
Tag: energy markets

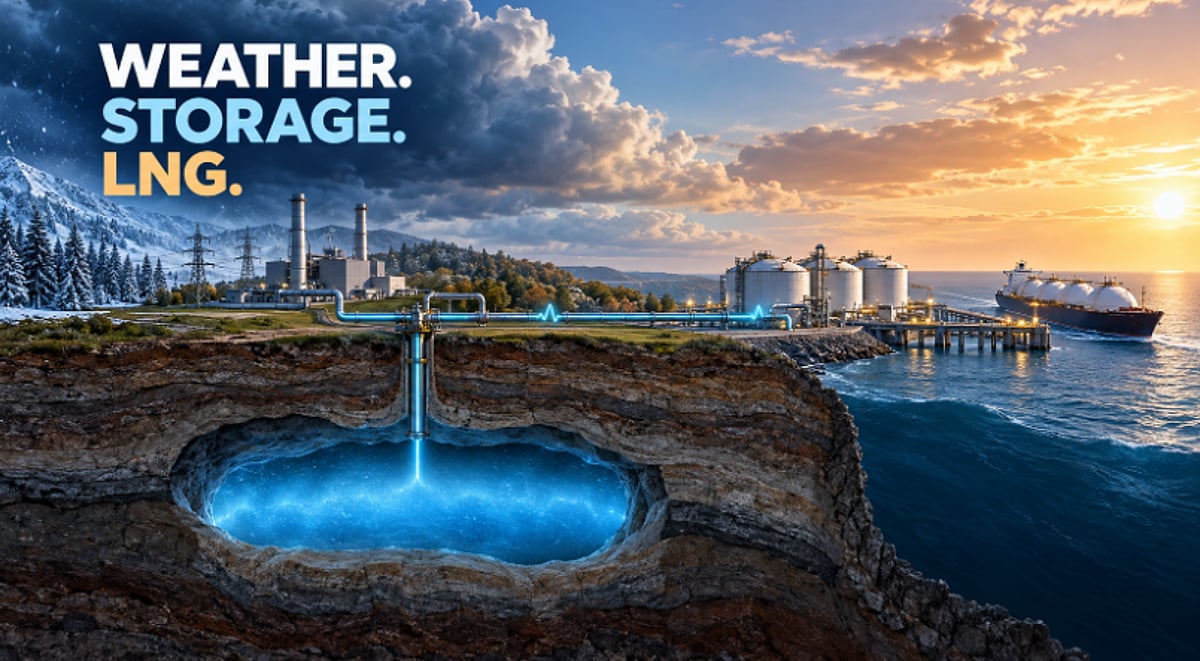
  • The Key Factors Behind Natural Gas Prices: Weather, Storage, and LNG Exports

    The Key Factors Behind Natural Gas Prices: Weather, Storage, and LNG Exports

    Natural gas prices are shaped by a complex mix of weather patterns, storage levels, and LNG export demand. Understanding how these forces interact helps businesses and traders anticipate market movements and make informed decisions.

    Weather’s Immediate Impact on Demand

    Weather conditions directly affect natural gas demand. Cold spells increase heating needs, while heatwaves drive up electricity demand for air conditioning, which often relies on gas-fired power plants. Traders closely monitor weather forecasts, and even slight changes in predicted temperatures can cause price fluctuations before the actual weather arrives. The location of weather events matters too: a cold snap near a pipeline bottleneck can create local shortages even if other regions have ample supply.

    Storage as a Market Buffer

    Natural gas storage facilities provide a cushion against seasonal demand variations. However, the effectiveness of this buffer depends on storage capacity and deliverability rates. A large inventory is less useful if it cannot be withdrawn quickly enough to meet sudden demand spikes. Weekly storage reports are evaluated against market expectations: a withdrawal that seems large may actually be smaller than anticipated, leading to price drops, while a modest withdrawal can boost prices if the market expected an injection. Comparisons with historical norms are crucial for assessing market tightness.

    LNG Exports Link Domestic and Global Markets

    LNG terminals act as large consumers of natural gas. Increased export demand tightens domestic supply, while outages can free up gas for local use. Global events, such as a cold winter in Asia or European storage rebuilding, can influence US prices through competition for LNG cargoes. According to the International Energy Agency’s Q1 2026 review, global LNG production increased by nearly 7% in 2025, with three-quarters of that growth occurring in the second half. The correlation between European and Asian benchmark prices reached 0.955, highlighting the strong linkage between markets.

    Navigating Conflicting Signals

    Market analysis becomes challenging when indicators point in different directions. A cold forecast may support higher prices, but a mild storage report could limit gains. Timing differences between weather forecasts, storage data, and LNG flows add complexity. A comprehensive approach considers scenarios rather than a single prediction.

    Building a Practical Forecast

    Effective price forecasts rely on scenario analysis. By considering various combinations of weather, storage, and export conditions, businesses can prepare for different outcomes. Monitoring changes in underlying assumptions is more valuable than focusing solely on price targets. Regional pipeline conditions also deserve attention, as local shortages can occur even in a balanced national market.

    In conclusion, the interplay of weather, storage, and LNG exports creates a dynamic environment for natural gas prices. Recognizing how these forces interact allows market participants to develop more resilient strategies.
  • Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Brent and WTI Hold Above $100

    Global oil prices slipped about 1% on Friday, September 18, marking a third consecutive session of declines. Brent crude futures fell $1.01 to $103.77 a barrel, while West Texas Intermediate dropped $1.03 to $100.88. Both benchmarks stayed above the $100 level after closing roughly 1% lower on Thursday.

    Saudi Pipeline Disruption and Market Response

    Earlier in the week, prices reached four-month highs after crude loadings at Saudi Arabia’s Yanbu Red Sea export hub were suspended. An attack on Saudi Arabia’s East-West pipeline damaged three pumping stations, according to satellite imagery and industry sources, and prompted Riyadh to cancel some deliveries to Europe.

    Traders warned that a prolonged shutdown could remove as much as 4% of global supply. However, Saudi Arabia is now working to restore about half of the pipeline’s capacity within days and is offering additional crude cargoes to Asian refiners through ship-to-ship transfers off Oman’s Sohar port. US Energy Secretary Chris Wright said crude should begin flowing through the pipeline within days, helping to ease immediate supply fears.

    Geopolitical Risks Remain

    The market largely shrugged off fresh cross-border strikes between Saudi Arabia and Yemen’s Iran-backed Houthis on Thursday. At the same time, Iran’s Revolutionary Guards Navy reported that a Togo-flagged oil tanker was struck while attempting an ‘illegal passage’ through the Strait of Hormuz, adding to uncertainty in an already fragile market.

    Analysts Cautious on Outlook

    JPMorgan said it had no clear baseline view for oil markets for the first time since the start of the US-Israeli war on Iran. Peace talks between the US and Iran have not resumed since an interim agreement collapsed in June. The conflict is expected to be discussed at the UN General Assembly next week, with an Iranian delegation scheduled to attend.

    What to Watch

    Market attention now centers on whether Saudi Arabia can restore disrupted pipeline flows and reroute enough crude to limit the impact of the attack. Any delay in repairs or new escalation in the Middle East could quickly reverse the recent downward move in prices.

  • Goldman Sachs Warns Brent Crude Could Surge Past $120 on Strait of Hormuz Disruptions

    Goldman Sachs Warns Brent Crude Could Surge Past $120 on Strait of Hormuz Disruptions

    Brent crude oil prices could surge above $120 per barrel in the fourth quarter if disruptions in the Strait of Hormuz persist, according to Goldman Sachs. The investment bank, however, clarified that such a sharp rally is not its base-case expectation.

    The warning comes as global oil markets remain on edge amid renewed geopolitical tensions in the Middle East. Brent crude recently climbed above $91 a barrel following fresh hostilities involving the US and Iran, raising concerns over potential supply disruptions.

    Shipping Routes Under Pressure

    Market sentiment has also been affected by threats from Iran-backed Houthi rebels in Yemen to impose a blockade on Saudi oil shipments. The warning has added to concerns over the security of key energy routes.

    With disruptions at the Strait of Hormuz, the Red Sea has become an increasingly important alternative for transporting crude from the Persian Gulf to global markets. Any disruption along this route could further tighten supplies and push prices higher.

    In a note dated July 20, Goldman Sachs analysts said escalating tensions in the region and a sharp decline in Persian Gulf oil flows had already contributed to the recent rebound in crude prices.

    Base Case Still Points to Lower Prices

    Despite highlighting the upside risks, Goldman Sachs maintained that its central forecast assumes geopolitical tensions gradually ease. Under that scenario, the bank expects Brent crude to average around $80 per barrel in the fourth quarter and decline to about $75 per barrel next year.

    The analysts cautioned, however, that risks remain skewed to the upside because of ongoing shipping disruptions through the Strait of Hormuz and the possibility of further interruptions in the Red Sea.

    China Demand May Limit the Rally

    Goldman Sachs noted that declining global oil inventories during the second quarter have left the market more exposed to supply shocks. At the same time, weaker crude imports by China and greater demand elasticity could help contain any sustained price spike.

    For investors seeking protection from prolonged geopolitical uncertainty linked to the Middle East and Russia, the bank recommended taking a long position in the European diesel timespread between December 2026 and March 2027.

    According to the analysts, diesel markets were already tight before the latest conflict, with continued Ukrainian attacks on Russian refineries, hurricane risks, extreme summer temperatures and refinery maintenance delays adding to supply concerns.

    Brent crude futures were last trading at $88.54 per barrel. Earlier this year, prices briefly surged above $126 a barrel during the initial phase of the US-Iran conflict.