Tag: financial inclusion

  • How Sameer Nigam Built PhonePe Into India’s Digital Finance Powerhouse

    How Sameer Nigam Built PhonePe Into India’s Digital Finance Powerhouse

    As India surged ahead in adopting digital payments at an unprecedented scale, a handful of entrepreneurs worked quietly behind the scenes to drive that transformation. One key figure is Sameer Nigam, founder and CEO of PhonePe, who turned a fledgling idea into one of the nation’s biggest fintech success stories.

    From a simple payment app to a comprehensive digital solution for millions of Indian consumers, PhonePe’s evolution reflects Nigam’s unwavering vision. His journey from engineer to entrepreneur is a blend of technical expertise and business acumen. With a computer science degree from the University of Mumbai and the University of Arizona, plus an MBA from Wharton, Nigam honed his skills at Shopzilla in the US before co-founding Mime360, a digital content distribution company later acquired by Flipkart. That acquisition introduced him to India’s booming e-commerce scene, where he held leadership roles in engineering and marketing.

    During those years, as India underwent digital transformation, Nigam spotted a critical gap in payment systems. In 2015, he co-founded PhonePe with Rahul Chari and Burzin Engineer. At a time when the Unified Payments Interface (UPI) was still nascent, the founders bet on its future rather than building a digital wallet. That bet paid off spectacularly. The 2016 demonetization campaign accelerated India’s shift to digital payments, and PhonePe surged ahead with its intuitive interface, fast bank integration, and easy onboarding for first-time digital users.

    Today, PhonePe is far more than a payments app. It offers insurance, mutual funds, lending, stock investments, merchant solutions, and app discovery. Nigam’s leadership philosophy centers on trust. Instead of aggressive marketing, he focused on building reliable technology capable of handling massive transaction volumes without hiccups. This engineering-first approach helped PhonePe thrive within India’s rapidly evolving digital payment ecosystem.

    Nigam also understood India’s diverse consumer base. By simplifying services and offering them in multiple languages, PhonePe reached users in metropolitan, suburban, and rural areas. For many Indians, the app was their first experience with digital financial services.

    Beyond payments, Nigam envisioned a complete digital ecosystem. Under his guidance, PhonePe expanded into wealth management, insurance distribution, lending, and merchant services. The launch of the Indus Appstore marked its entry into digital commerce, signaling ambitions far beyond fintech. This diversification is central to Nigam’s strategy of building a multi-product platform.

    Colleagues describe Nigam as a leader who prioritizes product-centricity and experimentation. His engineering mindset fosters a culture of innovation. Rather than chasing media hype, he lets the company’s products and performance speak for themselves, earning him recognition as a key fintech opinion-maker in India.

    As India moves deeper into the digital era, Nigam’s influence extends beyond PhonePe’s growth metrics. He has made digital payments a routine practice for small businesses and consumers alike. The future of India’s fintech industry may involve artificial intelligence, embedded finance, digital commerce, and greater financial accessibility. Given PhonePe’s trajectory, Nigam intends to be at the forefront of that evolution.

    This is not just an entrepreneurial success story; it is a story of reshaping an entire nation’s relationship with finance. Sameer Nigam has cemented his place as one of the architects of India’s digital financial revolution.

  • India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

    India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

    India’s fintech revolution has transformed digital finance through UPI, AI, and mobile-first innovation. From payments and investing to insurance and lending, the country’s top 10 fintech companies are driving financial inclusion, serving millions of users, and reshaping the future of banking.

    Overview

    India processes over 13 billion UPI transactions monthly, with the fintech market expected to exceed $150 billion by 2025, highlighting its rapid digital finance growth. The top 10 fintech firms lead payments, investing, insurance, and lending, serving millions of users while reshaping India’s financial ecosystem. AI, UPI, Aadhaar, and the Account Aggregator framework power these platforms, enabling faster services, smarter lending, and greater financial inclusion across India.

    The Leaders Redefining India’s Financial Landscape

    PhonePe

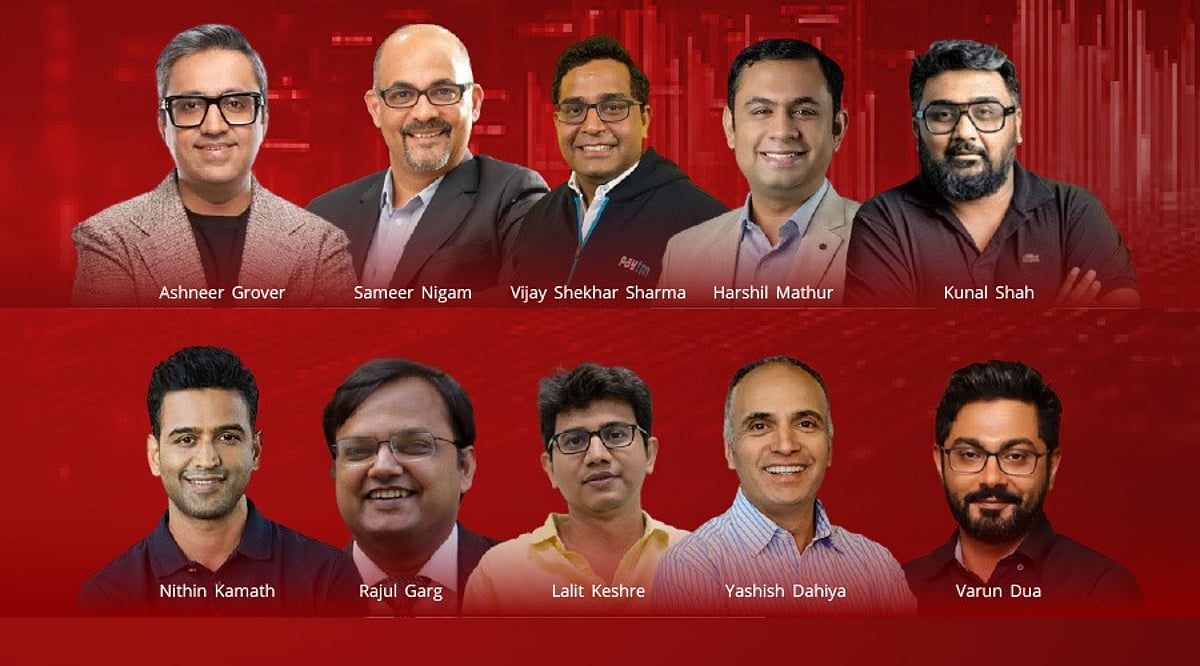
    PhonePe stands as India’s largest digital payments platform. Founded in 2015 by Sameer Nigam, Rahul Chari, and Burzin Engineer, it commands the UPI ecosystem with over 600 million registered users. The company’s revenue crossed ₹5,000 crore in FY24. Its platform spans payments, insurance, digital gold, and mutual funds. An IPO targeting a valuation between $9 billion and $10.5 billion remains on the horizon.

    Paytm

    Vijay Shekhar Sharma founded Paytm in 2000, making it one of India’s oldest fintech institutions. It began as a mobile recharge tool and expanded into wallets, merchant payments, lending, and wealth management. Annual revenues hover above ₹7,000 crore. Despite regulatory headwinds in recent years, Paytm holds a deep merchant network that keeps it embedded in India’s payment infrastructure.

    Razorpay

    Harshil Mathur and Shashank Kumar launched Razorpay in 2014 to solve a clear gap: businesses needed a reliable, developer-friendly payment gateway. The company now processes over $150 billion in annual payment volume and carries a valuation of approximately $7.5 billion. Its product suite covers payment gateways, business banking, payroll automation, and lending products used by thousands of Indian startups and enterprises.

    CRED

    Kunal Shah founded CRED in 2018 around a single insight: financially responsible people deserved better rewards. The platform targets high-credit-score users, offering reward points for credit card bill payments and expanding into personal loans, rent payments, and vehicle services. CRED’s valuation stands at around $6.4 billion, with estimated revenues crossing ₹2,000 crore in FY24.

    Zerodha

    Nithin Kamath and Nikhil Kamath built Zerodha in 2010 to lower the cost of investing. Discount brokerage and a clean trading interface on the Kite platform democratized equity markets for millions of retail investors. Revenue crossed ₹6,000 crore, and the company’s valuation sits between $3 billion and $4 billion. Zerodha remains profitable without external funding, which sets it apart in a sector that often burns capital for growth.

    Groww

    Lalit Keshre, Harsh Jain, Neeraj Singh, and Ishan Bansal founded Groww in 2016 to make investing simple for first-time users. The platform covers mutual funds, stocks, ETFs, IPOs, and fixed deposits under one roof. Its clean design and financial literacy focus helped it attract millions of young investors. Groww became a unicorn and continues expanding its wealth-tech offerings across India.

    Pine Labs

    Pine Labs traces its roots to 1998, making it one of the sector’s most seasoned players. Founded by Rajul Garg, the company built a merchant payment ecosystem spanning over one million touchpoints. Its POS machines and digital finance products serve retail chains and small merchants alike. Valuations range between $5 billion and $6 billion. Pine Labs bridges the offline and online commerce divide at meaningful scale.

    PB Fintech

    Yashish Dahiya founded PB Fintech in 2008, and it operates two major platforms: Policybazaar and Paisabazaar. Policybazaar became India’s largest online insurance marketplace, while Paisabazaar helps consumers compare loans and credit products. The company reported revenue growth of 33% year-on-year in recent results. Its market capitalization ranges between $4 billion and $5 billion.

    BharatPe

    Ashneer Grover and Shashvat Nakrani launched BharatPe in 2018 to serve a neglected segment: small merchants. The company introduced zero-fee UPI QR codes for shopkeepers and followed up with merchant loans and POS solutions. Its revenue surpassed ₹1,000 crore, and its merchant network now covers millions of micro and small retailers. BharatPe remains central to financial access for India’s informal business sector.

    ACKO

    Varun Dua founded ACKO in 2016 to reinvent insurance distribution. Traditional agents and lengthy paperwork gave way to a mobile-first platform where users buy, renew, and claim policies entirely online. ACKO offers motor, health, and travel insurance with faster claim settlements. Its digital-first model has attracted a growing customer base, and the company stands among India’s most prominent insurtech names.

    What These Leaders Share

    Several common threads run through all ten companies on this list: each built its product around mobile-first access, reaching users traditional banks could not. All ten leverage UPI, Aadhaar, or the Account Aggregator framework as foundational infrastructure. AI now powers credit scoring, fraud detection, and customer support across most platforms. Financial inclusion remains a stated goal, whether the customer is a salaried professional or a street-side vendor.

    Final Words

    India’s top fintech leaders did not simply build successful businesses. They rewired how a nation of 1.4 billion people manages money. Each company on this list solved a specific friction point, whether that was payment acceptance for merchants, affordable brokerage for retail investors, or instant insurance for urban professionals. The result is a financial ecosystem that is faster, cheaper, and more accessible than it was even five years ago. The next phase will demand more: regulatory clarity, sustainable unit economics, and deeper penetration into rural markets. The foundations, however, are already strong. India’s fintech sector enters the second half of this decade not as a promising experiment but as a proven engine of economic transformation. The names above have earned their place at the forefront. Now comes the harder task of staying there.

  • Women in Fintech: How Female Leaders Are Driving Innovation and Inclusion in India

    Women in Fintech: How Female Leaders Are Driving Innovation and Inclusion in India

    By Santosh Kadali

    A Sector Built on Access, Now Building for Women

    Fintech in India carries a promise of inclusion at its core. It brings banking and credit to people who never had easy access to either. Women sit at the center of this story directly. President Droupadi Murmu made this point clear at the Black Swan Summit in Bhubaneswar earlier this year. She said India’s fintech journey should be remembered not just for innovation, but for inclusion and gender justice.

    She further shared a striking number too. India has opened over 57 crore Jan Dhan accounts, and more than 56 percent of them belong to women. This detail shows something simple. Financial technology, when built with intent, can close old gaps in access instead of widening them.

    Funding Tells a Mixed Story

    Women-led fintech startups have started to draw serious investor interest. The numbers still show a clear gap, though. In 2024, women-led startups across India raised close to $5 billion. That sum made up 15.2 percent of all funding that went to women-led startups worldwide that year. Fintech stood out as the top sector within that total. It pulled in close to $267 million across 136 deals.

    A report from the Department for Promotion of Industry and Internal Trade found something worth noting. 42 percent of fintech startups in India have at least one woman director or founder. That figure runs well ahead of India’s broader corporate sector, where women hold just 18 percent of board seats. Growth has not stayed limited to big cities either. Women-led fintech ventures outside Tier-1 cities grew by 44 percent over the last decade, says the Ministry of Commerce and Industry.

    The Leadership Gap Still Runs Deep

    Progress at the founder level has not carried over fully into top leadership. Industry research from 2023 to 2025 shows a clear pattern. Women hold fewer than 15 percent of top jobs at Indian fintech firms. The share of women among founders and co-founders sits even lower, close to 10 to 12 percent. Representation drops further still in investment and business-decision roles.

    A KPMG India and AIMA survey from 2026 paints a similar picture across corporate India as a whole. The survey found that 79 percent of women professionals want leadership roles. Only 1 percent of them currently hold a board-level position though. Women now hold 20 percent of leadership roles in mid-market companies, up from 13 percent in 2016.

    This gain matters, though it still falls far short of real parity. The survey’s authors point to a clear reason behind this gap. Structural design, inconsistent execution and uneven accountability across companies keep women from moving past mid-career roles into senior ones. This happens even when ambition and talent are both present.

    Women Leaders Setting the Pace

    Individual leaders across India’s fintech space show what this progress looks like in real terms. Roshni Aslam, co-founder of GoSats, has helped build India’s first rewards app that gives users Bitcoin and gold on their purchases. The platform has grown past 1.1 million users under her work. Stories like hers keep showing up across the sector now, from payments and lending startups to wealth-tech platforms.

    Voices from the wider fintech industry echo the same point about what these leaders bring to the table. Maya Kumar, an executive at fintech firm Banked, has said diversity brings a range of perspectives that form the base of purpose-driven innovation.

    She added that the role women play in driving the sector’s next phase of growth deserves real weight. This kind of leadership shapes more than who runs fintech companies. It shapes how the products themselves get built, tested and delivered to a wide range of users.

    Final Thoughts

    India’s fintech sector stands at a turning point. It has already shown that technology can widen financial access at scale. The next stage of its growth will bring credit expansion, wealth creation and AI-driven finance. This stage will test something important. Can the industry widen access at the leadership level too? Women have already shown their ability to build products, raise funding and lead companies in this space.

    Closing the remaining gaps in senior leadership and investment decisions will decide something bigger. It will decide whether fintech in India truly serves everyone it claims to serve, or keeps its biggest rewards limited to a narrow few. The answer will shape not just the industry’s growth, but its legacy too.

    FAQs

    1. Why are women important to India’s fintech sector?

    Women are driving innovation, building successful startups, improving financial inclusion, and designing products that better serve a diverse customer base across India.

    2. How many fintech startups are there in India?

    India has more than 10,000 fintech startups, making it one of the world’s fastest-growing fintech ecosystems with strong growth in digital payments and financial services.

    3. What challenges do women face in the fintech industry?

    Despite progress, women remain underrepresented in senior leadership, board positions, investment decision-making, and founder roles due to structural and organizational barriers.

    4. How are women-led fintech startups performing in India?

    Women-led fintech startups are attracting increasing investor interest, with fintech emerging as one of the top-funded sectors among women-led ventures in recent years.

    5. What is the future of women in India’s fintech industry?

    As fintech expands into AI-driven finance, digital lending, and wealth management, greater representation of women in leadership and investment roles will be key to building a more inclusive financial ecosystem.

  • India’s Fintech Revolution: Unlocking a Trillion-Dollar Market Opportunity

    India’s Fintech Revolution: Unlocking a Trillion-Dollar Market Opportunity

    India’s financial landscape has undergone a remarkable transformation over the past decade. What began as a push toward digital payments has evolved into a thriving fintech ecosystem that is reshaping how millions save, borrow, invest, and transact daily.

    Traditional banking with its long, tedious paper forms has given way to financial services accessible at the tap of a smartphone. The country’s robust digital public infrastructure, expanding internet access, and a young, tech-savvy population have created fertile ground for fintech innovation.

    Today, India boasts one of the world’s largest digital payment ecosystems, alongside a growing network of startups building tools for lending, insurance, wealth management, and embedded finance. With artificial intelligence (AI) emerging as a new layer of innovation, many industry experts believe India’s fintech sector is entering its next growth phase — one that could eventually make it one of the country’s trillion-dollar industries.

    UPI Became a Game Changer

    The launch of the Unified Payments Interface (UPI) in 2016, created by the National Payments Corporation of India (NPCI), gave a huge boost to the fintech revolution. UPI enables instant payments from one bank account to another via mobile phones.

    Consumer behavior shifted dramatically. QR codes are now ubiquitous across the country — from roadside tea stalls and vegetable vendors to shopping malls and multinational corporations. Digital payments are no longer confined to urban users; they have become accessible in smaller towns and rural areas.

    The success of UPI opened the door for further fintech innovations. Startups began crafting offerings for lending, saving, investing, and insurance based on users’ digital payment histories.

    Booming Fintech Ecosystem

    India’s fintech applications extend far beyond payments. Fintech startups now operate across digital lending, wealth management, insurtech, personal finance, embedded banking, and cross-border payments.

    The large number of unbanked individuals and micro, small, and medium enterprises (MSMEs) has created immense opportunities for fintech companies to fill gaps left by traditional banking. These startups help individuals access banking services through alternative credit scoring, paperless onboarding, and quick loan approvals — even for those with low or no credit ratings.

    Digital lending has become a reliable source of working capital for small enterprises. Meanwhile, investment fintech platforms have opened up mutual funds, shares, and government securities to novice investors.

    AI Powering the Next Wave of Innovation

    Artificial intelligence is emerging as the backbone of fintech innovation. Organizations are using AI algorithms to detect fraud, automate customer service, and improve credit underwriting.

    Banks and fintech companies leverage AI to enhance compliance processes, monitor suspicious transactions, and reduce operational expenses. Loan approvals are faster, and risk assessment improves through the use of alternative data sources.

    As digital transactions increase, AI will be crucial for handling larger volumes securely and conveniently.

    Why Investors Remain Optimistic

    While global venture capital investment has experienced ups and downs, India continues to attract strong investment in fintech. This is not due to cyclical trends but to structural factors.

    The country’s growing digital economy, widespread smartphone usage, supportive government policies, increased internet penetration, and the world’s largest real-time payment system collectively create a solid foundation for future growth. Financial inclusion presents significant opportunities, as many Indians enter the formal financial system for the first time.

    Challenges on the Road Ahead

    Rapid growth is not without risks. Cybersecurity threats, digital fraud, and data privacy concerns have heightened focus on consumer safety. Regulations from the Reserve Bank of India are tightening, especially regarding digital lending and payment processes.

    Profitability remains an issue for many fintech companies operating with zero-cost or heavily subsidized products. Ultimately, consumer trust will be the deciding factor.

    The Trillion-Dollar Opportunity

    India’s fintech evolution extends beyond replacing cash with digital payments. It involves building a complete financial ecosystem where payment systems, lending services, investment platforms, insurance schemes, and commerce increasingly integrate across digital platforms.

    The coming decade will see increased partnerships among banks, fintech companies, regulators, and technology providers. Artificial intelligence, digital public infrastructure, and supportive policies will play pivotal roles in accelerating this process.

    Given the current momentum, India’s fintech sector could become one of the most notable success stories of the Indian economy — contributing to financial inclusion, capital generation, and the transformation of banking for over a billion people.

  • How Michael Gastauer Built Black Banx into a Borderless Digital Banking Giant

    How Michael Gastauer Built Black Banx into a Borderless Digital Banking Giant

    Michael Gastauer, a German self-made billionaire and technology investor, is best known as the founder and chairman of Black Banx Group. His vision: banking that works across borders with the speed and accessibility of modern digital services. Under his leadership, Black Banx has grown into a privately held digital banking group serving over 100 million customers in more than 180 countries.

    Black Banx offers digital financial services to private, business, and institutional clients, focusing on international account access, cross-border payments, and support for multiple fiat and crypto currencies. Rather than being limited by geography, the platform is designed for customers whose personal and commercial lives span national boundaries.

    Gastauer’s background in financial services spans asset management and online payments, giving him deep experience in the infrastructure behind international transactions and technology-led client service. He launched Black Banx in 2015, combining those earlier ventures into a global banking proposition.

    Financial inclusion is a cornerstone of the strategy. Digital account opening and remote access reduce the need for physical branches, particularly in markets where consumers and businesses have historically had limited access to the international financial system. For Gastauer, technology is both an efficiency tool and a way to widen participation in global commerce.

    Looking ahead, Gastauer emphasizes real-time payments, artificial intelligence, digital identity, and automated compliance as key drivers of change. His founder-led approach has built systems that scale while maintaining a consistent digital experience.

    Beyond Black Banx, Gastauer serves as chairman of the Gastauer Family Office, which manages diversified investments in technology, financial services, private equity, real estate, contemporary art, crypto assets, and global capital markets. Through the Gastauer Foundation, he supports initiatives in financial inclusion, education, entrepreneurship, environmental sustainability, and biodiversity conservation.

    This combination of commercial success and philanthropy illustrates a defining feature of modern founder leadership: building a global platform requires attracting specialist teams, adapting to different markets, and maintaining a clear purpose as the organization grows. Gastauer’s narrative emphasizes continuity of vision, from early digital payments opportunities to a banking group serving customers at international scale.

    As banking moves from nationally defined products to connected international services, Gastauer’s perspective is especially relevant. Customers increasingly expect accounts, payments, and support to remain available wherever they relocate, establish companies abroad, or trade in multiple currencies. Meeting that expectation requires combining product design with a dependable operational foundation. Gastauer’s contribution at Black Banx is both entrepreneurial and architectural: identifying a global need, assembling the technology and teams, and maintaining clear direction as the platform reaches a larger and more diverse audience.

  • 10 African Fintech Startups Shaping Digital Finance in 2026

    10 African Fintech Startups Shaping Digital Finance in 2026

    Africa’s fintech sector continues to gain momentum, with startups across the continent raising approximately $3.4 billion in disclosed funding during 2025—a 33% increase from the previous year. The positive trend has extended into 2026, with fintechs securing $187.1 million in the first quarter across 21 deals. These figures underscore sustained investor interest and growing demand for digital financial tools that help people send money, save, borrow, and run businesses more efficiently.

    Here are the top 10 African fintech startups leading innovation in payments, lending, merchant services, and financial inclusion.

    1. OPay

    OPay has become a major payments platform in Nigeria, offering transfer features, merchant tools, and other financial services within a single app. It serves individuals and small to medium-sized enterprises (SMEs) seeking quick and easy payment solutions, making it one of the most recognizable fintech companies in the region.

    2. Moniepoint

    Moniepoint enables small businesses to make payments and access banking services easily. By focusing on merchants, it has emerged as a top financial platform for SMEs in Nigeria, addressing the real payment challenges faced by everyday business owners.

    3. Flutterwave

    Flutterwave provides business-to-business and business-to-consumer payment services across Africa and beyond. Its platform facilitates checkout, payouts, and cross-border payments, making it a go-to solution for businesses that need seamless international transactions.

    4. Yoco

    Yoco serves small businesses in South Africa with card readers and point-of-sale tools. It simplifies card payments for smaller merchants, offering easy setup and clear control for business owners who want to accept digital payments without complexity.

    5. Paymob

    Paymob is a digital payment platform used by retailers in Egypt and neighboring regions. It helps businesses accept various payment methods and process transactions easily, playing a vital role in the region’s digital economy.

    6. MNT-Halan

    MNT-Halan combines lending, payments, and consumer finance on a single platform. It serves customers who need flexible credit and easy access to everyday financial tools, securing a strong position in North Africa’s growing fintech market.

    7. PiggyVest

    PiggyVest is an app that enables people to save and invest. Its strength lies in its simplicity and ease of use, making saving and investing accessible to a broad audience. It has gained popularity for its stress-free functionality.

    8. Tala

    Tala provides short-term credit through data-driven lending, reaching users often excluded from traditional banking. Its model is crucial in markets where access to credit remains limited, offering quick financial support when needed.

    9. Interswitch

    Interswitch remains a key part of Africa’s payments infrastructure, especially in Nigeria. It supports card processing, transaction systems, and enterprise payment services used by many businesses, earning strong trust and reach through its long market presence.

    10. PalmPay

    PalmPay has grown quickly as a mobile payments platform built around convenience. It excels in consumer payments, merchant acceptance, and customer incentives, with a simple interface that appeals to a broad user base.

    Future Outlook

    The African fintech market is advancing through clear use cases rather than a single broad direction. Nigerian platforms like OPay, Moniepoint, Flutterwave, and PalmPay are building payment rails for consumers, merchants, and small businesses. In South Africa, Yoco helps smaller retailers accept card payments more easily. In Egypt, Paymob and MNT-Halan are expanding digital payments and credit access. In Kenya, Tala continues to serve users who need short-term loans. The companies that will lead are those solving market-specific problems with products people use every day.

    FAQs

    Why is Africa’s fintech sector growing so rapidly in 2026?
    Rising smartphone adoption, expanding internet access, growing demand for digital payments, and the need for financial services reaching underserved individuals and small businesses are driving growth.

    Which African countries have the strongest fintech ecosystems?
    Nigeria, South Africa, Egypt, and Kenya remain the continent’s leading fintech hubs, supported by active startup ecosystems, strong investor interest, and expanding digital infrastructure.

    What services do African fintech startups commonly offer?
    Most provide digital payments, money transfers, merchant solutions, lending, savings, investment, mobile wallets, and financial management tools for consumers, entrepreneurs, and small businesses.

    Why are investors interested in African fintech startups?
    Investors see strong growth opportunities because these companies address real financial challenges, expand financial inclusion, serve large underserved markets, and record steady user adoption and funding momentum.

    Which African fintech startups are worth watching in 2026?
    Companies including OPay, Moniepoint, Flutterwave, Yoco, Paymob, MNT-Halan, PiggyVest, Tala, Interswitch, and PalmPay are expected to remain among Africa’s most influential fintech innovators in 2026.

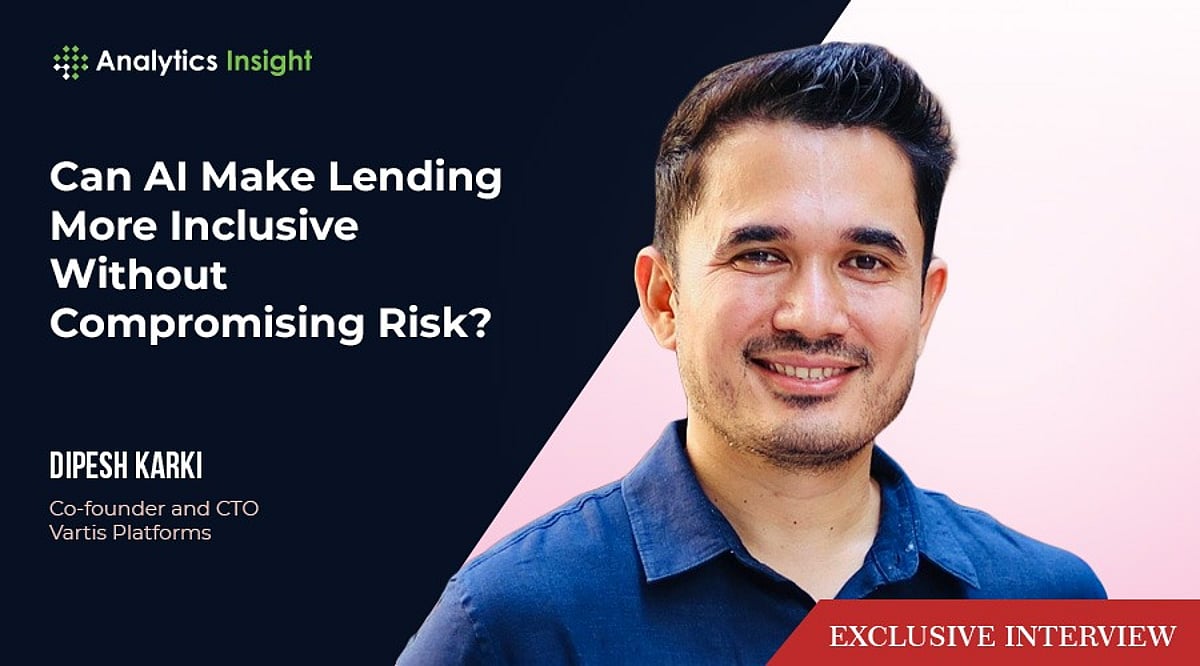
  • How AI-Native Lending Is Reshaping Credit Delivery: An Interview with Vartis Platforms’ Dipesh Karki

    How AI-Native Lending Is Reshaping Credit Delivery: An Interview with Vartis Platforms’ Dipesh Karki

    Artificial intelligence, machine learning, predictive analytics, and automation are transforming India’s digital lending ecosystem. Lenders are shifting from traditional assessments to data-driven decision-making, enhancing underwriting, fraud detection, collections, and portfolio monitoring. This technological evolution supports broader financial inclusion by allowing lenders to assess underserved and new-to-credit borrowers through alternative data and a comprehensive view of financial behavior.

    Dipesh Karki, Co-founder and CTO of Vartis Platforms, emphasizes that the future of lending lies in AI-native ecosystems that embed intelligence throughout the credit delivery process. In an exclusive interview with Analytics Insight, he discusses the impact of these technologies on underwriting, risk management, compliance, and how Vartis Platforms is using data science to foster a more efficient and inclusive lending environment. Here are the excerpts from the interview:

    How are AI, Machine Learning, and Automation Transforming Underwriting and Risk Management in Digital Lending?

    The biggest shift we are seeing in digital lending is the move from static, rules-based underwriting to intelligent, data-driven decision-making. Traditionally, lending decisions relied heavily on bureau scores and predefined eligibility criteria. While those remain important, they often provide only a partial view of a borrower’s financial profile.

    AI and machine learning allow lenders to analyse a much broader set of signals and identify patterns that are difficult to detect through conventional methods. These models can continuously learn from repayment behaviour, portfolio performance, and changing market conditions, helping improve risk assessment over time.

    From a risk management perspective, AI is enabling more proactive monitoring. Rather than assessing risk only at the point of loan origination, lenders can continuously evaluate portfolio health, identify early warning signals, and take corrective action before risks escalate.

    Automation complements this by streamlining operational processes such as application screening, verification, fraud checks, and policy enforcement. This not only improves efficiency but also ensures greater consistency in decision-making. Ultimately, the combination of AI, machine learning, and automation is helping the industry build lending systems that are faster, more scalable, and better equipped to manage risk.

    Why is Alternative Data Becoming Increasingly Important in Expanding Credit Access Beyond Traditional Bureau-Led Assessment Models?

    India has made significant strides in expanding access to formal credit, but a large segment of the population remains either new-to-credit or underrepresented in traditional credit bureau systems. If lenders rely solely on bureau data, they risk excluding many creditworthy individuals who simply lack an extensive borrowing history.

    Alternative data helps address this challenge by providing additional insights into a borrower’s financial behaviour and repayment capacity. With the growth of digital financial services, lenders today can evaluate indicators such as cash-flow patterns, income consistency, transaction behaviour, and other consent-based financial data points to build a more comprehensive risk profile.

    The emergence of digital public infrastructure and frameworks that enable secure data sharing is further accelerating this shift. Instead of assessing borrowers based only on their past credit history, lenders can increasingly evaluate their current financial health and behavioural patterns.

    This approach creates a win-win outcome. Borrowers gain access to formal credit opportunities, while lenders can make more informed risk decisions and expand responsibly into previously underserved segments. In many ways, alternative data is becoming a key enabler of financial inclusion at scale.

    What Role does Predictive Analytics Play in Improving Borrower Assessment, Repayment Forecasting, and Collections Efficiency?

    Predictive analytics has become a critical component of modern lending because it allows organisations to move from reactive decision-making to proactive risk management.

    In underwriting, predictive models help estimate the likelihood of repayment by analysing relationships between historical borrower behaviour and future outcomes. This enables lenders to make more accurate credit decisions and improve portfolio quality.

    Beyond loan origination, predictive analytics plays an important role in portfolio monitoring and repayment forecasting. By identifying behavioural patterns and early indicators of financial stress, lenders can anticipate potential delinquencies and take preventive measures before accounts deteriorate.

    Collections is another area where predictive analytics is creating significant value. Rather than applying a uniform collections strategy across all borrowers, lenders can prioritise accounts based on risk levels, predict repayment propensity, and optimise engagement strategies accordingly. This improves operational efficiency while also creating a better borrower experience.

    As lending portfolios become larger and more complex, predictive analytics will continue to be a foundational capability for improving decision-making across the entire credit lifecycle.

    How is Automation Helping Reduce Turnaround Times While Ensuring Consistency, Governance, and Regulatory Compliance?

    Historically, lending operations involved multiple manual touchpoints, which increased processing times and introduced variability in outcomes.

    Today, automated workflows can manage activities such as onboarding, KYC verification, document validation, eligibility checks, underwriting workflows, and loan servicing with far greater speed and accuracy. This significantly reduces turnaround times and improves the customer experience.

    Equally important is the role automation plays in governance and compliance. Automated systems ensure that policies are applied consistently across all applications and that decisions are made within predefined risk and regulatory frameworks. This reduces the possibility of operational errors and strengthens control mechanisms.

    From a regulatory standpoint, automation also improves transparency by creating clear audit trails and documentation for every stage of the lending process. As lending volumes continue to grow, automation will remain critical for balancing operational efficiency with accountability and compliance.

    How Could AI-Native Lending Models Reshape the Future of Credit Delivery in India?

    We are moving towards a future where AI is not simply supporting lending processes but is becoming embedded across the entire lending lifecycle. That is what defines an AI-native lending model.

    In such a model, intelligence is integrated into customer acquisition, underwriting, risk assessment, fraud detection, servicing, collections, and portfolio management. Decisions become more dynamic because models can continuously learn from new data and adapt to changing borrower behaviour and build foresights.

    For India, the opportunity is particularly significant. The combination of digital public infrastructure, increasing digital adoption, and access to richer financial datasets creates a strong foundation for AI-driven innovation in credit delivery. AI-native lending can help reduce friction in the borrowing journey, improve risk assessment accuracy, and enable a better personalization tailored to their need. At the same time, the industry must ensure that AI adoption is responsible and transparent. Explainability, fairness, data privacy, and regulatory compliance will be critical considerations as these models become more prevalent. The goal should not simply be faster lending, but smarter and more inclusive lending that benefits both borrowers and financial institutions.

    How is Vartis Platforms Leveraging Technology and Data Science to Create a More Efficient, Inclusive, and Sustainable Lending Ecosystem?

    At Vartis Platforms, technology and data science are at the core of how we build financial products and scale lending operations. With LenDenClub, InstaMoney, and Vartis One operating within a unified ecosystem, we could leverage shared technology infrastructure, AI-driven credit intelligence, and advanced analytics across multiple parts of the lending value chain.

    Our focus is on creating systems that enable faster decision-making, stronger risk management, and improved customer experiences. We use data science and machine learning to enhance credit assessment, monitor portfolio performance, strengthen fraud detection capabilities, and drive operational efficiencies.

    Through Vartis One, we are also investing in scalable technology architecture that supports both current business needs and future growth opportunities. This allows us to build modular, adaptable platforms capable of supporting evolving lending models and increasing transaction volumes.

    A key objective for us is to make lending more accessible without compromising risk discipline. By combining technology, data-driven insights, and automation, we aim to expand responsible credit access, improve operational efficiency, and create a more sustainable lending ecosystem. We believe the future of lending will be defined by organisations that can successfully balance innovation, risk management, and financial inclusion, and that is the direction we are building towards at Vartis Platforms.

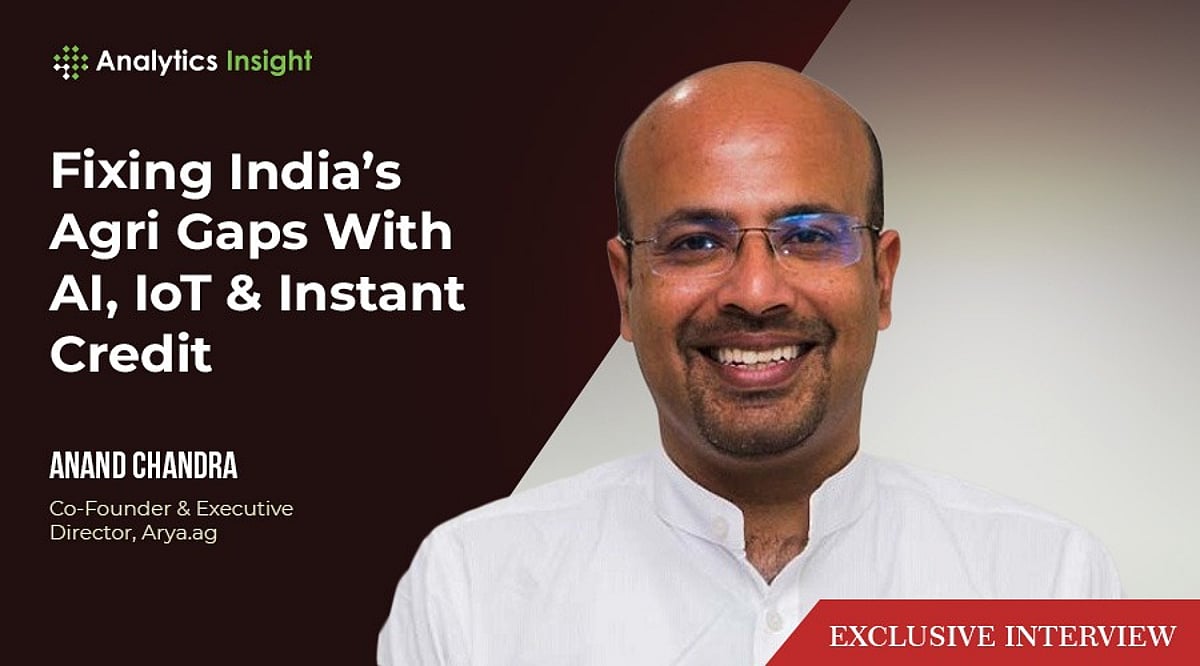
  • How Arya.ag Combines Satellite AI and Agri-Fintech to Reduce Post-Harvest Losses and Boost Farmer Credit

    How Arya.ag Combines Satellite AI and Agri-Fintech to Reduce Post-Harvest Losses and Boost Farmer Credit

    In an interview with Analytics Insight, Anand Chandra, Co-Founder & Executive Director of Arya.ag, discusses how the company leverages satellite imagery, AI, IoT, and agri-fintech to transform India’s grain supply chain, reduce post-harvest losses, and unlock credit for farmers.

    How does Arya.ag use AI, IoT, and satellite data across the grain value chain, and what makes your tech deployment accurate across diverse geographies and crops in rural India?

    Arya.ag integrates technology to create the most practical value in the agricultural supply chain. Satellite imagery is a key layer in our stack. It enables predictive analytics on crop health, weather-related risks, and biotic stress. These insights directly inform our procurement planning and advisory services. For example, we can flag early warning signs of crop failure or pest outbreaks, allowing farmers and buyers to make timely decisions.

    AI is used for quality grading of grains and for risk scoring that determines a farmer’s credit eligibility. IoT systems are embedded into our hermetic storage infrastructure to support real-time surveillance and inventory management, particularly in warehouses close to the farm.

    What ensures accuracy is how these technologies are layered and localised. We operate across 11,000 near-farm storage points in 425 districts, covering 21 states. The models we use are trained using regional parameters and adapted to local cropping cycles and behaviour. This is not a one-size-fits-all deployment. The stack evolves with geography, making it both context-aware and scalable.

    By turning grain into digital assets, how is Arya.ag reshaping farmer access to credit, and what does this mean for financial inclusion at scale?

    Once produce enters our storage network, it is graded, weighed, and converted into an electronic balance. This balance is a digital representation of value that can be offered as collateral for credit or sold through our platform. This method unlocks access to formal finance without relying on land records, income statements, or traditional credit scores. More than 40 percent of our borrowers are accessing formal finance for the first time. Crucially, this creates an alternative to informal financial systems. Farmers no longer need to depend on local traders or commission agents for liquidity. With digital visibility and secure collateral, they can take loans based on stored produce and choose when to sell. The credit process is designed for speed and transparency. Disbursement happens in minutes, repayments are tied to commodity sales, and all transactions are visible to stakeholders. It is a system that brings financial inclusion to fragmented, underbanked regions, while also de-risking credit by focusing on the commodity rather than the farmer alone.

    What is one AI or IoT application that surprised you with its impact, and how are these insights actually enabling farmers or partners on the ground?

    Biotic stress detection through satellite imagery has been one of the most impactful use cases. We piloted this capability in select districts through our FPO partners, aiming to improve crop visibility. During one cycle, the system flagged early-stage pest risks in maize before they were visible on the ground. This advisory was delivered through our app and verified by our field teams. The FPO acted on the alert, which helped farmers intervene early and significantly reduce crop losses.

    What made this solution stand out was not just the outcome but the cost at which it was delivered. Satellite-based insights have typically been expensive or limited to large enterprises. We have made this capability available at a price rural institutions can afford. That combination of affordability, speed, and accuracy makes it practical for wide-scale deployment.

    It also reinforced an important lesson. Technology only creates value when insights are timely, actionable, and delivered through a trusted interface that connects digital systems to people on the ground.

    With poor connectivity and low digital trust in rural India, what is the most realistic way to scale agritech, and where are policymakers or innovators missing the mark?

    The most realistic path to scale is to decouple digital outcomes from digital literacy. Farmers do not need to become full-time app users. What they need is a consistent experience where technology works seamlessly in the background, delivering visible benefits.

    This is where human-led, tech-enabled models work well. A warehouse operator helping a farmer access finance or an FPO lead executing a trade creates more confidence than a digital-only system. Trust builds when the farmer sees the grain being weighed, tagged, and recorded as an asset they can track and use.

    Affordability is another critical factor. As we saw with satellite-based pest alerts, the cost at which a solution is available determines whether it can move beyond pilot projects. Technologies that are affordable, modular, and localised are the ones that will scale.

    Most importantly, the agritech sector must shift from a solution-first mindset to a problem-solving approach. The focus should be on solving specific, real-world problems, such as post-harvest loss, delayed payments, or access to working capital. When technology addresses pain points rather than pushing pre-built products, adoption becomes organic and sustainable.

    How can India build a rural workforce that is fluent in both agriculture and technology, and how can we encourage global adoption?

    India can build an agri-tech fluent workforce not just through training programs but by creating roles where agriculture and technology are integrated. We have seen this with warehouse managers, sourcing leads, FPO tech operators, and credit enablers who earn by enabling farmers through digital tools.

    This alignment of incentives drives faster learning and adoption. Rural India is not unfamiliar with technology. When there is visible utility and income opportunity, adoption is fast. For instance, the rapid rise of UPI payments among vegetable vendors and rickshaw drivers happened because it solved a real-world problem in a simple, cost-free way. Agri-tech will follow a similar path. The more a tool improves efficiency, reduces loss, or increases income, the more quickly it will be embraced even in low-literacy or low-connectivity environments.

    On the global front, India has an opportunity to set a benchmark. Countries in Africa, Southeast Asia, and Latin America face similar post-harvest and financial access challenges. If India can demonstrate that decentralised infrastructure, tech-led visibility, and commodity-backed finance can succeed in harsh conditions, it provides a practical model for others to adopt.