Tag: insurtech

  • Checkr Debuts AI Verification Platform for U.S. Auto, Life, and Home Insurers

    Checkr Debuts AI Verification Platform for U.S. Auto, Life, and Home Insurers

    Checkr, an AI-powered verification platform for high-stakes decisions, has launched a new insurance solution for U.S. auto, life, and home insurance carriers. The platform is designed to give insurers faster access to verified applicant information during the quoting and underwriting process.

    Why Insurers Need Faster Verification

    Consumers are shopping around more before buying coverage. According to J.D. Power’s 2026 Insurance Shopping Study, U.S. consumers now get an average of 3.5 quotes before purchasing a policy — the highest level the study has recorded.

    Digital purchasing is also climbing. Nearly 48% of new auto insurance policies are now purchased online, up from 36% five years ago. That shift means insurers must evaluate more prospective customers before knowing which applicants will eventually become policyholders.

    Traditionally, insurers had to choose between conducting detailed checks early in the process or relying on applicant-supplied information and verifying it later.

    What the Platform Offers

    • Direct access to identity records, criminal information, public records, and driving data from more than 2,400 government sources.
    • Daily data refreshes and classification across more than 250 offense categories.
    • Coverage of more than 260 million profiles, representing 96% of U.S. adults.
    • Up to 20% more driving, criminal, and public records than legacy verification providers.
    • Improved applicant matching to reduce manual review and provide more structured information for underwriting decisions.

    Pay-Per-Bind Pricing Model

    The commercial model differs from conventional per-transaction verification. Carriers pay when an applicant becomes a policyholder, not each time a check is requested.

    Hippo is among the insurers using additional Checkr data during underwriting. Hippo Chief Underwriting Officer Ilya Shnol said the additional data signals are provided earlier in the assessment process and support more consistent underwriting decisions.

    Checkr has made the insurance platform available to carriers across the United States.

  • On-Demand Rental Car Insurance: How Insurtech Is Reshaping Travel Protection

    On-Demand Rental Car Insurance: How Insurtech Is Reshaping Travel Protection

    The travel insurance landscape is undergoing a digital transformation, and the rental car counter is where the change is most tangible. Insurtech companies are replacing the traditional, pressure-filled sales pitch with data-driven, on-demand protection that travelers can activate in seconds from their smartphones.

    The Rental Counter Shock vs. One-Tap Coverage

    Imagine arriving at a busy U.S. airport, tired from a long flight. At the rental counter, the agent offers a collision damage waiver (CDW) for $30–45 per day—an add-on that could nearly double the cost of a week’s rental. Now, imagine a traveler who, one minute before pickup, opens an app, taps “buy,” and secures standalone rental car insurance for a fraction of that price. That scenario is no longer hypothetical.

    Insurtech platforms are making on-demand rental car protection possible through mobile apps, streamlining everything from purchase to claims. According to Fairfield Market Research, the global on-demand insurance market is projected to grow from roughly $110.6 billion in 2025 to $173.7 billion by 2034, with automobile and mobility segments representing nearly 40% of that value. Rental car protection is a prime use case driving this expansion.

    CarInsuRent, a London-based digital-first provider founded in 2017, exemplifies the model. It sells single-trip and annual policies online, covering damage, theft, and items often excluded at the counter. Let’s compare the legacy rental desk model with app-based alternatives—no marketing fluff, just the numbers and mechanics that matter.

    The Legacy Model: How Traditional Rental Desk Insurance Works (and Where It Breaks)

    Car rental companies traditionally sell CDW, LDW, supplemental liability, and personal accident cover at the counter. Pricing reflects a one-size-fits-all approach:

    • CDW alone typically runs $15–30 per day in North America and Western Europe.
    • Full bundles climb to $40–60 per day—meaning rental desk insurance can cost double the rental rate over a seven-day holiday.
    • Standard waivers routinely exclude tyres, windscreens, undercarriage, keys, and administrative or loss-of-use charges.

    According to CarInsuRent, 68% of renters felt “pressured” by rental agents to make immediate decisions at the counter. Many travelers assume their personal auto insurance or credit card provides sufficient coverage, but gaps are common for international rentals, certain vehicle types, and higher excess amounts. The legacy model lacks transparency and is full of hidden costs—a challenge the industry is only now addressing.

    Because on-demand protection can be activated instantly, insurtech platforms must protect themselves against opportunistic claims. Deploying advanced AI fraud detection, behavioral biometrics, and real-time transaction scoring helps catch fraudulent claims before automated payouts occur.

    Side-by-Side: Old vs. New Rental Car Insurance Models

    The table below contrasts legacy rental car insurance with digital on-demand protection:

    Aspect Legacy Rental Desk Digital On-Demand (e.g., CarInsuRent)
    Purchase process At the counter, under time pressure Via app or web, in under 90 seconds
    Cost per day $30–60 $8–12
    Coverage exclusions Tyres, windscreens, undercarriage, keys, loss-of-use Often includes these items
    Claims process Paperwork, lengthy Digital submission, 24/7, fast reimbursement
    Flexibility One-size-fits-all Customizable by trip, vehicle, and driver
    Transparency Opaque, hidden fees Clear terms and pricing

    This digital shift eliminates rental desk friction and represents a structural overhaul of legacy insurance workflows. Automated cloud architectures and instant risk scoring enable insurtech firms to scale operations efficiently.

    Inside the Insurtech Playbook: Data, Apps, and On-Demand Car Rental Insurance

    On-demand car insurance is web- or app-based cover activated for a specific rental car, date range, and driver profile—often in under 90 seconds. The technology stack is simple in concept but powerful in execution:

    • Digital KYC verifies a driver’s license and age in seconds.
    • Real-time pricing models adjust by destination, duration, car category, and claim history.
    • Instant policy issuance delivers documentation to the customer’s phone and email—no paper, no line.
    • Claims can be submitted in under a minute via mobile apps, 24/7. Digital-first workflows can reduce waiting times from weeks to hours.

    CarInsuRent, for example, reviews claims within five business days of complete documentation, with reimbursement on a set schedule. Its coverage extends to windscreens, tyres, undercarriage, roof damage, keys, and towing. Comprehensive protection can be purchased for less than $10 per day, making the economics hard to ignore.

    Consumer Economics: Why Digital Excess Cover Beats the Counter Upsell

    Consider a 10-day rental in Florida. Legacy CDW at $30 per day totals $300—potentially double the rental rate. A standalone digital excess policy might run $8–12 per day, or $80–120 for the entire trip. Consumers save significantly by opting for insurtech alternatives.

    The cost advantage stems from global risk pooling, lower distribution costs (no counter staff or printed paperwork), and flexible product design. Annual policies cover multiple trips throughout the year, while single-trip policies are designed for one-time rentals with lower upfront costs. Insurtech solutions often act as primary coverage rather than secondary to personal auto policies, a meaningful advantage for those renting outside their home country. Renters must still follow rental agreement terms—no driving under the influence, no restricted road use—or reimbursement may be denied.

    What’s Next: Autonomous Mobility, Embedded Cover, and the Future of Travel Risk

    Autonomous vehicles, car-sharing platforms, and subscription services are reshaping what a rental car even means. Insurance coverage is shifting from days of hire to minutes of mobility—embedded insurance can automate activation based on vehicle usage and rental duration, letting travelers access coverage directly at checkout.

    Telematics data enables real-time risk assessment and usage-based pricing. Sensor-triggered claims, where a vehicle detects an accident and initiates a claim automatically, are on the horizon. Platforms like CarInsuRent can evolve into infrastructure layers, providing white-label or embedded car hire excess insurance for online travel agencies and mobility services worldwide.

    As autonomous vehicles become mainstream, car protection will shift from human drivers to vehicle hardware. AI-powered automotive systems will allow shared rental fleets to dynamically adjust coverage levels based on real-time telematics and predictive maintenance data.

    The bottom line: insurtech is turning rental car protection from an opaque afterthought into a transparent, real-time feature of digital mobility. The information is clearer, the ways to insure are simpler, and the advantage sits firmly with the consumer. For anyone still overpaying at the counter, the case for switching has never been stronger.

  • 10 AI-Powered Insurtech Companies Reshaping Insurance in 2026: A Deep Dive

    10 AI-Powered Insurtech Companies Reshaping Insurance in 2026: A Deep Dive

    Overview

    Ten companies made this list on verified deployments, named carrier partners, and reported metrics, not marketing claims. Coverage spans claims computer vision, repair workflows, fraud detection at two different stages, underwriting, actuarial pricing, cyber risk, and full-lifecycle AI insurance. Every figure below traces to a company report, carrier statement, or 2026 industry filing.

    A cyber insurer that stops seven in ten attacks before they land. A claims platform that settles a policy in two seconds flat. These are production numbers from carriers running AI as the core engine of underwriting, claims, and fraud detection, not a support feature bolted onto old workflows. The ten companies below made this list on verified deployments, named carriers, and outcomes anyone can check. A few well-known names got left out, since nothing tied their claims to a specific carrier result or a sourced number.

    What Makes These Insurtechs Leaders in 2026

    Three things separate a genuine leader from a company that simply mentions AI in its pitch deck. AI has to run a core operation, not sit beside it as a support tool. A named carrier, broker, or regulator has to confirm the result in public. And the deployment has to run at scale, across thousands of policies or claims, not a small cohort of early testers. Model sophistication barely matters here. What matters is how much of a workflow AI now finishes without a person stepping in.

    Claims and Damage Assessment: Tractable

    Millions of vehicle and property photos, collected since 2014, taught Tractable’s computer vision system to read collision damage the way a seasoned appraiser would, only faster. The platform reviews car damage with roughly 95% accuracy and turns a photo into a repair estimate in seconds, work that once took 30 minutes. GEICO and 25 of the world’s top 100 insurers now run claims through it, an adoption that pushed Tractable past a $1 billion valuation.

    Claims and Repair Workflow: CCC Intelligent Solutions

    Where Tractable reads the damage, CCC manages what happens next: repair shop, parts, and paperwork between insurer and body shop. Its Mobile Jumpstart tool already initiates 98% of repair estimates for one of the largest multi-store repair operators in the country. This quarter, a top-five insurer became CCC’s biggest customer yet for its AI-based subrogation tool, which automates the reimbursement claims carriers file against each other.

    Fraud Detection After the Claim: Shift Technology

    Claims fraud rarely announces itself, which is the problem Shift Technology’s Paris-built platform was designed to catch. AXA extended its partnership with Shift for five more years to widen fraud detection and underwriting checks across its global business, and Covéa signed on in early 2026 for a fraud framework spanning the entire policy lifecycle. Shift runs its models on Azure OpenAI Service, so carriers get newer AI without losing the compliance layer around it.

    Fraud Screening at the Point of Application: FRISS

    Shift catches fraud after a claim gets filed. FRISS catches it earlier, scoring an application for risk before a policy is even issued. Canadian insurer SGI brought the platform on in January 2026 to flag suspicious requests while speeding up legitimate ones, and a partnership with ForMotiv now folds in behavioral data captured during the application itself.

    Underwriting Built Around Continuous Risk: Cytora

    Commercial underwriting used to work off a single snapshot: an application filled out once, reviewed once, and revisited a year later. Cytora tore that model up with a platform that keeps absorbing broker emails, documents, and calls as new risk data shows up. Zurich Insurance is rolling it out across more than 20 markets over 16 months, and manual triage time there has already dropped from 75 minutes to 15 per submission. Markel and Travelers have adopted it too.

    Underwriting for Workers Comp and Group Health: Gradient AI

    Most insurtechs chase auto or property. Gradient AI went after a line most competitors ignore: workers’ compensation and group health risk scoring. Managing general underwriter BTIS adopted the platform for sharper workers’ comp pricing. One regional carrier running Gradient’s model cut its average quote turnaround from three days to under four hours by pre-scoring every submission and sending only the borderline cases to a human.

    Pricing and Actuarial Modeling: Akur8

    Pricing has always been the hardest place to trust a black box, since regulators expect an actuary to explain exactly why a rate moved. Akur8 built its platform around that constraint, offering machine learning transparent enough to survive review. More than 300 insurers across 40 countries now use it, including AXA, Generali, and Tokio Marine, and over 3,000 actuaries build pricing and reserving models in the system daily.

    Cyber Insurance’s AI-Native Leaders: Coalition and At-Bay

    Cyber risk changes by the hour, which is why Coalition built its ‘Active Insurance’ model around continuous scanning of a policyholder’s exposed systems instead of a one-time application. The company covers roughly 110,000 active policyholders and says they see about 70% fewer claims than the broader cyber market. At-Bay takes a similar approach to early warning. Its 2026 InsurSec Report, built from more than 100,000 policy years, recorded an all-time high average claim severity of $221,000, a figure it now uses to sharpen pricing before renewal.

    The Fully AI-Native Insurer: Lemonade

    No company on this list runs AI through more of the policy lifecycle than Lemonade. Its chatbots take 96% of first notices of loss without a person involved, and 55% of all claims settle from start to finish in seconds. The underwriting side backs that up: Lemonade’s gross loss ratio fell to 62% in the first quarter of 2026, down from 83% two years earlier, an improvement solid enough that the company now keeps more risk on its own books instead of handing it to reinsurers.

    Comparison Table

    Company Focus Area Key Metric Notable Partner
    Tractable Claims & Damage Assessment 95% accuracy, seconds to estimate GEICO
    CCC Intelligent Solutions Claims & Repair Workflow 98% estimates initiated via AI Top-five insurer
    Shift Technology Fraud Detection (post-claim) Extended partnership with AXA AXA, Covéa
    FRISS Fraud Screening (pre-issue) Real-time risk scoring SGI
    Cytora Continuous Underwriting Manual triage: 75 min to 15 min Zurich Insurance
    Gradient AI Workers Comp & Group Health Quote turnaround: 3 days to <4 hours BTIS
    Akur8 Pricing & Actuarial Modeling 300+ insurers, 40 countries AXA, Generali
    Coalition Cyber Insurance 70% fewer claims 110,000 policyholders
    At-Bay Cyber Insurance $221,000 avg claim severity 100,000+ policy years
    Lemonade Full-Lifecycle AI 55% claims settled in seconds Gross loss ratio 62%

    Final Thoughts

    Strip away the branding, and a pattern sits underneath all ten companies. Each one picked a single narrow job — reading a damaged photo, scoring a fraud risk, filing a rate change — and letting AI carry that job from start to finish instead of just assisting the person doing it. Regulators are starting to ask carriers to explain an AI decision, not just report it, and that shift will reward platforms built for scrutiny over ones chasing the broadest AI story. Watch which companies can show their work.

    FAQs

    1. What are AI-powered insurtech companies?

    AI-powered insurtech companies use artificial intelligence to improve insurance operations such as underwriting, claims processing, fraud detection, customer service, and risk assessment. Their technologies help insurers make faster, more accurate decisions while enhancing customer experience.

    2. Which are the leading AI-powered insurtech companies in 2026?

    Some of the leading AI-powered insurtech companies in 2026 include Lemonade, Coalition, At-Bay, Cytora, Akur8, Gradient AI, Tractable, Shift Technology, and FRISS, each specializing in different AI-driven insurance solutions.

    3. How is AI transforming the insurance industry in 2026?

    AI is enabling insurers to automate claims, improve underwriting accuracy, detect fraud in real time, personalize policy pricing, and streamline customer interactions. These advancements reduce costs while improving operational efficiency and customer satisfaction.

    4. What makes an AI-powered insurtech company a market leader?

    Leading AI-powered insurtech companies combine advanced AI capabilities with insurance expertise, strong partnerships, scalable platforms, and proven business impact. Their solutions deliver measurable improvements in risk assessment, claims management, and policy administration.

    5. What are the biggest AI trends shaping insurtech in 2026?

    Key trends include agentic AI for workflow automation, AI-assisted underwriting, computer vision for damage assessment, real-time fraud detection, embedded insurance, and personalized pricing powered by predictive analytics.

  • India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

    India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

    India’s fintech revolution has transformed digital finance through UPI, AI, and mobile-first innovation. From payments and investing to insurance and lending, the country’s top 10 fintech companies are driving financial inclusion, serving millions of users, and reshaping the future of banking.

    Overview

    India processes over 13 billion UPI transactions monthly, with the fintech market expected to exceed $150 billion by 2025, highlighting its rapid digital finance growth. The top 10 fintech firms lead payments, investing, insurance, and lending, serving millions of users while reshaping India’s financial ecosystem. AI, UPI, Aadhaar, and the Account Aggregator framework power these platforms, enabling faster services, smarter lending, and greater financial inclusion across India.

    The Leaders Redefining India’s Financial Landscape

    PhonePe

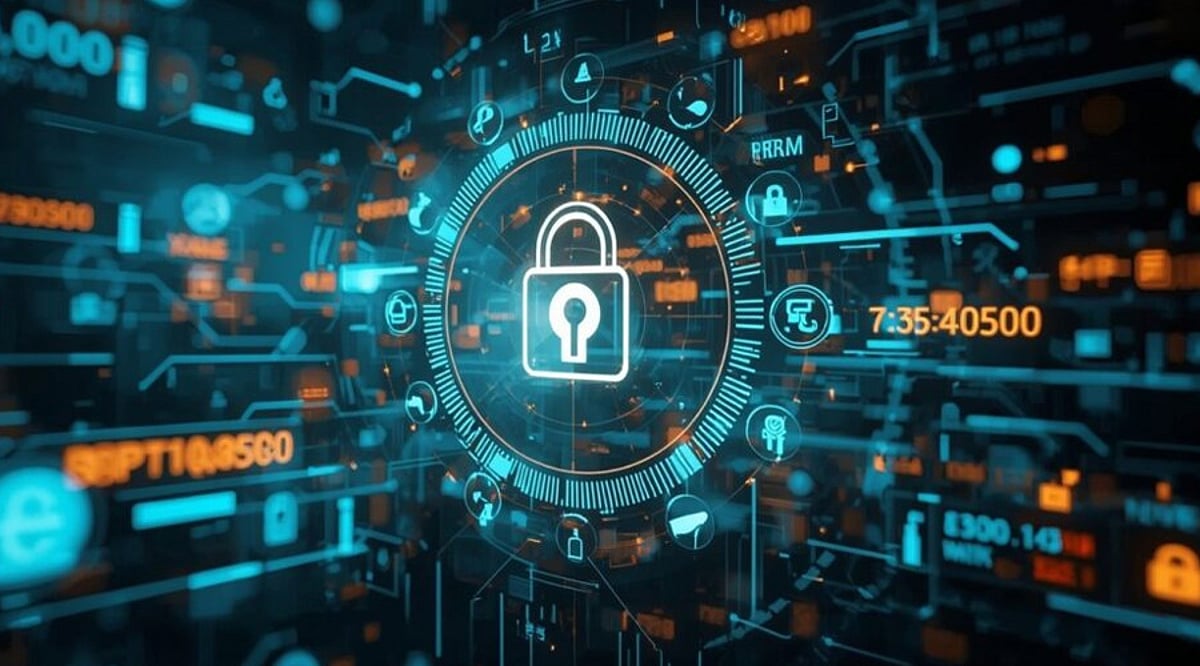
    PhonePe stands as India’s largest digital payments platform. Founded in 2015 by Sameer Nigam, Rahul Chari, and Burzin Engineer, it commands the UPI ecosystem with over 600 million registered users. The company’s revenue crossed ₹5,000 crore in FY24. Its platform spans payments, insurance, digital gold, and mutual funds. An IPO targeting a valuation between $9 billion and $10.5 billion remains on the horizon.

    Paytm

    Vijay Shekhar Sharma founded Paytm in 2000, making it one of India’s oldest fintech institutions. It began as a mobile recharge tool and expanded into wallets, merchant payments, lending, and wealth management. Annual revenues hover above ₹7,000 crore. Despite regulatory headwinds in recent years, Paytm holds a deep merchant network that keeps it embedded in India’s payment infrastructure.

    Razorpay

    Harshil Mathur and Shashank Kumar launched Razorpay in 2014 to solve a clear gap: businesses needed a reliable, developer-friendly payment gateway. The company now processes over $150 billion in annual payment volume and carries a valuation of approximately $7.5 billion. Its product suite covers payment gateways, business banking, payroll automation, and lending products used by thousands of Indian startups and enterprises.

    CRED

    Kunal Shah founded CRED in 2018 around a single insight: financially responsible people deserved better rewards. The platform targets high-credit-score users, offering reward points for credit card bill payments and expanding into personal loans, rent payments, and vehicle services. CRED’s valuation stands at around $6.4 billion, with estimated revenues crossing ₹2,000 crore in FY24.

    Zerodha

    Nithin Kamath and Nikhil Kamath built Zerodha in 2010 to lower the cost of investing. Discount brokerage and a clean trading interface on the Kite platform democratized equity markets for millions of retail investors. Revenue crossed ₹6,000 crore, and the company’s valuation sits between $3 billion and $4 billion. Zerodha remains profitable without external funding, which sets it apart in a sector that often burns capital for growth.

    Groww

    Lalit Keshre, Harsh Jain, Neeraj Singh, and Ishan Bansal founded Groww in 2016 to make investing simple for first-time users. The platform covers mutual funds, stocks, ETFs, IPOs, and fixed deposits under one roof. Its clean design and financial literacy focus helped it attract millions of young investors. Groww became a unicorn and continues expanding its wealth-tech offerings across India.

    Pine Labs

    Pine Labs traces its roots to 1998, making it one of the sector’s most seasoned players. Founded by Rajul Garg, the company built a merchant payment ecosystem spanning over one million touchpoints. Its POS machines and digital finance products serve retail chains and small merchants alike. Valuations range between $5 billion and $6 billion. Pine Labs bridges the offline and online commerce divide at meaningful scale.

    PB Fintech

    Yashish Dahiya founded PB Fintech in 2008, and it operates two major platforms: Policybazaar and Paisabazaar. Policybazaar became India’s largest online insurance marketplace, while Paisabazaar helps consumers compare loans and credit products. The company reported revenue growth of 33% year-on-year in recent results. Its market capitalization ranges between $4 billion and $5 billion.

    BharatPe

    Ashneer Grover and Shashvat Nakrani launched BharatPe in 2018 to serve a neglected segment: small merchants. The company introduced zero-fee UPI QR codes for shopkeepers and followed up with merchant loans and POS solutions. Its revenue surpassed ₹1,000 crore, and its merchant network now covers millions of micro and small retailers. BharatPe remains central to financial access for India’s informal business sector.

    ACKO

    Varun Dua founded ACKO in 2016 to reinvent insurance distribution. Traditional agents and lengthy paperwork gave way to a mobile-first platform where users buy, renew, and claim policies entirely online. ACKO offers motor, health, and travel insurance with faster claim settlements. Its digital-first model has attracted a growing customer base, and the company stands among India’s most prominent insurtech names.

    What These Leaders Share

    Several common threads run through all ten companies on this list: each built its product around mobile-first access, reaching users traditional banks could not. All ten leverage UPI, Aadhaar, or the Account Aggregator framework as foundational infrastructure. AI now powers credit scoring, fraud detection, and customer support across most platforms. Financial inclusion remains a stated goal, whether the customer is a salaried professional or a street-side vendor.

    Final Words

    India’s top fintech leaders did not simply build successful businesses. They rewired how a nation of 1.4 billion people manages money. Each company on this list solved a specific friction point, whether that was payment acceptance for merchants, affordable brokerage for retail investors, or instant insurance for urban professionals. The result is a financial ecosystem that is faster, cheaper, and more accessible than it was even five years ago. The next phase will demand more: regulatory clarity, sustainable unit economics, and deeper penetration into rural markets. The foundations, however, are already strong. India’s fintech sector enters the second half of this decade not as a promising experiment but as a proven engine of economic transformation. The names above have earned their place at the forefront. Now comes the harder task of staying there.

  • Varun Dua: The ACKO Founder Revolutionizing Digital Insurance in India

    Varun Dua: The ACKO Founder Revolutionizing Digital Insurance in India

    Varun Dua is an Indian entrepreneur and one of the pioneers of India’s insurtech sector. He founded ACKO in 2016 to make insurance simple, digital-first, and customer-centric by reducing paperwork and removing intermediaries. He is currently serving as the company’s CEO.

    Early Life and Education

    Born on 25 February 1981, Varun Dua grew up alongside India’s digital and commercial transformation, an environment that influenced his approach to business and technology. He holds a Bachelor’s Degree from the University of Mumbai and has established a firm academic foundation before making the transition to corporate and start-up sectors. He pursued postgraduate education in Marketing & Communication from MICA to gain in-depth knowledge of markets and customers. His educational and professional background helped pave the way for his entry into the world of insurtech. With his experience in the fundamentals of business along with the principles of communication, Dua embraced the concept of ‘Customer First’ in everything. Eventually, this became his hallmark as an entrepreneur.

    Career Journey: Building Insurance the Digital Way

    Varun Dua spent the early part of his career at the intersection of marketing and financial services, working with names such as Leo Burnett, TATA AIG Life Insurance, and Franklin Templeton. This experience taught him how brands are built and financial products are sold, while exposing frequent pain points in the insurance experience: complex policies, lengthy processes, and heavy reliance on intermediaries. In 2011, he co-founded Coverfox to make it simpler for consumers to compare and buy insurance online. The platform demonstrated the power of digital distribution, but it also revealed its limits: enabling sales was not enough. Dua concluded that meaningful, customer-centric transformation would happen only when insurers owned the full digital journey. This conviction later shaped his strategy for building more direct and user-friendly insurance models.

    ACKO: From Startup to Insurance Giant

    Varun Dua launched ACKO in 2016 as a digital-native insurance company. After receiving its regulatory licence from the Insurance Regulatory and Development Authority of India (IRDAI) in 2017, ACKO expanded into motor insurance, health insurance, travel insurance, term life insurance, mobile insurance, and digital automotive services through ACKO Drive. The company grew into one of India’s leading insurtech startups and entered the unicorn club in 2021 after a major funding round. The latest reports suggest that ACKO is preparing for an IPO with a target valuation of around $2.5 billion.

    Varun Dua as a Voice for Startups

    Business and Customers: He has a profound passion for the strategic aspect of business and consumer behavior. He keeps studying trends and new business models. Role as a Founder’s Advisor: He acts as an advisor and mentor to founders via Shark Tank India, sharing his expertise and experience with startups. Thought Leadership and Culture: He is a thought leader and often writes about leadership, corporate culture, and consumer behavior. Insurances and Technology: He supports innovation and technology and promotes the use of artificial intelligence and other technologies to optimize the insurance process.

    Career Highlights

    Varun Dua’s biggest business milestones include: started ACKO Insurance in 2016 to simplify insurance, making it faster and fully digital; co-founded CoverFox to help more Indians compare and purchase insurance online; led ACKO from a startup into becoming a ‘unicorn’ worth over a billion dollars; expanded ACKO’s business into health, life, travel, and many other types of insurance; partnered with brands such as Ola, Zomato, OYO, Urban Company for embedded insurance services; and serves as an investor in Season 3 of Shark Tank India.

    The Final Word: Varun Dua’s Vision Endures

    Varun Dua’s journey reflects how innovation and persistence can transform even the most traditional industries. From co-founding Coverfox to building ACKO into one of India’s leading digital insurers, he has consistently challenged conventional insurance models. His focus on technology, customer experience, and accessibility has earned him recognition as a key figure in India’s insurtech ecosystem. Dua remains an inspiration for aspiring entrepreneurs across the country.