Tag: money management

  • PennyGuard: How Its Features Support Everyday Money Decisions

    PennyGuard: How Its Features Support Everyday Money Decisions

    PennyGuard is a personal finance tool designed to bring the details of your everyday spending into one view. Rather than focusing only on saving, it helps you understand what is happening with each charge, identify recurring expenses, and uncover benefits linked to the cards you already use.

    What PennyGuard Does

    PennyGuard connects to your financial data through a few different paths. It works with bank connections through Plaid, offers a card connection option, and supports email connections from Gmail, Outlook, or Yahoo. The level of bank support depends on Plaid coverage.

    Once connected, the platform uses that information to identify options tied to individual transactions. The outputs fall into three main categories:

    • Information: explaining what a charge is, reminding you of a renewal, or showing a card perk.
    • Requests: actions you confirm, such as a cancellation or refund request.
    • Fulfilled outcomes: completed results, such as a confirmed cancellation or a refund that has landed in your account.

    Keeping these categories separate helps you know exactly what a feature is doing and what still needs to happen.

    Card Benefits for Purchases You Plan to Keep

    Not every transaction needs to be reduced or eliminated. Some charges reflect purchases you are happy with, and your main interest is whether your card offers a benefit for them.

    PennyGuard’s planned transaction-focused main view is meant to surface cashback or perks associated with your card, along with possible ways to pay less. The goal is to help you notice a benefit you might otherwise miss.

    There is an important difference between seeing a benefit and receiving it. Cashback is paid by the bank or card network under its own terms, so eligibility and fulfillment matter after discovery.

    When You Need More Context About a Charge

    A charge can look unfamiliar without being something you want to stop. In those cases, the text AI assistant is designed to answer questions using the same connected information that powers transaction analysis.

    You could ask what a charge is, which subscriptions are worth reviewing, or what perk may apply to a specific transaction. The explanation comes first; deciding to keep a service, cancel it, or request a refund comes later.

    PennyGuard helps surface opportunities and prepares actions, but you stay in control before any request is sent.

    Subscription Review and Cancellation Support

    Subscription detection uses bank and email data to spot recurring payments. The tool also looks for regular bills, trial periods, price increases, and duplicate charges. Those findings are a starting point for reviewing what you actually use.

    For example, you might go through a list of subscriptions after a change in your routine. Some services may still be essential, others may be occasional, and a few may no longer make sense. PennyGuard helps organize that review without assuming every subscription should be canceled.

    When you decide to cancel a service, PennyGuard can initiate cancellation requests through an AI agent, email, or a partner. Confirmation is required before anything is sent. The time to completion depends on the service, and you should treat a cancellation request as separate from a confirmed cancellation.

    Refund Requests vs. Bill Negotiation

    Merchant refunds and bill negotiation both involve another organization’s response, but they address different situations. A refund request is about money already charged. Negotiation is about lowering a bill.

    If you want a merchant to review a charge, PennyGuard can help submit a refund request after your confirmation. The useful output at that stage is initiation. Approval and the return of funds are separate outcomes.

    If you want to keep a service but pay less, the path is negotiation through a partner. The intended result is a changed cost rather than ending the service.

    Because timing depends on the merchant or provider, it helps to distinguish between the request you sent, the decision that came back, and the actual money impact.

    Notifications and Safe to Spend

    PennyGuard includes notifications for renewals, trial endings, price changes, and unfamiliar charges. Email and in-app notifications are planned delivery methods. An alert may simply prompt you to make a conscious decision to keep a service unchanged.

    The Safe to Spend feature answers a common question: how much may be left before your next deposit? It is an estimate, not a guarantee, so you should use it alongside commitments and upcoming expenses when weighing a purchase.

    PennyGuard does not hold money, transfer funds, pay bills, or open financial products. Its role is to keep you informed and help you decide what deserves attention.

    How to Use PennyGuard in Practice

    Start with the question you actually have:

    • If the purchase is staying, look at card benefits.
    • If the charge is unclear, seek context.
    • If a recurring service is no longer useful, consider a cancellation request.
    • If the issue is a past charge, think about refund assistance.
    • If the issue is a high ongoing bill, explore negotiation.

    Then identify what result you are looking at: information displayed, an action you confirmed, or a completed outcome. That distinction is the thread that connects PennyGuard’s planned features without making them interchangeable.

    PennyGuard is scheduled to launch on October 15, 2026. For current product information, consult the official PennyGuard site.
  • Top 10 Personal Finance Books to Master Money in 2026

    Top 10 Personal Finance Books to Master Money in 2026

    Managing money well depends as much on behavior as on financial knowledge. The right books can help build better saving, investing, and spending habits over time. Timeless principles remain valuable even as markets, technology, and personal finance continue to evolve.

    A budgeting app can track spending in seconds. It cannot explain why a person overspends every payday despite knowing better. That gap between knowing and doing is where books still earn their place, and it is wider in 2026 than it was five years ago, with gig income, AI-driven job cuts, and market swings reshaping how people relate to money.

    Here are the ten worth reading, grouped by financial stage rather than ranked by popularity.

    Strongest Starting Trio

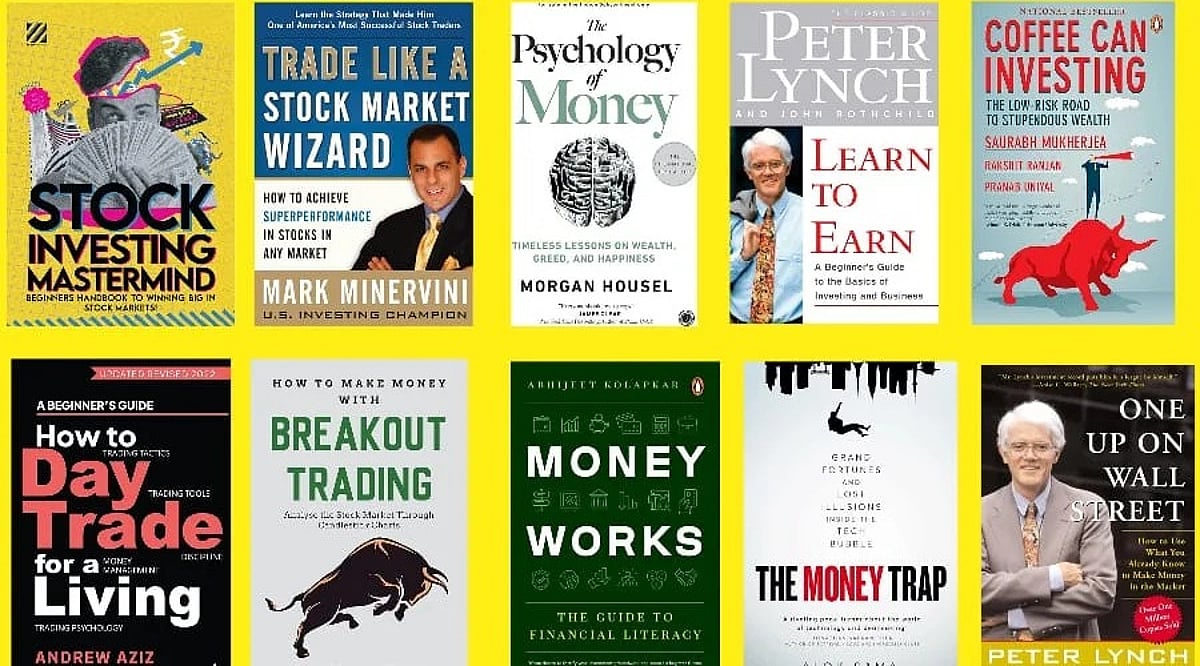
    Most readers, regardless of stage, gain the most from three books together: The Psychology of Money, I Will Teach You to Be Rich, and The Simple Path to Wealth. One reshapes how money is understood. One provides a working routine for daily decisions. One builds a durable investing foundation. Together they cover the three most common failure points: poor instincts, no system, and fear of investing.

    For Money Mindset and Behavior

    The Psychology of Money, by Morgan Housel, explains why capable people still make poor financial decisions under stress and social pressure. Rich Dad Poor Dad, by Robert Kiyosaki, reframes how readers categorize assets and liabilities. That shift proves useful even though several of Kiyosaki’s specific claims have drawn criticism from financial professionals over the years. Housel holds up better on rereading and works well as a single starting point for anyone who reads only one book from this list.

    Financial anxiety has become routine for many readers in 2026. Layoffs tied to AI adoption and unpredictable gig income have made that anxiety a daily condition, and no budgeting app addresses it directly. Both books tackle that psychological layer instead of the numbers alone.

    For Budgeting, Debt, and Daily Money

    The Total Money Makeover, by Dave Ramsey, and I Will Teach You to Be Rich, by Ramit Sethi, solve the same problem through opposite personalities. Ramsey favors strict rules: cut up the cards, snowball the debt, and live on a fixed cash plan. It works well for readers who need firm boundaries. Sethi favors automation: build routines that run quietly in the background so willpower matters less. Neither method is wrong. They suit different temperaments.

    Get Good with Money, by Tiffany Aliche, serves a third kind of reader—someone who feels structurally lost rather than simply undisciplined, with no baseline financial education to build from. It starts several steps earlier than the other two, covering credit basics and account structure before moving into strategy. Rigid budgets tend to break under variable income, and gig work keeps growing. Sethi’s automation-first model tends to hold up better for readers without a fixed monthly paycheck.

    For Investing and Wealth Building

    The Simple Path to Wealth, by JL Collins, and The Intelligent Investor, by Benjamin Graham, are both essential but not interchangeable. Collins offers a direct, low-friction case for index investing that a reader could act on within a week. Graham offers a philosophy of value and risk that takes longer to absorb but shapes every future investment decision. Collins builds action. Graham builds judgment.

    Friends that Invest, by Simran Kaur, works as the right entry point for readers who find both intimidating. It skips theory and walks through mechanics instead: opening a brokerage account, choosing a first fund, and understanding fees. Together, Collins and Graham argue for disciplined, low-cost investing over chasing trends, a case that has only grown stronger as AI-driven volatility and a flood of new ETF products make picking individual winners harder.

    For Retirement, FIRE, and Life Design

    Die with Zero, by Bill Perkins, and Your Money or Your Life, by Vicki Robin, share a premise: most people over-save and under-live. They land in different places. Perkins argues for deliberate spending before health or energy declines, treating memories and experiences as assets with their own expiration date. Robin pushes further, asking readers to treat every purchase as hours of life spent rather than dollars traded.

    The FIRE conversation has moved past the question of early retirement itself. Higher borrowing costs and pricier healthcare have made the math harder than it looked a decade ago, shifting the real question toward what retirement is actually for. Perkins and Robin, read together, address both the numbers and the purpose behind them.

    Suggested Reading Order

    Start with The Psychology of Money to reset how money gets evaluated. Move to I Will Teach You to Be Rich for a working routine. Read The Simple Path to Wealth next to build investing confidence. From there, branch based on priority: Die with Zero for life design, or The Intelligent Investor for deeper investment judgment.

    Final Thought

    Reading ten books was never the goal. Applying one lesson from the right book, at the right stage, changes outcomes faster than collecting a shelf of titles that never get opened. That single act of follow-through will matter more in the next few years than it has in the last decade, as financial noise keeps multiplying and genuine signal gets harder to find.

  • CRED’s Next Move: What Lies Ahead for Kunal Shah’s Fintech Platform

    CRED’s Next Move: What Lies Ahead for Kunal Shah’s Fintech Platform

    CRED has emerged as one of India’s most prominent fintech platforms, and questions are mounting about its next phase of growth and innovation. Founded by Kunal Shah, the company initially gained traction by rewarding users for timely credit card payments while cultivating a premium financial community.

    Beyond bill payments, CRED has expanded into lending, payments, financial products, and money management solutions. After years of rapid expansion, the company’s future focus is expected to sharpen on stronger monetization, deeper customer engagement, and sustainable business growth.

    India’s fintech market is becoming increasingly competitive, with digital payment platforms and financial technology companies launching new products for consumers. CRED’s ability to attract high-value users remains a key advantage as it explores fresh opportunities in the evolving financial services sector.

    The company faces challenges including profitability expectations, intensifying competition, shifting regulations, and the need to maintain long-term customer trust. Future growth could depend on expanding financial services while delivering greater value beyond traditional payment experiences.

    CRED’s next chapter will be closely watched as the fintech industry moves toward deeper digital banking and personalized financial solutions.

  • FamApp Review: All-in-One UPI Payment, Prepaid Card, and Money Management App

    FamApp Review: All-in-One UPI Payment, Prepaid Card, and Money Management App

    FamApp is a distinctive fintech mobile application that combines UPI payment, prepaid card services, and money management into a single platform. It enables users to handle their finances quickly and easily through transactions, payments, rewards, and expense management. The app focuses on delivering fast, efficient, and user-friendly payment services alongside comprehensive financial tools. Key benefits include digital payments, cashback rewards, and streamlined money management.

    General Information

    • Founded in: 2019
    • Platform Support: Android, iOS
    • Download: Click Here

    Main Features of FamApp

    • Safe UPI Transactions: Send money, pay merchants, recharge SIMs, and pay utility bills directly through the app.
    • Prepaid Card Services: Set spending limits, track expenses, and maintain a full transaction history for better financial control.
    • Cashbacks and Rewards: Earn incentives, cashback, and exclusive discounts from partner merchants on everyday digital transactions.
    • QR Code & Instant Transfers: Support for QR code payments, bank account linking, and instant peer-to-peer money transfers.
    • Integrated Finance Hub: All-in-one app combining digital payments, prepaid cards, transaction analysis, and reward programs.

    Benefits of FamApp

    • Seamless Transactions: Unified UPI, prepaid card, and digital wallet features streamline all payments.
    • Savings & Rewards: Cashback, reward programs, and merchant discounts help users save money effortlessly.
    • Secure Payments: A robust security framework ensures hassle-free and protected transactions.
    • User-Friendly Interface: Intuitive design makes it easy to transfer money, monitor expenses, pay bills, and use prepaid cards.
    • All-in-One Financial Tool: Combines digital payments, expense tracking, and reward schemes in a single app.

    Challenges of FamApp

    • Limited Rewards: Cashback and promotions may be restricted to specific merchants and campaigns.
    • Verification Required: Access to certain financial services depends on successful identity verification and regulatory compliance.
    • Potential Delays: UPI and transaction processing may occasionally slow during peak periods due to banking partner network issues.
    • Regional Availability: Some services, prepaid card features, and promotional offers vary by location.
    • Financial Discipline: Although secure, users should maintain good financial practices and always verify transactions.

    Subscription Information

    FamApp by Trio is a free download. Basic UPI transactions and financial services are available at no cost, while premium services may be offered based on eligibility and availability.

    Support Options

    • Help Center & Learning Resources: FAQs, payment guides, UPI support articles, security resources, blog posts, product updates, documentation, and knowledge base.
    • Customer Support: Email support, customer care, payment and account support, in-app Help Center, technical assistance, and documentation.

    Conclusion

    FamApp is an integrated digital payment platform that brings together UPI transfers, prepaid cards, reward systems, and expense management. With its convenient interface, secure payment system, and comprehensive financial products, it is well-suited for daily digital payment needs. However, users should note that certain offers and services depend on eligibility and banking partnerships.

  • Best Smart Budgeting Apps for 2026: Features, Market Growth, and Expert Picks

    Best Smart Budgeting Apps for 2026: Features, Market Growth, and Expert Picks

    Smart budgeting apps have transformed how people manage income, expenses, savings, and subscriptions. Instead of juggling multiple bank accounts or keeping paper records, these tools consolidate everything into one screen, often with automatic bank syncing and detailed reports. Below, we explore seven popular apps, their standout features, and the latest market figures shaping personal finance.

    Key Takeaways

    • Wallet by BudgetBakers delivers detailed cash-flow tracking with automatic bank synchronization.
    • YNAB follows a zero-based budgeting approach that supports disciplined financial planning.
    • Rocket Money helps identify unwanted subscriptions and reduce unnecessary monthly expenses.

    Market Overview

    The global smart budgeting app market reached about US$1.21 billion in 2024 and is projected to grow to around US$6.6 billion by 2034, at a compound annual growth rate (CAGR) of 18.4%. Mobile apps hold 72.6% of the market, while expense tracking and financial planning account for nearly 49.8% of total usage. Individual consumers represent 68.4% of users, highlighting that personal money management drives this growth.

    Top Budgeting Apps in Detail

    Wallet by BudgetBakers – Complete Money Tracking

    Wallet by BudgetBakers is a strong choice for users who want a clear picture of their finances. It combines multiple tools in one app and creates detailed reports to show where money goes each month. Forbes recently ranked it among the best budgeting apps for cash-flow monitoring thanks to its practical features and reliable bank synchronization. The app connects with multiple bank accounts, automatically records transactions, supports shared wallets for household budgeting, and offers cash-flow forecasts to help users prepare for future expenses.

    YNAB (You Need a Budget) – Builds Disciplined Habits

    YNAB follows a zero-based budgeting method that assigns every dollar to a specific category before spending. This approach promotes planning over impulsive spending. Widely regarded as one of the most popular budgeting apps, YNAB helps users achieve long-term financial goals by cutting costs and improving savings systematically.

    Monarch Money – Household Finances Together

    Monarch Money focuses on complete financial management, combining budgets, investments, savings goals, and net worth into one dashboard. It is especially useful for couples and families, as shared financial planning keeps everyone updated. Investment tracking adds extra value for users who want both budgeting and wealth management in one platform.

    Rocket Money – Reduce Unnecessary Expenses

    Rocket Money targets forgotten subscriptions and unnecessary monthly payments. It identifies recurring charges before they become costly. Besides subscription management, it offers spending analysis, budget planning, bill negotiation, and credit score monitoring, helping users gain better financial control.

    Copilot Money – Smart Automation for Apple Users

    Copilot Money has gained traction among Apple users due to its intuitive interface and smart automation. It automatically categorizes expenses and provides insights into financial behaviors. Instant identification of recurring payments reduces manual work, and visual dashboards make finances easy to understand at a glance.

    Goodbudget – Digital Envelope Method

    Goodbudget brings the traditional envelope budgeting method into a digital format, creating virtual envelopes for groceries, transport, shopping, savings, and more. With over 3 million downloads, it supports shared budgets and cross-device synchronization, making it ideal for families. Goal-based saving envelopes encourage regular saving without complexity.

    PocketGuard – Safe Daily Spending

    PocketGuard answers a simple question: how much money is safe to spend today? It calculates available funds after bills, savings goals, and recurring expenses are allocated. The Safe-to-Spend feature helps users avoid unnecessary purchases, and automatic budgeting reduces manual effort while providing clear financial guidance.

    Smart Features Shaping Budgeting Apps

    Modern budgeting apps go beyond simple expense tracking. Artificial intelligence enables smarter categorization and personalized advice. Subscription tracking has become essential as more people pay for multiple online services. Other features include real-time bank synchronization, automatic savings goal management, investment monitoring, cash-flow forecasting, and collaborative household budgeting. These developments make contemporary apps increasingly powerful for financial planning.

    Frequently Asked Questions

    1. What is a smart budgeting app? A smart budgeting app helps track income, expenses, savings, and bills while providing financial insights through automation and reports.
    2. Which budgeting app is best for beginners? Wallet by BudgetBakers is a strong choice given its simple interface and detailed expense tracking.
    3. Which app works well for subscription management? Rocket Money specializes in identifying recurring subscriptions and helping reduce unnecessary monthly payments.
    4. What makes YNAB different from other budgeting apps? YNAB follows a zero-based budgeting method that assigns every dollar a specific purpose before spending begins.
    5. How fast is the smart budgeting app market growing? The market was valued at about US$1.21 billion in 2024 and is projected to reach around US$6.6 billion by 2034, growing at a CAGR of 18.4%.