Tag: mutual funds

  • 7 Key Assets for Building Long-Term Wealth

    7 Key Assets for Building Long-Term Wealth

    Building wealth is a long-term endeavor that requires a strategic approach to investing. By diversifying across different asset classes, you can spread risk and increase your potential for returns. Here are seven assets that can help you build wealth over time.

    1. Stocks

    Stocks offer long-term growth potential by giving investors exposure to company performance, market movements, and economic conditions. However, they come with varying levels of risk depending on the company and market trends.

    2. Bonds

    Bonds provide income through regular interest payments and can help diversify a portfolio. Their returns and risk depend on the issuer and prevailing market conditions, making them a more stable option compared to stocks.

    3. Gold

    Gold is a tangible asset that often moves differently from financial assets, offering a hedge against inflation and economic uncertainty. Its price can fluctuate based on global economic factors, but it remains a popular diversification tool.

    4. Real Estate

    Investing in physical property can generate rental income and appreciate in value over time. However, it requires significant capital and ongoing maintenance costs, making it less accessible for some investors.

    5. REITs (Real Estate Investment Trusts)

    REITs allow you to invest in real estate without directly buying properties. They offer accessibility and potential income through distributions, making real estate investment more liquid and manageable.

    6. Mutual Funds

    Mutual funds pool money from multiple investors to invest in a diversified portfolio of securities. They are professionally managed, making them a convenient way for individuals to achieve diversification without picking individual stocks or bonds.

    7. Yourself

    Investing in your own education, skills, and professional development can significantly improve your earning potential. This personal investment supports stronger long-term financial decision-making and career growth.

    Diversification and Risk Management

    Combining different asset classes spreads exposure across investments, reducing dependence on any single asset’s performance. Your asset choices should align with your personal goals, risk tolerance, and investment time horizon rather than following popular trends.

    By carefully selecting a mix of these assets, you can build a robust portfolio that works toward your financial future.

  • India’s Largest Small-Cap Funds: How Many Stocks Do They Hold?

    India’s Largest Small-Cap Funds: How Many Stocks Do They Hold?

    Introduction

    India’s small-cap mutual fund space features a diverse range of portfolio strategies. A recent analysis of the seven largest small-cap funds by assets under management (AUM) reveals significant variation in the number of individual stocks held. Below is a breakdown of each fund’s stock count and AUM.

    Fund-by-Fund Breakdown

    Bandhan Small Cap Fund

    Holds the highest stock count among the seven funds at 258 stocks, with an AUM of ₹34,176 crore. Its portfolio breadth slightly exceeds that of Nippon India Small Cap.

    Nippon India Small Cap Fund

    With 254 stocks and an AUM of ₹82,580 crore, this fund is the largest by AUM and holds the second-highest number of stocks, indicating a diversified approach.

    Axis Small Cap Fund

    Holds 128 stocks with an AUM of ₹31,448 crore. Its stock count is moderate compared to peers.

    Quant Small Cap Fund

    Manages 104 stocks and ₹35,557 crore in AUM, placing it in the middle of the range.

    HDFC Small Cap Fund

    Holds 84 stocks with an AUM of ₹41,891 crore, showing a more concentrated portfolio relative to its AUM.

    DSP Small Cap Fund

    Holds 82 stocks and manages ₹21,659 crore in AUM, similar in stock count to HDFC but with lower AUM.

    SBI Small Cap Fund

    Holds the fewest stocks at 68, with an AUM of ₹42,631 crore. This highlights that a lower stock count does not necessarily mean lower AUM.

    Key Takeaways

    The data shows that small-cap funds vary widely in their portfolio construction. Bandhan and Nippon India hold over 250 stocks each, while SBI and DSP hold fewer than 100. AUM also varies, with Nippon India leading at over ₹82,000 crore. Investors should consider both stock count and AUM when evaluating fund diversification.

  • New UPI MDR Framework: How SIPs, OTT, and Rent Payments Are Affected from October 15

    New UPI MDR Framework: How SIPs, OTT, and Rent Payments Are Affected from October 15

    The Reserve Bank of India’s new UPI Merchant Discount Rate (MDR) regime takes effect on October 15, 2026. While the updated rules introduce charges for certain merchant transactions, many recurring payments—like mutual fund SIPs and OTT subscriptions—remain untouched. Here’s a breakdown of what changes, what stays free, and how different payment types are classified.

    Key Takeaways

    • UPI AutoPay SIPs and OTT subscriptions are exempt from the prescribed MDR.
    • One-time mutual fund and capital-market UPI payments incur a 0.02% MDR, capped at ₹300.
    • Specified person-to-merchant (P2M) payments above ₹2,000 may attract a 0.4% MDR, with a ₹300 cap for transactions of ₹75,000 or more.

    Understanding the New MDR Structure

    The new framework applies a 0.4% MDR to specified P2M UPI payments exceeding ₹2,000. For transactions of ₹75,000 and above, the charge is capped at ₹300. Person-to-person (P2P) transfers remain completely free, regardless of the amount. Merchant payments up to ₹2,000 are also exempt. According to the government, approximately 96% of P2M transactions will remain outside the MDR net.

    UPI AutoPay Exemption: Relief for Recurring Payments

    NPCI has confirmed that UPI Mandates and AutoPay recurring transactions will not attract the prescribed MDR. This includes utility bills, OTT subscriptions, and recurring investments such as mutual fund SIPs. So, a ₹10,000 SIP set up via UPI AutoPay will not incur an MDR charge simply because it exceeds ₹2,000. Similarly, a ₹2,500 monthly OTT subscription—whether Netflix, Amazon Prime, or JioHotstar—remains unaffected.

    Mutual Fund SIPs: Two Different Rules

    The treatment of mutual fund SIPs depends on the payment route. Recurring SIPs using UPI AutoPay are outside the prescribed MDR. However, one-time UPI payments for mutual funds, securities, stockbrokers, or dealers fall under a separate capital-market category. This category carries a much lower MDR of 0.02%, capped at ₹300 per transaction. The reduced rate is intended to encourage retail participation in formal financial markets.

    This distinction is significant for brokers and investment platforms. Reuters has reported industry concerns about the impact of frequent UPI transactions on brokerage costs, and Zerodha CEO Nithin Kamath has publicly questioned whether brokers can absorb the long-term cost.

    Rent Payments: Structure Matters

    Rent payments do not automatically receive the same AutoPay exemption unless the transaction uses a UPI Mandate or AutoPay structure. A simple transfer between individuals remains a P2P payment, which is free regardless of amount. However, if rent is paid to a merchant or property service provider, it may fall under the P2M framework if the transaction meets relevant conditions. The official rules do not list rent as a special category, so the exact treatment depends on how the payment is structured and who the recipient is.

    Customers Won’t Pay MDR Directly

    The MDR is a merchant-side charge within the UPI ecosystem. The government has clearly stated that customers will not be charged a separate UPI transaction fee. Banks have been directed to prevent merchants from passing on the MDR to customers, and UPI app providers are prohibited from adding platform fees or hidden charges under this framework. A ₹20,000 eligible merchant payment, therefore, will not become a ₹20,080 debit from the customer’s account.

    Still, businesses may feel the pinch. Retailer groups have expressed opposition, warning that the added cost could squeeze already thin margins. Some industry associations have also questioned the timing, given the upcoming festive season.

    What Changes from October 15

    Starting October 15, 2026, the following rules apply:

    • Standard P2M transactions above ₹2,000: 0.4% MDR, capped at ₹300 for amounts of ₹75,000 or more.
    • Railways, telecom, insurance, fuel, and agricultural inputs above ₹2,000: flat ₹5 MDR.
    • Capital-market payments (one-time mutual fund, securities, etc.): 0.02% MDR, capped at ₹300.
    • UPI AutoPay recurring payments (SIPs, OTT, bills): exempt from prescribed MDR.
    • P2P transfers: always free.

    The immediate impact on most households appears limited. The bigger shift is internal—banks, payment service providers, apps, brokers, and merchants must now adapt to a new cost landscape after more than six years of zero-cost UPI merchant payments.

    Frequently Asked Questions

    1. Will mutual fund SIPs become costlier under the new UPI MDR rules?

    No, SIPs that use UPI AutoPay mandates remain outside the prescribed MDR.

    2. Will OTT subscriptions attract UPI MDR?

    No, recurring OTT payments through eligible UPI AutoPay mandates remain outside the prescribed MDR.

    3. Will rent payments become costlier?

    Treatment depends on the payment structure. P2P transfers remain free, while eligible P2M transactions can fall under the MDR framework.

    4. What MDR applies to one-time mutual fund payments?

    A 0.02% MDR applies to specified capital-market payments, with a maximum charge of ₹300 per transaction.

    5. When will the new UPI MDR framework start?

    The new framework takes effect on October 15, 2026.

  • SIP Investing Explained: How Systematic Investment Plans Work and How to Begin

    SIP Investing Explained: How Systematic Investment Plans Work and How to Begin

    Systematic Investment Plans (SIPs) have become a cornerstone of mutual fund investing in India, enabling ordinary savers to build wealth through small, regular contributions rather than a single large payment. This article explains how SIPs work, the types available, and the steps needed to start.

    What is a Systematic Investment Plan?

    A SIP is a method of investing a fixed sum in a mutual fund scheme at regular intervals, typically monthly. It functions like a recurring bank deposit, but the money goes into a market-linked fund instead of a fixed-rate account. The amount is automatically deducted from the investor’s bank account on a chosen date and converted into fund units. Many schemes allow entry with amounts as low as Rs. 500, making SIPs accessible to almost every income group.

    How SIP Works in Practice

    Each SIP installment buys units of the chosen mutual fund at that day’s Net Asset Value (NAV). When markets fall, the same installment buys more units; when markets rise, it buys fewer units. Over time, this pattern averages out the purchase cost and reduces the pressure of timing the market. Investors who stay invested through ups and downs typically achieve a smoother average cost than those who invest a lump sum at a single point.

    The process follows a simple cycle: select a fund and fix the installment amount, set up a bank mandate for automatic transfer on a chosen date, receive units at each installment based on that day’s NAV, and build returns gradually through market-linked growth and reinvestment.

    Why Investors Prefer SIPs

    SIPs suit both first-time and experienced investors for practical reasons: low entry amount keeps budgets manageable, automatic transfers build a savings habit, rupee-cost averaging smooths market volatility, and flexibility to pause, increase, or stop installments adapts to changing goals. Investors also benefit from professional fund management without needing deep market knowledge.

    Types of SIP Available

    Fund houses offer several SIP formats: regular, step-up, flexible, perpetual, and trigger SIPs. Each caters to different saving patterns and goals.

    Steps to Start Investing Through SIP

    1. Complete KYC using PAN and address proof.
    2. Define a financial goal (e.g., home purchase, education, retirement).
    3. Choose a fund category (equity, debt, or hybrid) based on goal and time horizon.
    4. Select the SIP amount and frequency that fits your monthly cash flow.
    5. Set up an auto-debit mandate linked to your bank account.
    6. Track investments periodically and adjust the amount as income grows.

    Online SIP calculators help estimate the projected corpus by entering the monthly amount, expected return, and tenure, aiding in setting realistic targets.

    Final Thoughts

    Mutual fund returns depend on market performance, with no guaranteed outcomes. Equity-oriented funds carry higher short-term volatility; debt funds tend to move within a narrower range. Always read the scheme document, check the expense ratio, and review the fund manager’s track record. Staying invested through market cycles, rather than exiting during downturns, generally benefits long-term SIP investors.

    A well-planned SIP journey rests on three habits: starting early, staying consistent, and reviewing the portfolio once or twice a year. Time in the market matters more than trying to pick the perfect entry point. For beginners, a SIP offers a structured, low-pressure path toward long-term financial goals like a home, education, or retirement.

  • 5 Essential Mutual Fund Books to Sharpen Your Investing Skills in India

    5 Essential Mutual Fund Books to Sharpen Your Investing Skills in India

    Building strong mutual fund investing skills begins with the right knowledge. The best books explain fund selection, portfolio construction, and long-term investing using practical frameworks. Following a structured reading roadmap helps Indian investors make informed decisions and build disciplined wealth creation habits.

    Most Indian investors lose money not from picking bad funds, but from investing without a clear framework or process. Five books, read in the right order, build four distinct skills: fund basics, fund evaluation, portfolio construction, and emotional discipline. Books are selected for practical value, Indian market relevance, and principles that hold across market cycles.

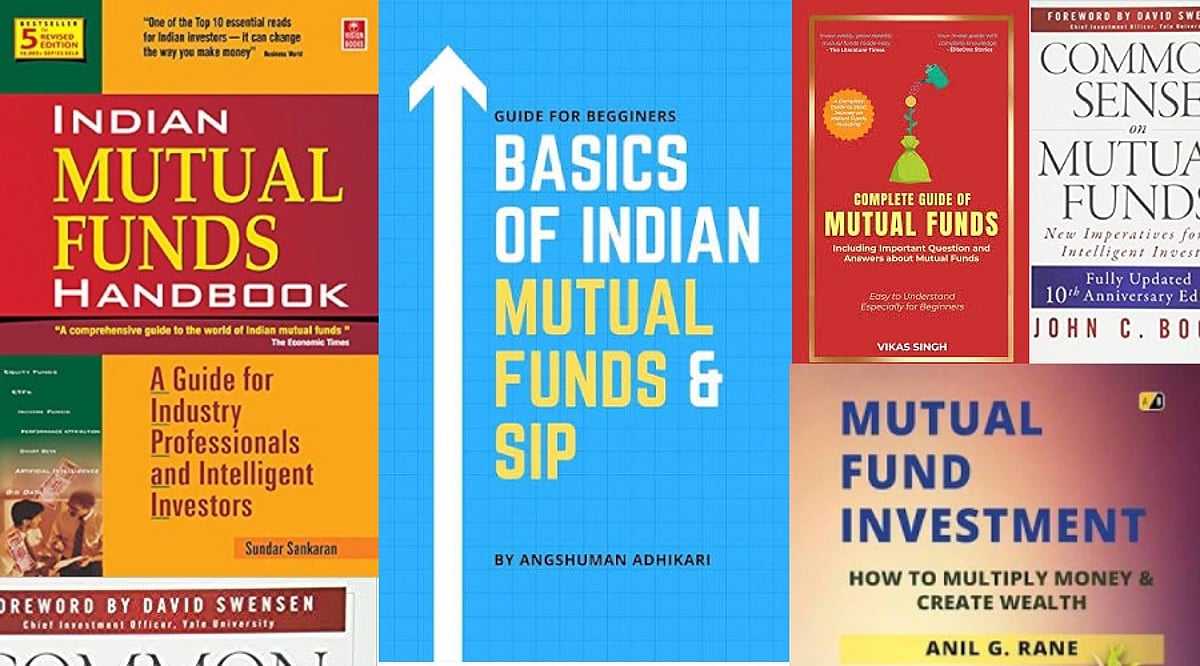
    Every market correction produces the same behavior. Investors scan social media, chase last year’s top-performing funds, and reshuffle portfolios on impulse. Months later, many realize the problem was never the fund. It was the absence of a process. One well-chosen book can close that gap faster than years of trial and error. Monika Halan’s Let’s Talk Mutual Funds has done exactly that for a wide range of Indian investors by teaching them how to think before they invest, not after.

    The books in this guide are not ranked by popularity. Each one is chosen for the specific investing skill it develops. Read them in order, and the effect is cumulative.

    The Four Skills That Actually Drive Investment Success

    Good mutual fund investing is not one skill. It is four. First, understand what funds are and how they work. Second, learn to evaluate them without relying on tips or rankings. Third, build a portfolio that fits your goals and risk tolerance. Fourth, stay rational when markets move against you. Most investors develop the first skill and skip the rest. That is where the damage happens.

    Let’s Talk Mutual Funds — Monika Halan

    Skill Built: Fund Basics

    Halan writes for real people, not finance professionals. She explains SIPs, NAV, fund categories, and risk using everyday Indian financial situations. The book is grounded in local regulations and household budgeting realities, which makes it immediately useful for first-time investors.

    Her central point is worth repeating: choose funds based on your goals, not on recent performance tables. Investors who miss this early tend to keep chasing returns for years. The book does not go deep into fund evaluation. That is intentional. It is designed to build a foundation, and it does that well.

    Indian Mutual Funds Handbook — Sundar Sankaran

    Skill Built: Fund Evaluation

    Once the basics are clear, the next step is learning to read a fund properly. Sankaran walks through scheme documents, factsheets, expense ratios, and fund manager assessment with more detail than most Indian investing books attempt.

    This is the reference that helps investors stop depending on third-party rankings and start forming their own views. It pairs naturally with Common Sense on Mutual Funds, which extends the conversation on costs.

    Common Sense on Mutual Funds — John C. Bogle

    Skill Built: Cost Awareness

    Bogle’s argument is direct. Reducing costs does more for long-term wealth than identifying the next top-performing fund. For Indian investors still in regular plans, this insight alone can translate into a material difference over a decade or more. Every percentage point saved in annual fees compounds quietly in the background. Most investors underestimate how much that adds up.

    The Four Pillars of Investing — William J. Bernstein

    Skill Built: Portfolio Construction

    Bernstein moves the conversation away from individual fund selection toward how a portfolio holds together as a whole. He covers diversification, rebalancing, and long-term planning in a way that is structured without being dense. This is the right book to read after fund evaluation is clear but before a long-term portfolio is locked in.

    The Intelligent Investor — Benjamin Graham

    Skill Built: Emotional Discipline

    Graham wrote this for stock investors, but the core lessons apply directly to anyone holding mutual funds through a volatile market. His framing of “Mr. Market” remains the clearest explanation of why reacting to short-term price moves is almost always a mistake. Chapters 8 and 20 carry the most practical value for mutual fund investors and are worth reading more than once.

    Read Them in this Sequence

    Start with Let’s Talk Mutual Funds to build a solid foundation. Move to the Indian Mutual Funds Handbook to learn fund evaluation. Follow with Common Sense on Mutual Funds to understand what fees actually cost over time. Then read The Four Pillars of Investing before constructing a diversified portfolio. Finish with The Intelligent Investor to develop the discipline that separates long-term investors from short-term reactors. The sequence matters. Each book builds on the one before it.

    Final Thoughts

    The investors who hold steady through ten or twenty years of market cycles are rarely the ones who picked the best fund at the right time. They are the ones who built a clear process early and trusted it when things got uncomfortable. These five books do not promise shortcuts. They build the kind of judgment that holds up across market conditions, economic shifts, and personal financial changes. That is what makes them worth reading.

  • CowryWise Review: Nigeria’s Automated Savings and Investment App for Smart Financial Planning

    CowryWise Review: Nigeria’s Automated Savings and Investment App for Smart Financial Planning

    Overview

    CowryWise is a Nigerian fintech mobile app that helps users automate savings and invest in regulated mutual funds. Licensed by the Nigerian SEC, the platform offers goal-oriented saving, investment opportunities in both Naira and Dollars, and portfolio management tools. It is designed for individuals, young professionals, students, salaried employees, freelancers, families, and long-term investors. The app is available on iOS, Android, and the web.

    Key Features

    • Automated Savings: Set up daily, weekly, or monthly savings plans to build wealth without manual deposits.
    • Mutual Fund Investments: Access professionally managed Naira and Dollar mutual funds tailored to your financial goals.
    • Goal-Based Savings: Choose from options like Emergency Savings, Money Duo, Circle Savings, or custom savings for rent, travel, education, or business.
    • Risk Assessment: Receive investment recommendations based on your financial objectives and risk tolerance.
    • Account Linking & Tracking: Automate bank account connections, recurring payments, portfolio tracking, interest calculations, and access to financial literacy resources.

    Benefits

    • Disciplined Savings: Automated schedules help you meet short- and long-term goals effortlessly.
    • Better Returns: Invest in well-regulated mutual funds that typically outperform traditional savings accounts.
    • High Security: Licensed custodians, SEC oversight, encryption, and anti-fraud systems protect your funds.
    • User-Friendly: An intuitive interface makes saving and investing easy for beginners.
    • Compound Growth: Consistent reinvestment helps build wealth over time.

    Challenges

    • Locked Savings: Funds in locked savings plans cannot be withdrawn before maturity, reducing flexibility in emergencies.
    • Emergency Savings Waiting Period: Withdrawals require a security waiting period, which may be inconvenient.
    • Minimum Contributions: Some plans require minimum deposits that may not suit small savers.
    • Market-Dependent Returns: Investment performance is not guaranteed.
    • Nigeria-Focused: Most services are limited to Nigerian users, excluding international customers.

    Pricing & Subscription

    CowryWise does not charge subscription fees for opening or managing accounts. Users can start saving with minimal deposits; investment products have varying minimums. Returns depend on market performance and the chosen mutual fund, not on subscription fees.

    Customer Support

    The platform offers a comprehensive Help Center with FAQs, security tips, and educational content. Support is available via in-app chat, email, and phone for account verification, savings plans, investments, and withdrawals.

    Conclusion

    CowryWise combines automated savings, regulated mutual fund investments, strong security, and ease of use. User testimonials, domain age, and popularity add to its credibility. While locked savings and market-dependent returns may not suit everyone, the app remains a solid choice for Nigerians seeking effective saving and investing tools.

  • Best Mutual Funds in India for 2026: High Returns with Lower Risk

    Best Mutual Funds in India for 2026: High Returns with Lower Risk

    As Indian investors look ahead to 2026, selecting the right mutual funds is crucial for balancing growth and stability. The following funds have been identified for their consistent performance, smart diversification, and risk management. Whether you are a conservative investor or seeking higher growth, these options cater to a range of financial goals.

    Parag Parikh Flexi Cap Fund

    This flexi-cap fund is known for its diversified investing approach, delivering strong long-term returns through disciplined stock selection across market caps.

    HDFC Balanced Advantage Fund

    By dynamically balancing equity and debt, this fund helps investors manage market volatility while targeting steady wealth creation over the long term.

    SBI Contra Fund

    Employing a value-oriented strategy, SBI Contra Fund invests in undervalued companies with strong recovery potential, aiming for long-term growth across sectors.

    UTI Nifty 50 Index Fund

    Ideal for passive investors, this fund tracks the Nifty 50 Index, offering low-cost exposure to India’s top companies with consistent long-term performance.

    ICICI Prudential Bluechip Fund

    Focused on established large-cap companies with stable earnings, this fund is suitable for those seeking relatively lower-risk equity investing.

    Nippon India Small Cap Fund

    Investing in promising small-cap companies, this fund offers higher growth opportunities, though it carries greater market volatility and risk.

    Kotak Equity Opportunities Fund

    Diversifying across large and mid-cap stocks, this fund aims for balanced growth with effective risk management through professional fund selection.

    Axis ELSS Tax Saver Fund

    Combining tax-saving benefits with long-term equity investments, this ELSS fund is attractive for investors seeking wealth creation and deductions under Section 80C.

    Choose Based on Your Goals

    Financial experts advise selecting mutual funds according to your personal financial goals, investment horizon, and risk tolerance, rather than relying solely on historical returns. Always review fund performance and consult a financial advisor before investing.

  • Why Market Volatility Creates Optimal SIP Investment Opportunities: An Expert Guide

    Why Market Volatility Creates Optimal SIP Investment Opportunities: An Expert Guide

    Many investors feel anxious when stock markets become volatile. Sharp market falls often create fear as portfolio values shrink temporarily. However, financial experts argue that market volatility can actually be the best time for Systematic Investment Plan (SIP) investments.

    SIP allows a fixed amount to be invested in mutual funds every month. This strategy works especially well during uncertain market periods because falling markets enable investors to buy more units at lower prices. Over the long term, this approach can generate better wealth than investing only when markets are strong.

    Market Falls Create Better Investment Opportunities

    When stock markets decline, share prices across many sectors become cheaper. Many investors wait for the perfect moment to invest, but predicting the exact market bottom is impossible. SIP eliminates this problem by investing a fixed monthly amount regardless of market conditions. When prices fall, the same monthly investment buys more mutual fund units. For example, a monthly SIP of Rs. 5,000 buys fewer units when markets are high, but during downturns, that same amount purchases more units, lowering the average buying cost over time. This is known as rupee cost averaging, a key advantage of SIP investing.

    Market Volatility Has Increased in 2026

    The Indian stock market has experienced significant volatility in recent months due to rising crude oil prices, inflationary pressures, global economic uncertainties, and geopolitical tensions in West Asia. According to recent data from the Association of Mutual Funds in India (AMFI), equity mutual fund inflows dropped nearly 40% in May 2026 to Rs. 22,908 crore, the lowest level in almost one year. This decline reflects increased caution among investors, but SIP investors have responded differently.

    SIP Investments Remain Strong Despite Market Pressure

    Despite the volatility, SIP contributions have remained robust. AMFI data shows SIP inflows reached Rs. 32,087 crore in March 2026, Rs. 31,115 crore in April 2026, and Rs. 30,954 crore in May 2026. This marks three consecutive months of SIP inflows above Rs. 30,000 crore, indicating a shift in investor behavior. More investors now understand that short-term market fear should not derail long-term wealth creation. Instead of panicking, disciplined investors continue their regular investments.

    Lower Prices Can Boost Future Returns

    Stock markets do not move in one direction forever. Every bull market eventually corrects, and every correction leads to a recovery. This cycle creates opportunities for SIP investors. When prices remain low, monthly investments accumulate more mutual fund units. When markets recover, the value of those extra units can rise substantially. Investments made during difficult market periods often generate superior long-term returns compared to those made during rallies.

    SIP Share in Mutual Funds Reaches New High

    Industry data from 2026 reveals that SIP-linked equity assets now account for more than 29% of total equity mutual fund assets under management, one of the highest levels in recent years. This trend underscores growing trust in systematic investing among retail investors, even during unpredictable market conditions.

    Emotional Decisions Often Hurt Investors

    A common mistake during volatile markets is panic selling or stopping SIP contributions. When portfolio values fall, fear often drives investors to halt their SIPs, eliminating the primary benefit of rupee cost averaging. Recent data shows the SIP stoppage ratio crossed 95% in May 2026, meaning nearly 96 SIP accounts closed or matured for every 100 new registrations. Despite this, total SIP inflows remained above Rs. 30,954 crore, highlighting that disciplined investors continue regular investments while emotional decisions force others to exit prematurely.

    Why SIP Matters

    Financial experts generally advise continuing SIP investments during difficult market periods rather than stopping them. Market volatility allows investors to purchase more units at lower prices, and over long periods, lower average costs combined with compounding can generate stronger returns. The biggest mistake often stems from fear, not from market corrections themselves. Current conditions reaffirm an important lesson: market volatility may feel uncomfortable in the short term, but for SIP investors, such periods often build the strongest foundation for future wealth creation. In long-term investing, temporary market declines can become opportunities, while panic and poor decisions pose the real danger.

    Frequently Asked Questions

    1. Why is market volatility considered good for SIP investments? Market falls enable investors to buy more units at lower prices, reducing the average cost over time.
    2. Should SIP investments stop during market corrections? Experts generally advise continuing SIPs because corrections often create better long-term opportunities.
    3. What was SIP inflow in May 2026? According to AMFI data, SIP inflows remained strong at Rs. 30,954 crore.
    4. How does SIP reduce investment risk during volatility? Regular monthly investments spread purchases across different price levels, reducing market timing risk.
    5. What is rupee cost averaging in SIP? It means buying more units when prices fall and fewer when prices rise, lowering the average purchase cost over time.
  • Best IPO Index Funds in India to Watch in 2026

    Best IPO Index Funds in India to Watch in 2026

    India’s fast-growing IPO market has sparked strong interest in funds that offer exposure to newly listed companies. While pure IPO index funds are still limited in the country, several mutual fund and index fund options provide compelling access to recent public offerings and emerging market leaders. This guide explores the top choices for investors in 2026.

    Why IPO-Related Funds Are Gaining Traction

    India is experiencing one of its strongest IPO cycles, with major companies preparing for public listings. Upcoming issues like Jio Platforms (expected over Rs. 30,000 crore) and the National Stock Exchange (also around Rs. 30,000 crore) have fueled retail and institutional enthusiasm. SBI Funds Management has also received regulatory approval for its IPO. These large listings could attract global investment and broaden retail participation, making IPO-focused funds a key wealth creation theme.

    IPO-related funds allow investors to participate in early growth stages after a company’s stock market debut, without the uncertainty of direct IPO allotment. They offer diversification and professional management, though they carry higher risk due to the volatility of newly listed companies.

    Top IPO Index and Mutual Funds in India (2026)

    1. Edelweiss Recently Listed IPO Fund

    This is the closest option to a dedicated IPO fund in India. It invests primarily in companies listed within the last three years, offering exposure to their early growth phase. The fund has an AUM over Rs. 1,000 crore, a NAV near Rs. 31.95, and a minimum SIP of just Rs. 100. Its portfolio spans technology, healthcare, financial services, and manufacturing. Risk is high due to the focus on new companies.

    2. Nippon India Nifty Next 50 Index Fund

    Though not a direct IPO fund, this passive fund tracks the Nifty Next 50 index, which includes companies just below the top 50. Many successful IPOs eventually enter this category before moving to larger indices. It offers low expense ratios and strong institutional backing, making it a cost-effective way to gain indirect IPO exposure.

    3. UTI Nifty 50 Index Fund

    This trusted passive fund provides long-term exposure to India’s largest companies. While it doesn’t directly invest in IPOs, it automatically benefits when newly listed firms grow and enter the Nifty 50. With over Rs. 27,000 crore in AUM, low expense ratio, and minimal tracking error, it’s ideal for stable, diversified growth.

    4. HDFC Nifty Next 50 Index Fund

    Similar to the Nippon fund, this one focuses on companies with potential to become blue-chip stocks. Many recent IPOs enter this index after successful expansion. It offers higher growth potential than Nifty 50 funds, with the advantages of passive management and no stock selection bias.

    5. Motilal Oswal Midcap and Emerging Index Funds

    These funds target midcap and emerging companies, many of which are recent IPOs in sectors like electric vehicles, fintech, manufacturing, and consumer technology. They provide indirect access to India’s IPO ecosystem, as newly listed firms often start in the midcap space before ascending to large-cap status. Several 2026 IPOs have delivered listing gains of 70% to 150%.

    Final Outlook for 2026

    India’s stock market stands at a pivotal stage with rising public listings and strong investor participation. While pure IPO index funds remain scarce, the options above—focused on recently listed companies, emerging businesses, and future leaders—offer viable pathways. Investors should weigh the higher risk against potential rewards and consider their long-term goals.

    Frequently Asked Questions

    1. What is an IPO index fund?
    It’s a fund that gives exposure to newly listed companies after their IPO launch.

    2. Does India have dedicated IPO index funds?
    India has limited direct IPO funds, but several funds focus on recently listed companies.

    3. Which fund is closest to an IPO fund in India?
    The Edelweiss Recently Listed IPO Fund is one of the closest options available.

    4. Are IPO-related funds risky?
    Yes, these funds usually carry high risk because new companies can show price volatility.

    5. Why are IPO funds popular in 2026?
    Large upcoming IPOs and strong stock market growth have increased investor interest.