Tag: NASDAQ

  • American Bitcoin Expands BTC Reserve in Q2 Despite Revenue Miss and Stock Slump

    American Bitcoin Expands BTC Reserve in Q2 Despite Revenue Miss and Stock Slump

    American Bitcoin significantly expanded its Bitcoin holdings and mining output during the second quarter, even as revenue fell short of expectations and its stock continued to decline sharply. The company increased its reserve by 981 BTC (14%) to 8,002 BTC by June 30, up from 7,021 BTC at the end of March.

    Outstanding shares rose about 3% during the quarter, yet Bitcoin backing per share climbed from 9,943 satoshis to 10,989 satoshis. Management highlighted this metric as the company’s primary treasury goal, with CEO Mike Ho reiterating a focus on increasing Bitcoin per share. He stopped short of committing to selling Bitcoin to fund equity buybacks.

    Co-founder and Chief Strategy Officer Eric Trump doubled down on the company’s Bitcoin-centric strategy, calling the firm “absolute Bitcoin maximalists” during the earnings call. He also reflected on American Bitcoin’s rapid growth, noting that “a little over a year ago, American Bitcoin was just an idea.”

    Record Mining Output and Expanding Hashrate

    American Bitcoin mined a record 932 BTC in Q2. Mining revenue rose 8% to $67 million from $62.1 million in the prior quarter, though revenue per Bitcoin mined fell 5% to $71,900 as Bitcoin’s price dropped 12% during the period. Mining costs edged up slightly to $36,500 per Bitcoin.

    The company maintained a gross margin near 50%, offsetting weaker prices and higher energy costs with increased production. It also energized 11,298 next-generation ASIC miners at Hut 8’s Drumheller site, adding 3.05 exahashes per second (EH/s) of capacity.

    By quarter-end, American Bitcoin controlled 89,242 miners with 28.1 EH/s total capacity, operating 58,999 miners at 25 EH/s with an efficiency of 14.1 J/TH.

    Earnings Miss and Stock Decline

    Revenue came in at $67.015 million, below analysts’ $73 million estimate. The company posted a loss of $0.80 per share, far worse than the consensus forecast of a $0.15 loss. American Bitcoin continued to combine mining output with market purchases of Bitcoin.

    The stock fell 7.38% in the latest 24-hour period and has lost more than 80% over the past year. A Bloomberg report estimated that recent market performance erased about $600 million in company value. Shares have dropped 95% since their NASDAQ debut in September 2025.

    Despite the stock’s struggles, American Bitcoin now holds 8,300 BTC worth approximately $527 million, making it the 16th-largest corporate Bitcoin holder.

    Conclusion

    American Bitcoin delivered on its promise of expanding Bitcoin reserves and mining output in Q2, boosting per-share Bitcoin exposure. However, revenue missed forecasts, losses widened, and the stock remained under severe pressure. Investors face a stark contrast between the company’s strengthening Bitcoin position and its deteriorating market performance.

  • Tesla Stock Drops Near $300 After Q2 Earnings Miss Triggers Market Selloff

    Tesla Stock Drops Near $300 After Q2 Earnings Miss Triggers Market Selloff

    Tesla shares fell nearly 15% after second-quarter results raised concerns over weaker margins, negative free cash flow, and rising AI spending. The selloff pushed the stock toward the $300 support area and added pressure to the NASDAQ, while Bitcoin and Ether also declined as risk sentiment weakened.

    Tesla shares closed at $313.03 on July 24 after falling 2.08% during the session. The stock also slipped to about $311.40 in after-hours trading. Over one month, Tesla lost around 16.55% as investors reassessed the company’s second-quarter results and spending plans.

    The latest decline followed a 14.52% plunge on July 23. Tesla reported record vehicle deliveries and higher revenue, yet weaker margins and negative free cash flow drew more attention. The stock now trades close to the lower end of its recent range, with $300 becoming the nearest major technical level.

    Tesla Stock Nears Key $300 Support

    Tesla stock traded as high as $322.87 on July 24 before falling to an intraday low near $306.53. Selling pressure stayed firm after the earnings-driven decline. As a result, the shares closed only a few dollars above their first major support zone.

    The area between $306.50 and $300 now serves as short-term support. A sustained close below $300 could bring the 52-week low near $297.82 back into focus. On the other hand, buyers need to reclaim the $320 to $323 range to slow the current decline.

    Stronger resistance sits between $340 and $342. Tesla traded near that area before the post-earnings gap widened. A recovery toward that range would require stronger demand and improved confidence in the company’s profit outlook.

    Record Deliveries Fail to Calm Investors

    Tesla delivered a record 480,126 vehicles during the second quarter. The total exceeded the company-compiled estimate of about 406,000 vehicles. Model 3 and Model Y deliveries reached 467,762 units and accounted for most of the quarter’s volume.

    Revenue rose 26% from a year earlier to about $28.24 billion. Automotive revenue reached nearly $20.5 billion, while services and other revenue increased 50% to $4.58 billion. These results showed that Tesla continued to expand sales across its main business lines.

    Nevertheless, investors focused on profitability. Tesla’s operating margin fell to 1.4% from 4.1% a year earlier. Lower vehicle prices and higher costs supported deliveries but reduced earnings from each sale.

    The weaker margin also raised questions about how quickly Tesla can turn rising sales into stronger cash generation. This issue became more important as the company increased spending on artificial intelligence, batteries, robotics, and autonomous-driving systems.

    AI Spending Adds Pressure Across Markets

    Tesla’s capital expenditure reached about $5.8 billion during the quarter. Free cash flow turned negative by roughly $1.1 billion, marking the company’s first quarterly cash burn in more than two years. Tesla also expects annual capital spending to exceed $25 billion.

    The company continues to fund robotaxi development, artificial intelligence infrastructure, next-generation manufacturing, and the Optimus robot program. Meanwhile, investors are waiting for clearer revenue growth from these projects as costs rise in the near term.

    The concern spread beyond Tesla. Alphabet shares also fell as investors reviewed higher artificial intelligence spending plans. It raised its 2026 capital expenditure guidance to between $195 billion and $205 billion, up from its earlier range.

    The NASDAQ moved lower as investors reduced exposure to high-growth technology stocks. Risk-off trading also reached digital assets. Bitcoin fell about 1.8% toward $64,800, while Ether dropped around 3% to nearly $1,870. Concerns over technology spending affected several risk markets during the same trading period.

  • Dow Rises Over 300 Points as Oil Retreats on Renewed Iran-US Peace Diplomacy Hopes

    Dow Rises Over 300 Points as Oil Retreats on Renewed Iran-US Peace Diplomacy Hopes

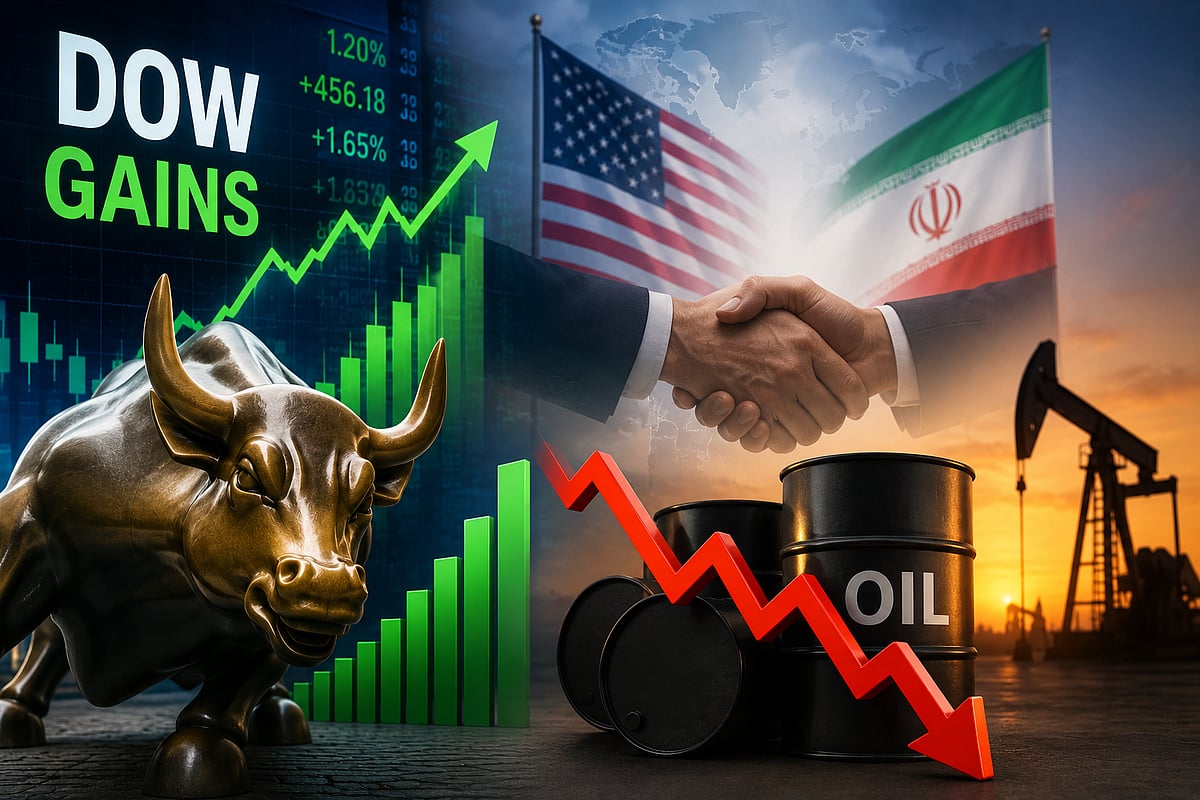
    The Dow Jones Industrial Average surged more than 300 points on Friday as oil prices tumbled following reports that Pakistan may mediate renewed talks between the United States and Iran. The S&P 500 also advanced, while the NASDAQ remained under pressure due to declines in semiconductor stocks.

    Oil Retreat Fuels Market Optimism

    The Dow gained approximately 0.7%, buoyed by a roughly 3% rise in Apple shares. The S&P 500 added around 0.6%, while the NASDAQ struggled to hold gains as chip stocks slid. Brent crude fell more than 4% to trade near $95 per barrel after surpassing $100 earlier in the week. West Texas Intermediate also dropped about 4% to above $88. Lower oil prices alleviated concerns over inflation, transportation costs, and corporate expenses.

    Pakistan Explores Peace Talks Mediation

    According to Reuters, Pakistan is exploring a path to restart stalled negotiations between the U.S. and Iran. Three Pakistani sources indicated that China initiated the diplomatic effort. Pakistani officials discussed the plan with Iranian representatives during recent meetings. However, the sources noted that “obstacles to any talks with the US remain high.” China has significant trade and energy interests in the Gulf, and Pakistan maintains close ties with Beijing, Saudi Arabia, and Iran, complicating its potential mediator role.

    Geopolitical Risks Drive Oil Volatility

    Oil had climbed above $100 earlier amid ongoing conflict in the region, raising fears of supply disruptions across the Gulf and Red Sea. U.S. strikes on Iranian targets and attacks linked to Iran-backed groups kept energy traders focused on shipping routes and production risks. The Strait of Hormuz remains a major concern for China and other large oil buyers, as any disruption could restrict crude shipments and drive up global energy costs. Friday’s diplomatic report eased some of those fears, prompting traders to sell oil futures.

    Chip Sector Caps Broader Gains

    Semiconductor stocks declined even as the Dow and S&P 500 rose. Intel dropped about 3% after initially gaining on better-than-expected results. Broadcom and Advanced Micro Devices each lost roughly 2%, while Micron Technology fell about 5%. The Philadelphia Semiconductor Index declined more than 3% in early trading. Investors continue to question the pace of artificial intelligence spending after Alphabet and Tesla reported higher capital costs and cash usage. The cautious tone set the stage ahead of earnings from Microsoft, Amazon, and Meta.

    Corporate Moves and Sector Rotation

    Verizon advanced after raising its annual forecasts for adjusted profit and free cash flow. Real estate and communication services led gains in the S&P 500 as investors rotated into sectors less exposed to chip weakness. Citi raised price targets for Dell and Hewlett Packard Enterprise, with analyst Asiya Merchant maintaining buy ratings on both, citing demand for servers, networking equipment, and AI infrastructure. Citi lifted its HPE target to $74 from $70, implying about 55% upside from Thursday’s close.

    Fed Policy and Tariffs Add to Uncertainty

    Investors also assessed new U.S. tariffs of 10% and 12.5% on goods from 60 trading partners, linked to weak enforcement of forced-labor restrictions. The new duties followed the expiration of a temporary 10% global tariff. The Federal Reserve meets next week, with markets weighing inflation risks from energy costs. Futures pricing indicates about a one-in-three chance of an interest rate hike, up from 12% a week earlier. Fed Chairman Kevin Warsh has maintained the central bank’s focus on price stability and employment.

    Despite Friday’s gains, the Dow and S&P 500 are on track for small weekly losses. The NASDAQ is headed for a decline of more than 1%, as technology weakness offsets the relief from lower oil prices.

  • Dow Rises, Nasdaq Slips as Wall Street Awaits Alphabet and Tesla Earnings Amid Rising Oil Prices

    Dow Rises, Nasdaq Slips as Wall Street Awaits Alphabet and Tesla Earnings Amid Rising Oil Prices

    U.S. stocks ended mixed on Wednesday as investors weighed rising oil prices, a downturn in semiconductor shares, and anticipation of major earnings reports from technology giants. The Dow Jones Industrial Average gained roughly 0.5%, while the S&P 500 hovered near the flatline. The Nasdaq Composite fell about 0.3%, dragged lower by weakness in chip stocks.

    Big Tech Earnings in Focus

    Alphabet, Tesla, IBM, ServiceNow, and Texas Instruments are set to report quarterly results after the closing bell. Their updates are expected to shed light on artificial intelligence spending, cloud demand, and corporate technology budgets. Alphabet and Tesla are the first members of the ‘Magnificent Seven’ to release second-quarter results, with investors closely watching revenue growth, capital expenditure, and forward guidance.

    Alphabet shares traded near $346 ahead of the report. The company faces scrutiny over its AI strategy after delaying a model launch tied to its development plans. Tesla’s results will also be closely watched as the automaker continues heavy spending on new projects. Analysts will focus on cash flow, operating costs, and capital outlays.

    Sam Stovall, chief investment strategist at CFRA Research, noted that investors may adopt a ‘wait-and-see attitude’ before making larger market moves, with spending levels playing a central role in the response to these earnings.

    Oil Prices Surge on Geopolitical Tensions

    Oil prices climbed as the United States conducted its eleventh straight round of strikes against Iran. Brent crude rose about 3% to trade above $93 per barrel, briefly crossing $95. West Texas Intermediate advanced above $86 per barrel. U.S. Secretary of State Marco Rubio stated that Washington would continue protecting shipping through the Strait of Hormuz and described Iran as ‘not serious’ about negotiations.

    Higher energy prices reignited concerns about inflation and interest rates. Federal funds futures indicated a strong likelihood that the Federal Reserve will hold rates steady at its next meeting, though markets still price in a potential rate increase later in 2026.

    Chip Stocks Weigh on Nasdaq

    Technology stocks were the weakest sector during morning trading, with semiconductor shares under pressure after several volatile sessions. The Philadelphia Semiconductor Index traded near unchanged levels, having closed lower in five of the past ten sessions. Texas Instruments edged lower ahead of its earnings release. Investors are scrutinizing chip demand, order growth, and management forecasts during this earnings season. AI infrastructure spending has supported semiconductor valuations, but recent price swings have slowed the Nasdaq’s momentum.

    Materials and utilities sectors moved higher, limiting broader market losses. Strength in industrial and materials shares also supported the Dow. Market breadth remained positive, with advancing stocks outnumbering decliners on both the NYSE and Nasdaq.

    Notable Stock Movers

    Super Micro Computer surged more than 20% after the AI server maker issued a strong business update, securing over $60 billion in new fourth-quarter orders and forecasting gross margins above previous expectations. AT&T gained about 3% after adding more wireless subscribers than analysts anticipated and reporting better-than-expected quarterly earnings.

    GE Vernova shares fell despite reporting $11.1 billion in revenue and raising its 2026 guidance, as earnings missed market estimates. The company posted an 88% rise in total orders to $24.2 billion, with data center orders exceeding $5 billion in the first half of the year—more than double its full-year total in 2025.

    Shares of generic drugmakers declined after President Donald Trump announced plans for future tariffs on imported generic medicines, starting with a 100% tariff in August 2028 and rising to 200% a year later.

    With oil prices rising and Big Tech earnings approaching, markets remain focused on the next major catalyst for direction.

  • Wall Street Futures Gain Despite US-Iran Tensions as Nasdaq Leads Tech Rally

    Wall Street Futures Gain Despite US-Iran Tensions as Nasdaq Leads Tech Rally

    U.S. stock index futures edged higher on Monday, with investors setting aside renewed military tensions between the United States and Iran as optimism over diplomatic engagement and resilient corporate earnings buoyed market sentiment.

    Despite lingering geopolitical nervousness, futures on the technology-heavy Nasdaq outperformed their peers, signaling that traders continue to focus on fundamentals and earnings rather than reacting to events in the Middle East.

    Nasdaq Futures Outperform the Broader Market

    As of 4:47 AM GMT-5, E-mini Nasdaq-100 futures rose 183.25 points, or 0.64%, to 28,956.50. E-mini S&P 500 futures gained 24.50 points, or 0.33%, to 7,522.25, while E-mini Dow Jones Industrial Average futures climbed 145 points, or 0.28%, to 52,520.00.

    The stronger showing in Nasdaq futures reflects ongoing investor interest in technology shares ahead of the start of the U.S. cash market.

    Markets Shift Focus from Conflict to Diplomacy

    Trading began cautiously following fresh U.S. military strikes against Iran, which kept geopolitical tensions elevated. During the session, oil prices were mixed and U.S. Treasuries rose, indicating initial concerns about the situation.

    However, market sentiment turned positive after Iranian Foreign Ministry spokesman Esmail Baghaei stated that communication channels remained open. According to Iranian news reports, Baghaei noted that messengers were continuing to send messages to Tehran despite the new U.S. strikes, adding that negotiations with the United States were possible as long as they aligned with Iran’s interests.

    Investors Remain Focused on Equities

    The United States has conducted its ninth consecutive strike on Iran overnight, keeping the geopolitical situation tense. Nevertheless, Monday’s gains suggest that traders are hopeful the crisis can be contained through diplomacy.

    Another key factor is that the upward movement in futures markets indicates optimism about U.S. equities. With the ongoing earnings season and strong interest in tech stocks, traders appear to be balancing geopolitical risks against stable corporate performance.

    As the U.S. cash market opens, all eyes will be on whether this positive momentum can be sustained amid ongoing geopolitical developments.

  • NASDAQ Futures Climb as Chip Stocks Rebound and Oil Prices Pull Back

    NASDAQ Futures Climb as Chip Stocks Rebound and Oil Prices Pull Back

    US technology stocks entered the new week after another sharp pullback led by semiconductor companies. The NASDAQ 100 has become more sensitive to daily moves in NVIDIA, Micron, AMD and Intel. Their rising market values have also increased their weight within the index.

    Wall Street futures moved higher on Monday as several chipmakers recovered before the opening bell. However, oil prices and the conflict involving the United States and Iran kept pressure on stocks. Investors also prepared for earnings from Alphabet, Tesla, IBM and Intel.

    Chip Stocks Drive Sharp NASDAQ Swings

    Semiconductor shares now play a larger role in NASDAQ 100 volatility. Assenagon says the weight of chip companies other than NVIDIA rose from about 15% to nearly 30%. Micron, AMD and Intel gained more influence as their valuations climbed during the AI rally.

    The asset manager said average one-year expected volatility for those companies moved above 80 points at times. That marked the highest level since the global financial crisis. Assenagon said, “Semiconductor stock volatilities are doing the heavy lifting.” Lower correlation between NASDAQ companies reduced part of the pressure, but it did not remove it.

    The Philadelphia Semiconductor Index also entered a bear market after closing more than 20% below its late-June record. Earlier data showed the index had gained 83% during 2026 before the July reversal. Chip funds then recorded large inflows and outflows as traders changed positions quickly.

    Apple and NVIDIA Trade the Top Market Spot

    Apple overtook NVIDIA on Friday to become the world’s most valuable listed company. Apple carried a market value of about $4.88 trillion. NVIDIA stood near $4.86 trillion after its shares fell 3.5%. Apple had not held the top position since April 2025.

    The change came as investors reviewed the prices attached to AI-linked companies. New model releases from China added competition within the sector. Meanwhile, concerns grew over the pace of spending on chips, servers and data centers. NVIDIA and other semiconductor companies had led much of the market’s 2026 advance.

    Bianca Botes of Citadel Global said, “The AI demand story is real,” but prices had moved ahead of earnings evidence. Recent losses in Micron, NVIDIA and other chipmakers showed how quickly sentiment could change. The moves also spread to South Korean technology stocks, including Samsung Electronics and SK Hynix.

    Oil Retreat and Earnings Lift Stock Futures

    NASDAQ 100 futures rose about 0.8% early Monday, while S&P 500 futures gained around 0.4%. Dow futures added about 0.3%. Memory chipmakers also advanced before the market opened. Micron, Western Digital, Seagate and SanDisk gained between 3.2% and 4.2%.

    Brent crude briefly moved above $90 per barrel after US forces struck Iran for a ninth straight day. Prices later eased after Iran said diplomatic contacts remained open. The early oil rise raised fresh concerns about transport costs, inflation and interest rates.

    Investors will now focus on quarterly results from major technology companies. Alphabet, Tesla, IBM and Intel will report during the week. Intel and Texas Instruments will provide new data on chip demand and AI infrastructure spending. Their reports could guide the next move across semiconductor stocks and the NASDAQ 100.

  • Wall Street Slips as Chip Rout Deepens, Netflix Forecast Disappoints, and Oil Price Worries Return

    Wall Street Slips as Chip Rout Deepens, Netflix Forecast Disappoints, and Oil Price Worries Return

    The S&P 500 fell on Friday as investors reduced exposure to semiconductor stocks. The index dropped 0.6%, while the NASDAQ Composite lost 1%. The Dow Jones Industrial Average traded near the flatline.

    Wall Street also faced pressure from Netflix, higher oil prices, and fighting between the United States and Iran. The major indexes moved toward weekly losses after a reversal in stocks linked to artificial intelligence spending.

    Chip Stocks Extend Weekly Selloff

    Semiconductor shares led the decline. NVIDIA, Advanced Micro Devices, Applied Materials, Lam Research, Intel, and KLA traded lower. The Philadelphia Semiconductor Index fell close to 2% and moved deeper into bear-market territory from its late-June peak.

    The index has lost about 11% this week and nearly 24% from its record high. Investors took profits after a three-month rally that lifted the chip gauge more than 100%. The VanEck Semiconductor ETF headed for its third weekly loss in four weeks.

    Fresh doubts over AI spending added pressure. Chinese startup Moonshot AI introduced Kimi K3, a large open-weight model that it says can compete with leading US systems. The launch raised questions over whether costly AI infrastructure plans will deliver the returns investors expect.

    Strategists at BBH said investors are ‘increasingly questioning the sustainability of the ongoing AI capital expenditure boom.’ Barclays took a less cautious view and said the pullback could create ‘more attractive entry points’ for long-term investors.

    Netflix Drops as Forecast Disappoints

    Netflix shares fell about 9% after its third-quarter forecast came in below Wall Street estimates. The decline weighed on the communication services sector and made Netflix one of the largest S&P 500 losers.

    Intuitive Surgical also dropped more than 11%. The medical device company kept its procedure-growth forecast unchanged and warned that insurance changes may delay care for some patients.

    Meanwhile, Apple shares edged higher while NVIDIA fell, allowing Apple to move ahead of the latter as the most valuable US company. NVIDIA had held the top position since late June last year.

    Meanwhile, the CBOE Volatility Index rose above 18, its highest level in more than a week. Declining stocks outnumbered gainers on both the New York Stock Exchange and the NASDAQ.

    Oil and Inflation Risks Return

    Oil prices rose as fighting between the United States and Iran widened across the Middle East. West Texas Intermediate traded above $81 per barrel, while Brent crude moved above $86.

    Kuwait said Iran attacked a power and water desalination plant. US Central Command said it completed a sixth straight night of strikes on Iranian military targets. Iran later claimed attacks on US forces in Syria and Bahrain.

    The conflict disrupted energy flows through the Strait of Hormuz, a route that handles about one-fifth of global oil traffic. Higher oil prices renewed concerns over inflation and future Federal Reserve policy.

    Cleveland Fed President Beth Hammack said business leaders are asking whether the central bank should act against inflation. She wrote that companies face pressure from energy, insurance, supply chains, and AI data center construction. Hammack added that ‘persistently high inflation is the bigger concern.’

    Consumer sentiment improved to 54.4, while one-year inflation expectations fell to 4.2%. Still, survey director Joanne Hsu said the rise may be hard to sustain if gas prices increase again.

    With semiconductor stocks under pressure, earnings disappointments weighing on sentiment, and geopolitical risks driving oil higher, investors remain focused on the outlook for inflation and Federal Reserve policy.

  • UnitedHealth Lifts Dow as Chip Selloff Pressures NASDAQ and S&P 500

    UnitedHealth Lifts Dow as Chip Selloff Pressures NASDAQ and S&P 500

    The S&P 500 and NASDAQ Composite fell on Thursday as semiconductor shares extended their decline, offsetting gains across much of the market. Strong earnings from UnitedHealth and firm economic data supported the Dow Jones Industrial Average, but technology losses kept pressure on the other major indexes.

    At 10:00 a.m. ET, the Dow rose 82 points, or 0.16%, to 52,740.92. The S&P 500 fell 0.39% to 7,545, while the NASDAQ dropped 1% to 26,100. Eight of the 11 S&P 500 sectors traded higher, showing that weakness remained concentrated in large technology names.

    Chip Stocks Lead the NASDAQ Lower

    Semiconductor shares posted the largest losses after Taiwan Semiconductor Manufacturing released its second-quarter results. Its US-listed shares fell about 2.5%, even though the company reported earnings above forecasts. Traders focused on its higher spending plan for 2026.

    TSMC raised its expected capital spending range to between $60 billion and $64 billion from $52 billion to $56 billion. The increase renewed concern over the cost of expanding artificial intelligence capacity across the chip industry. The Philadelphia Semiconductor Index fell 3.8%. Western Digital and Seagate Technology each dropped 7.3%, while Micron Technology lost 4.8%. Arm Holdings fell more than 6%, and Advanced Micro Devices and Broadcom also moved lower.

    Shiraz Ahmed of Sartorial Wealth said the chip rally is cooling, but “not because AI is losing steam.” He said AI use is still expanding across data centers, energy systems and semiconductor production.

    UnitedHealth Supports the Dow Jones

    UnitedHealth shares rose 7.8% after the health insurer posted better-than-expected second-quarter results and raised its 2026 profit forecast. The move helped keep the Dow Jones positive while the S&P 500 and NASDAQ fell. The healthcare sector gained about 2%, while consumer staples rose 2.1%. Those gains limited the broader decline, even as the information technology sector fell 1.9%.

    Meanwhile, GE Aerospace dropped 4.4% despite reporting earnings and revenue above forecasts. The company posted adjusted earnings of $2.02 per share on revenue of $12.63 billion, compared with forecasts of $1.86 and $11.86 billion. GE Aerospace also lifted its full-year guidance. United Airlines fell 2.8% as rising oil prices added pressure to its third-quarter and full-year profit outlook.

    Retail Sales and Jobless Claims Shape Rate View

    Fresh economic data showed that US consumers kept spending during June. Retail sales rose 0.2%, matching expectations. Lower gasoline prices reduced service-station receipts, while other areas of consumer spending held up. Bill Adams, Chief US Economist at Fifth Third Commercial Bank, said slower headline retail sales growth was “actually positive” since lower fuel prices drove much of the weakness. He added that the report supports second-quarter real gross domestic product growth.

    Weekly jobless claims also came in below forecasts. Initial claims fell to 208,000 for the week ended July 11, compared with expectations of 218,000. The data pointed to resilience in the labor market. Inflation reports released earlier in the week eased concern over tighter Federal Reserve policy. Traders priced an 88% chance that the central bank will leave rates unchanged at its July meeting, according to CME FedWatch data.

    Wider Market Gains Fail to Lift Major Indexes

    The market showed a split between large technology stocks and the wider group of companies. Advancing stocks slightly outnumbered decliners on the New York Stock Exchange, while declining shares held a wider lead on the NASDAQ. The Invesco S&P 500 Equal Weight ETF rose 0.6%, showing that the average company performed better than the market-cap-weighted index. The standard S&P 500 still fell as major chip and technology shares carried greater influence.

    Geopolitical concerns also stayed in focus. Reports said Iran asked Yemen’s Houthi movement to prepare for a possible closure of the Red Sea oil route if the United States strikes Iranian power facilities. The threat kept energy prices and airline costs in view during Thursday’s early trading session.

    Investors will now watch upcoming corporate earnings and economic data for clearer signals on the strength of the US economy and the Federal Reserve’s next policy move. Whether chip stocks stabilize or extend their pullback is also likely to play a key role in determining the broader market’s direction.

  • Wall Street Rises as Bank Profits and Tech Rally Boost Dow, S&P 500, and NASDAQ

    Wall Street Rises as Bank Profits and Tech Rally Boost Dow, S&P 500, and NASDAQ

    Wall Street climbed on Wednesday as investors weighed stronger-than-expected bank earnings and cooling wholesale inflation data. The Dow Jones Industrial Average, S&P 500, and NASDAQ Composite all posted gains, led by financial and technology shares.

    Indexes Gain as Inflation Eases

    The Dow rose approximately 0.4%, the S&P 500 added 0.3%, and the NASDAQ Composite gained 0.4%, supported by consumer discretionary and technology stocks. Nine of the 11 S&P 500 sectors traded in positive territory, with consumer discretionary leading and financials up 0.6%.

    Market sentiment was buoyed by a weaker-than-expected Producer Price Index report, which showed final demand prices fell 0.3% in June against expectations of no change. This followed Tuesday’s softer Consumer Price Index reading, together reducing expectations for an immediate Federal Reserve rate hike.

    Bank Earnings Support Financial Shares

    BlackRock shares surged more than 7% after the asset manager beat quarterly forecasts, reporting earnings of $13.91 per share on revenue of $7.08 billion—above the $6.72 billion expected by analysts. Assets under management rose to $15.35 trillion from $13.90 trillion.

    Morgan Stanley also gained after reporting second-quarter profit above market estimates, extending a strong start to earnings season for financial firms. “The large banks continue to demonstrate the strength of the US consumer and corporate balance sheets,” said Charlie Anderson of UBS Wealth Management, adding that healthy banks support broader economic confidence.

    PayPal Jumps on Reported Takeover Offer

    PayPal shares jumped nearly 14% following reports that Stripe and Advent International submitted a joint acquisition offer valuing the company at approximately $53 billion, or $60.50 per share—a premium of about 28% over Tuesday’s close. The offer comes as PayPal works to improve growth and defend its position in digital payments. Neither party announced a completed agreement during the session.

    Technology Stocks Add to Market Gains

    Large technology stocks supported the broader market. Amazon, Apple, and Microsoft each gained around 3%, while Alphabet rose more than 1%. ASML shares advanced after the Dutch chip equipment maker raised its sales forecast, citing strong demand for systems used in advanced AI chip production. ASML also plans to expand equipment production capacity by 30%, easing supply chain concerns.

    Investors are also watching TSMC, which will report second-quarter earnings on Thursday, with focus on spending plans, AI chip demand, advanced packaging capacity, and its 2-nanometer production schedule.

    Fed Policy and Oil Prices Stay in Focus

    Traders reduced the probability of a July rate hike to about 12%, down from 41% before Tuesday’s CPI release, according to CME FedWatch data. Federal Reserve Chair Kevin Warsh continued his congressional testimony, cautioning that one inflation report is not enough to confirm a lasting trend.

    Oil prices moved higher after the United States launched additional strikes against Iran, with West Texas Intermediate above $80 per barrel and Brent above $85. Higher crude prices limited some of the market’s advance as investors monitored the Middle East conflict for effects on energy costs and future inflation readings.

    Meanwhile, Elevance Health fell more than 8% despite raising its annual profit forecast, as the revised outlook failed to meet investor expectations. Advancing stocks outnumbered decliners on both major US exchanges.

    Disclaimer: Analytics Insight does not provide financial advice or guidance on cryptocurrencies and stocks. This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before making investment decisions.

  • S&P 500 Gains as June Inflation Slows and Bank Profits Surge

    S&P 500 Gains as June Inflation Slows and Bank Profits Surge

    U.S. stocks climbed on Tuesday after June inflation data came in cooler than expected, easing fears of an imminent Federal Reserve rate hike. The S&P 500 rose 0.5%, the NASDAQ Composite added 1%, and the Dow Jones Industrial Average gained roughly 86 points, or 0.2%. However, a steep drop in IBM shares and rising oil prices capped broader gains.

    June Inflation Data Boosts Market Sentiment

    The Consumer Price Index fell 0.4% in June from the prior month, bringing the annual inflation rate down to 3.5% from 4.2% in May. Economists had anticipated a 0.2% monthly decline and a 3.8% annual rate. The softer data reduced concerns that rising energy costs would push prices higher, and Treasury yields fell in response, lifting technology and housing-related stocks. Builders FirstSource and Lennar both gained as borrowing costs eased.

    Traders also scaled back bets on a July rate increase. According to CME FedWatch data, the probability of a hike dropped to 17% from 42% the previous day. Markets still see a higher chance of tighter policy at the September meeting.

    Bank Earnings Lift Financial Sector

    Major banks kicked off second-quarter earnings season with stronger-than-expected profits. Goldman Sachs rose after beating estimates, driven by dealmaking and equities trading. JPMorgan Chase, Citigroup, and Bank of America also gained on higher quarterly earnings. Wells Fargo traded lower despite reporting profit above expectations. The broader S&P 500 financial sector moved higher, with most major sectors posting gains during early trading.

    Investors are watching earnings reports for insights into consumer spending, business activity, and credit conditions. The reports showed steady card spending and stronger trading revenue, along with fresh data on loan demand.

    IBM Plunge Weighs on Dow

    IBM shares tumbled about 24% after the company warned that second-quarter revenue and profit would miss expectations due to weak demand in software and infrastructure. The decline pressured the Dow and dragged down other software stocks, including Oracle, ServiceNow, and Accenture. CEO Arvind Krishna acknowledged that the company failed to close several large deals on schedule, stating, “We did not adapt and move quickly enough,” while pointing to weaker execution across key businesses.

    Oil Prices Rise Amid Geopolitical Tensions

    Oil prices climbed as tensions between the United States and Iran escalated. U.S. crude traded above $80 per barrel, and Brent crude moved above $85 after President Donald Trump announced plans to restore a blockade on Iranian shipping through the Strait of Hormuz. The move raised concerns about global energy supplies. Higher fuel costs could slow the recent decline in inflation and maintain pressure on the Federal Reserve.

    Skyler Weinand of Regan Capital noted that the inflation surge linked to the conflict may be fading but warned that the relief “may just be temporary” as regional tensions increase.

    Chip Stocks Rebound After Monday’s Losses

    Semiconductor shares recovered after heavy selling in the previous session. The VanEck Semiconductor ETF rose nearly 2%, and the Philadelphia Semiconductor Index gained more than 3%. Applied Materials, Teradyne, Lam Research, Micron Technology, and STMicroelectronics all moved higher. NVIDIA also gained after falling sharply on Monday. The rebound helped the NASDAQ recover part of its previous decline, while investors continued to watch valuations in the volatile AI sector.

    Fed Chair Kevin Warsh prepared to testify before Congress later Tuesday, reiterating that returning inflation to the central bank’s 2% target remains a priority. He did not provide a direct signal about the Fed’s next rate decision.

    Disclaimer: Analytics Insight does not provide financial advice or guidance on cryptocurrencies and stocks. This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before making any investments.