Contactless payments feel instant, but layers of security work underneath. NFC connects the device to the terminal. EMV and tokenization protect card credentials. Cryptography authenticates each transaction. Issuers apply fraud checks before approval. Credentials are steadily fading from view, becoming identity systems.
A tap takes a moment. Behind that moment sits a stack of technology built over two decades, involving radio waves, cryptography, and a chain of banking infrastructure most people never see.
Contactless payment has become routine at grocery counters, metro gates, and coffee shops. Few people using it understand what happens between the tap and the beep. The customer sees tap, beep, done. The payment system performs several steps in rapid succession: connection, credential exchange, cryptographic authentication, authorization, and fraud screening. That contrast is the real story.
Near Field Communication Starts the Transaction
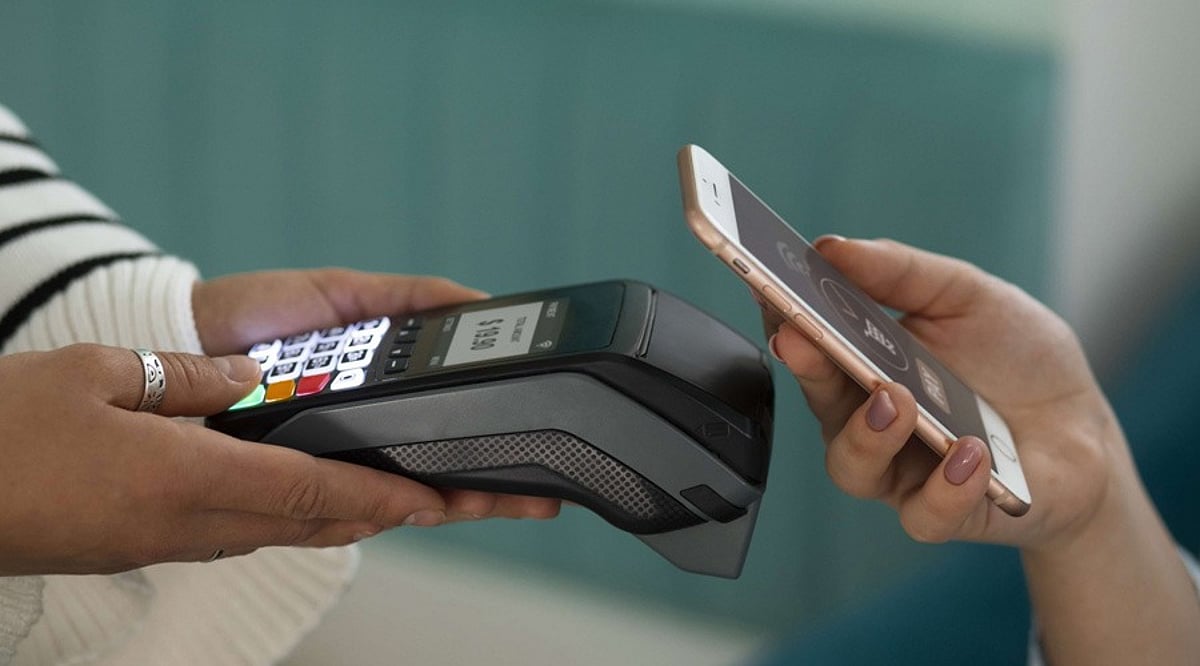
Every contactless transaction begins with Near Field Communication (NFC). This is a short-range radio technology that activates only within a few centimeters. The card or phone contains a small antenna and chip. The payment terminal generates a low-power magnetic field. When the two come close, the card’s chip draws power from that field itself, without needing a battery.
A contactless card has no power source. The terminal effectively wakes the chip during the tap, powers it briefly, and exchanges data before the field disappears. NFC communication itself happens in milliseconds, though the full authorization that follows depends on the payment network, the issuer, and the terminal.
What the Card or Phone Actually Sends
Physical cards use EMV chip security to generate transaction-specific authentication data during each tap, while digital wallets can add tokenization to protect the underlying card number. These are related but distinct systems. A physical contactless card and a phone-based wallet protect the transaction differently, even though both work to prevent the raw card number from being freely exposed.
This distinction matters for anyone comparing payment methods. A lost physical card still carries some exposure risk tied to its chip data. A lost phone, by contrast, typically exposes only a token linked to that one device, not the underlying account number itself.
Cryptography Makes Each Transaction Different
The payment chip, whether on a card or in a wallet, uses cryptographic processes to generate transaction-specific authentication data. Because that data is tied to the individual transaction, simply copying information captured from one payment does not produce a valid second transaction.
On the device side, contactless cards use secure chips to hold and protect payment credentials. Some phones use dedicated secure hardware, while other payment architectures use different combinations of tokenization, trusted execution environments, and software-based security. The exact setup varies by device manufacturer and payment system, and no single architecture applies across all devices.
From Tap to Bank Approval
The tap is only the first step. The terminal reads the payment credentials and transaction data, then sends an authorization request through the merchant’s payment infrastructure. The payment network routes that request to the card issuer, which checks the account and applies fraud controls before returning an approval or decline. Settlement, where funds actually move between banks, happens later. The instant beep at checkout marks approval, not completion of the full payment cycle.
Why Some Payments Still Ask for a PIN
Many contactless systems apply a transaction-value limit before requiring additional verification, such as a PIN. Some issuers can also require verification after a series of contactless transactions. These controls limit the potential exposure from repeated low-friction payments while keeping everyday purchases fast. Card networks and regulators typically review these limits periodically based on fraud data and regional banking rules, rather than fixing them permanently.
Fraud Detection Works Behind the Scenes
Fraud protection does not stop at the tap. Issuers and payment providers watch for patterns during authorization, checking things like past transaction behavior, the device being used, and where the merchant sits in the risk spectrum. This means security is not resting on a single moment. It is spread across a system built to catch problems before approval happens.
That same thinking now fits on a wrist or a finger. Contactless payments have moved into rings and smartwatches, letting people pay without pulling out a card or phone at all. What stands out is not the new form factor itself, but how easily the same protection travels with it. The hardware keeps changing shape. The security underneath stays consistent.
The Future of Payments Is Becoming Credentialless
Contactless payment succeeds by moving complexity away from the customer, not by eliminating it. NFC provides the connection, EMV and tokenization protect payment credentials, and cryptographic processes authenticate the transaction. The next shift is making those credentials even less visible to users. A card number may already be hidden behind a phone, watch, or other device, turning payment into an identity and authentication process rather than a simple exchange of card details.
Final Thought
The physical card is slowly losing its importance, even though it still looks the same at checkout. Biometrics and device identity are already doing more of the verification behind the scenes. So the tap itself won’t change much for a while. But what’s happening underneath it will keep getting quietly upgraded.