Tag: stablecoin

  • Tether Assists US Authorities in Freezing $550 Million in Iran-Linked USDT Amid Expanded Sanctions

    Tether Assists US Authorities in Freezing $550 Million in Iran-Linked USDT Amid Expanded Sanctions

    Tether announced on Monday that it helped US authorities freeze nearly $550 million in Iran-linked USDT this year, as Washington expands sanctions involving cryptocurrency networks. The stablecoin issuer detailed two major freezes involving TRON addresses linked to US sanctions, which together accounted for more than $474 million of the total.

    April Freeze Targets Central Bank of Iran

    In April, Tether locked more than $344 million in USDT across two TRON addresses after receiving information from US authorities. The Treasury’s Office of Foreign Assets Control (OFAC) added both addresses to its Central Bank of Iran sanctions entry on April 24, linking the bank to the IRGC Qods Force and Hezbollah.

    July Freeze Follows OFAC Expansion

    OFAC later added four more TRON addresses to the same sanctions entry on July 14. Tether then froze more than $130 million in USDT across those wallets. The April and July actions together totaled more than $474 million. Tether said its Iran-related freezes this year reached nearly $550 million, though it did not itemize the remaining amount.

    Tether CEO Paolo Ardoino noted that public blockchains give authorities greater visibility into fund movements than cash, and that Tether can respond when law enforcement provides credible information.

    US Treasury Intensifies Pressure on Iran-Linked Networks

    The freezes came as the US Treasury increased pressure on Iran-linked financial networks. In June, Treasury sanctioned Nobitex, Iran’s largest cryptocurrency exchange, for helping Iran’s central bank obtain stablecoins that supported the falling rial. Treasury Secretary Scott Bessent launched Operation Economic Outcast on August 24, targeting financial networks connected to the Iranian government. The initiative covers digital assets, technology, gold, aviation, and shipping, as Treasury said Iran increasingly uses cryptocurrency to avoid sanctions, including transactions connected to the IRGC.

    On September 17, OFAC sanctioned Iranian crypto exchange BitBank, which Treasury said is controlled by sanctioned financier Babak Zanjani. Treasury alleged that BitBank moved hundreds of millions of dollars in Bitcoin to the IRGC during June and July.

    Broader Enforcement and Collaboration

    Tether also said it has worked with Israel’s National Bureau for Counter Terror Financing for several years. Through more than 40 referred cases, Tether froze over 22 million USDT. In September 2025, the bureau published 187 crypto addresses linked to the IRGC, and blockchain analytics firm Elliptic said those wallets received $1.5 billion in USDT. Tether later blacklisted 39 of those addresses and froze nearly $1.5 million remaining in them.

    Across all enforcement-related cases, Tether has helped freeze more than $4.9 billion, with over $2.4 billion of that amount involving US authorities.

    EQIBank Exposure Raises Separate Questions

    Tether has also disclosed exposure to EQIBank, which is challenging a US seizure involving payment processor Capstone Limited. On September 25, Tether told PYMNTS that its exposure represented less than 0.034% of the Tether group’s assets, without providing a dollar figure. The company did not say whether that exposure forms part of the reserves backing USDT. The US government filed a civil forfeiture complaint in July, listing about $83.03 million across three bank balances and approximately 1.18 million USDT at two addresses. A later court order identified the bank accounts as belonging to Capstone, but the court record does not identify the listed property as Tether’s assets. EQIBank sought the return of seized property, but a court denied that motion, leaving the final forfeiture case unresolved.

  • XRP Ledger Stablecoin Market Cap Surpasses $1.159 Billion; RLUSD Leads with 92% Share as Permission Delegation Upgrade Nears Activation

    XRP Ledger Stablecoin Market Cap Surpasses $1.159 Billion; RLUSD Leads with 92% Share as Permission Delegation Upgrade Nears Activation

    XRP Ledger Stablecoin Market Cap Hits $1.159 Billion

    The XRP Ledger’s stablecoin market capitalization reached approximately $1.159 billion on September 25, after adding $67.12 million over the previous week, according to data from DefiLlama. Ripple USD (RLUSD) was the primary driver, accounting for $1.067 billion of the total — a dominant 92.1% share of the tracked stablecoin market on the network.

    RLUSD Continues to Dominate Stablecoin Growth

    RLUSD’s market cap on the XRP Ledger rose 11.55% over the past 30 days, outpacing the overall stablecoin market on the network, which expanded 9.8% in the same period. This growth further widened the gap between RLUSD and its competitors. For example, USDC’s tracked market cap on XRPL dropped 21.86% over the month to approximately $4.62 million, although it rebounded 6.71% in the latest week — just above RLUSD’s 6.69% weekly increase. Other stablecoins also saw declines: Valtorum USD fell 7.03% to $72.77 million, and EUR CoinVertible dropped 2.37% to around $11.37 million.

    These figures track only balances recorded on the XRP Ledger and do not represent each stablecoin’s total circulation across all supported blockchains. The data also does not confirm that holders exchanged USDC or other tokens directly for RLUSD; such movement would require transaction-level evidence.

    Stablecoin Growth Is Not Directly Tied to XRP Buying

    DefiLlama defines chain stablecoin market capitalization as the total tracked value of stablecoins on a blockchain, distinct from trading volume or DeFi deposits. Therefore, the $67.12 million weekly increase does not represent an equivalent amount of XRP purchases, nor does it confirm institutional investment without identifying the entities behind the balances. The available data shows RLUSD as the most tracked stablecoin on XRPL but does not reveal who holds the tokens or why balances grew.

    RLUSD is designed to maintain a one-dollar value, backed by segregated cash and cash-equivalent reserves. It operates on both the XRP Ledger and Ethereum, meaning the $1.067 billion figure only reflects the portion on XRPL. Ripple notes that RLUSD targets payments, settlements, and treasury flows, while XRP remains XRPL’s native cryptocurrency with a market-determined price.

    XRPL Upgrade Targets Institutional Permission Controls

    The XRP Ledger is approaching a second attempt at the PermissionDelegationV1_1 amendment, which entered a 14-day activation countdown on September 21 after 29 of 35 trusted validators signaled support. If validator support holds at or above the required 80% threshold, the amendment could activate on October 5.

    This feature would allow account owners to delegate specific actions — such as transaction processing — without granting full control over the account. Each delegate can receive up to 10 permissions, and the main account can revoke them at any time. For example, a payments desk could be authorized to process transactions without the ability to change critical security settings. Stablecoin issuers and custodians could use internet-connected systems for daily operations while keeping higher-level account keys offline.

    The amendment replaces an earlier version that was rejected by validators after a community tester discovered a flaw on a testnet. The flaw allowed an attacker to make another account pay fees for improperly signed transactions, potentially draining XRP through repeated transaction charges. The revised amendment, included in xrpld 3.3.0, changes how the network handles unauthorized transactions, preventing fee charges before signature verification.

    Conclusion

    The XRP Ledger’s stablecoin market capitalization has reached $1.159 billion, with RLUSD commanding a 92.1% share. Meanwhile, the PermissionDelegationV1_1 amendment, which introduces more granular account controls, is on track for possible activation on October 5 after developers fixed a security flaw in the earlier version.

  • Stablecoin Contractor Payouts: How to Keep Invoices and Records Audit-Ready

    Stablecoin Contractor Payouts: How to Keep Invoices and Records Audit-Ready

    Key Takeaways

    • A stablecoin transfer confirms on-chain in minutes, but an auditor checks the same three things they check on a bank payment: an agreement, a matching invoice, and proof the money reached the right person.
    • US payers still need a signed W-9 or W-8BEN on file before the first payout. From 1 January 2026 the 1099-NEC reporting threshold moves to $2,000, and missing documentation defaults to backup withholding.
    • A transaction hash is not an invoice. It confirms a transfer happened; it says nothing about what the payment was for or which agreement it settles.
    • Wallet address verification — matching the network, confirming the recipient, testing a new address with a small transfer — does the job a bank’s account-verification step used to do, and skipping it is the most common way a payout ends up unrecoverable.

    How Stablecoin Payouts to Contractors Work

    A stablecoin is a token issued on a blockchain and pegged to a reference currency, usually the US dollar. Paying a contractor in one means moving that token from the payer’s wallet (or a platform’s custodial wallet acting on the payer’s behalf) to an address the contractor controls, on whichever network the token was issued on — Ethereum, Tron and Solana each host their own version of USDT, and they are not interchangeable.

    The transfer itself has three stages that matter for a paper trail:

    1. Broadcast. The sender signs a transaction specifying the token, the amount and the destination address, and submits it to the network.
    2. Confirmation. Validators on that network include the transaction in a block. Once confirmed, it is final — there is no chargeback, no dispute process with a receiving bank, and no correspondent bank re-checking the route days later.
    3. Settlement. The contractor’s wallet balance updates immediately. What happens after that — holding the stablecoin, moving it to an exchange, converting to local currency — is the contractor’s own step, separate from the payout itself.

    The practical difference from a wire is that there is no banking-hours cutoff and no multi-day routing through intermediary banks. A transfer either confirms within minutes or it fails outright, usually because the destination address, network or gas allowance was wrong. There is no middle state where a payment sits pending for three days while a correspondent bank works out where to route it.

    Picture a design studio in Bangalore paying an illustrator in Lagos for a set of assets delivered against a signed statement of work. Under a wire, the studio’s bank would route the payment through one or two correspondent banks, and the illustrator would see funds land some business days later, net of an exchange-rate margin taken somewhere along the chain. Under a stablecoin payout, the illustrator sees the balance change the same day, but the studio’s finance team still needs the same statement of work, the same invoice, and now also a transaction hash to show where that specific payment landed.

    What Auditors Look For

    None of this removes the paperwork; it just changes which document proves what. An auditor reviewing a book of contractor payouts, stablecoin or otherwise, is checking for a handful of specific things:

    • A signed agreement predating the work. Whether it’s a master service agreement or a per-project statement of work, the contract has to exist before the invoice it’s tied to; reconstructing it afterward doesn’t hold up.
    • Tax documentation collected before the first payout. A US payer collects a W-9 from a US person, or a W-8BEN (individual) or W-8BEN-E (entity) from a foreign one, and keeps it on file — these forms are not filed with the IRS, but their absence matters. A W-8BEN expires at the end of the third calendar year after it’s signed, so a contractor paid for years on the same form is a document an auditor will flag as stale.
    • Correct withholding treatment. Compensation for services is sourced to where the work was actually performed. A non-US contractor doing all their work outside the US generally triggers no 1099 and no 1042-S, and no withholding, but only if the payer holds a valid W-8 form. Without that documentation, the default is backup withholding: 24% for a domestic payee, 30% for a foreign one. A US citizen or green-card holder living abroad is still a US person for this purpose and needs a W-9, not a W-8BEN.
    • The right reporting threshold applied. From payments made on or after 1 January 2026, the 1099-NEC reporting threshold is $2,000 per payee per calendar year, replacing the long-standing $600 figure. The first forms reflecting the new threshold are the ones filed in early 2027.
    • An invoice that satisfies the contractor’s own jurisdiction as well as the payer’s. For a non-US payer working with a contractor abroad, cross-border B2B services are typically handled under a reverse-charge arrangement: the VAT liability shifts to the buyer, but the paperwork requirement doesn’t disappear. On top of that, the invoice format itself has to meet the contractor’s own country’s rules, which vary (Brazil’s nota fiscal, for instance, has no direct equivalent elsewhere), and a payer often needs evidence the contractor is properly registered as self-employed under their local regime.

    A stablecoin payout doesn’t touch any of these obligations. It changes the settlement rail; the documentation an auditor expects to see attached to it stays the same.

    Linking Each Payout to an Agreement and an Invoice

    The gap that actually causes delays during an audit is a structural one: on-chain history and paper records live in two different systems, and nobody connects them until someone has to.

    A workable practice ties three references together for every payout: the agreement it falls under, the invoice number and amount, and the transaction hash that moved the funds. A few points make that link hold up:

    • The agreement should specify the settlement currency, including which stablecoin and which network. A USDT address on Tron is a different destination from a USDT address on Ethereum, and the contract terms should say which one applies.
    • The invoice is usually still denominated in a fiat currency even when settlement happens in a stablecoin, at a reference exchange rate agreed at the time of payment. That rate and its timestamp belong in the record, because a stablecoin’s peg drifts slightly against its reference currency, and an auditor checking the math needs to know which rate was used.
    • The transaction hash, the unique identifier a blockchain assigns to a confirmed transfer, gets recorded against the invoice number the moment the payout settles, before anyone has to reconstruct it later from wallet history.
    • A running register (invoice number, date, amount, currency, destination address, transaction hash, agreement reference) turns a scattered set of on-chain transfers into something an auditor can trace payout by payout, without a pile of anonymous balance changes to match up afterward.

    Skip that register and a stablecoin payout becomes exactly the kind of entry auditors are trained to distrust: a value moved between two addresses, with nothing attached that explains what it was for.

    Wallet and Address Verification

    A wallet address carries no name. Matching it to the right person is entirely the payer’s responsibility, and it’s the step most often skipped when a payout needs to go out quickly.

    A few checks do most of the work:

    • Matching the network to the address. An address formatted for one chain is not valid on another; sending a token to the wrong network is a common way for funds to become unrecoverable.
    • Confirming ownership before the first payout. Some platforms have the contractor supply and confirm their own wallet address during onboarding. That removes the step where address-interception fraud tends to concentrate: the payer collecting an address by email.
    • Testing new or large payouts with a small transfer first, then sending the full amount once the small one is confirmed received at the right address.
    • Treating the transfer as final once confirmed. Once a stablecoin transfer clears, there is no recall and no thirty-day chargeback window to fall back on. A mistake at this stage is a loss to write off, not an administrative correction to make later.

    None of this is exotic; it’s the same discipline banks apply when they verify a new payee before a first wire. Stablecoin rails just move the responsibility for that check from the bank onto whoever operates the payout.

    Platforms That Combine Payouts and Documents

    Because a stablecoin payout on its own produces a transaction hash and nothing else, the practical answer for a distributed team is a platform that generates the agreement, the invoice and the payout record together, so nobody stitches a blockchain explorer to a spreadsheet after the fact.

    4dev.com is one example of this category. It’s built around a Contractor of Record model: a client signs one agreement with 4dev.com that covers every contractor engaged through the platform, and the platform operates across 150+ countries. Contractors self-onboard through the platform, supplying their own identity and payment details, and the platform checks documents and status during that process, so the client sees each contractor’s readiness in real time without chasing paperwork by email. Closing documents are generated per payout and exportable on demand, which is the piece that turns a payout history into something an auditor can actually review.

    On the payment rail itself: 4dev.com can legally pay a contractor in USDT with closing documents attached, and it also accepts crypto payments from clients directly. Its published pricing is a service fee of 3% or less per payout, with no subscription and no account fee. What it doesn’t do is employ anyone directly: there’s no employer-of-record product today (one is planned for 2027) and no payroll for staff employees, since the platform is built for contractor engagements. On the trust side, 4dev.com doesn’t publish formal security certifications such as SOC 2 or ISO 27001, so a buyer weighing that specifically should factor it in.

    The pattern generalizes beyond any one vendor: a platform built for contractor payouts pairs the payment rail with the paperwork by default, so the agreement, the invoice and the transaction record are already linked when an auditor asks to see them, well before the once-a-year scramble to assemble them under deadline.

    FAQ

    Does a stablecoin payout still need an invoice?

    Yes. Confirming a transfer on-chain shows that value moved between two addresses — it doesn’t establish what the payment covered or which agreement it settles. Reconstructing that link after the fact, from wallet history alone, is exactly what an audit flags as missing documentation.

    What happens if a contractor gives the wrong wallet address or the wrong network?

    Usually nothing can be done. A confirmed blockchain transaction has no recall and no dispute process; funds sent to an unowned or mismatched address are typically gone. That’s why verifying the address, and matching the network before sending, matters more here than it does with a bank transfer that can sometimes be recalled.

    Does paying a contractor in a stablecoin change US 1099 reporting?

    No. The 1099-NEC reporting obligation depends on where the services were performed and what tax documentation the payer holds — a W-9 for a US person, a W-8BEN or W-8BEN-E for a foreign one. The currency or rail the payout settles in plays no part in that. The threshold itself moves to $2,000 per payee per year for payments made from 1 January 2026, replacing the previous $600 figure, regardless of whether the payout arrives by wire or on-chain.

  • Meru Evolves from Crypto Infrastructure to a Global Financial Ecosystem Across 132+ Countries

    Meru Evolves from Crypto Infrastructure to a Global Financial Ecosystem Across 132+ Countries

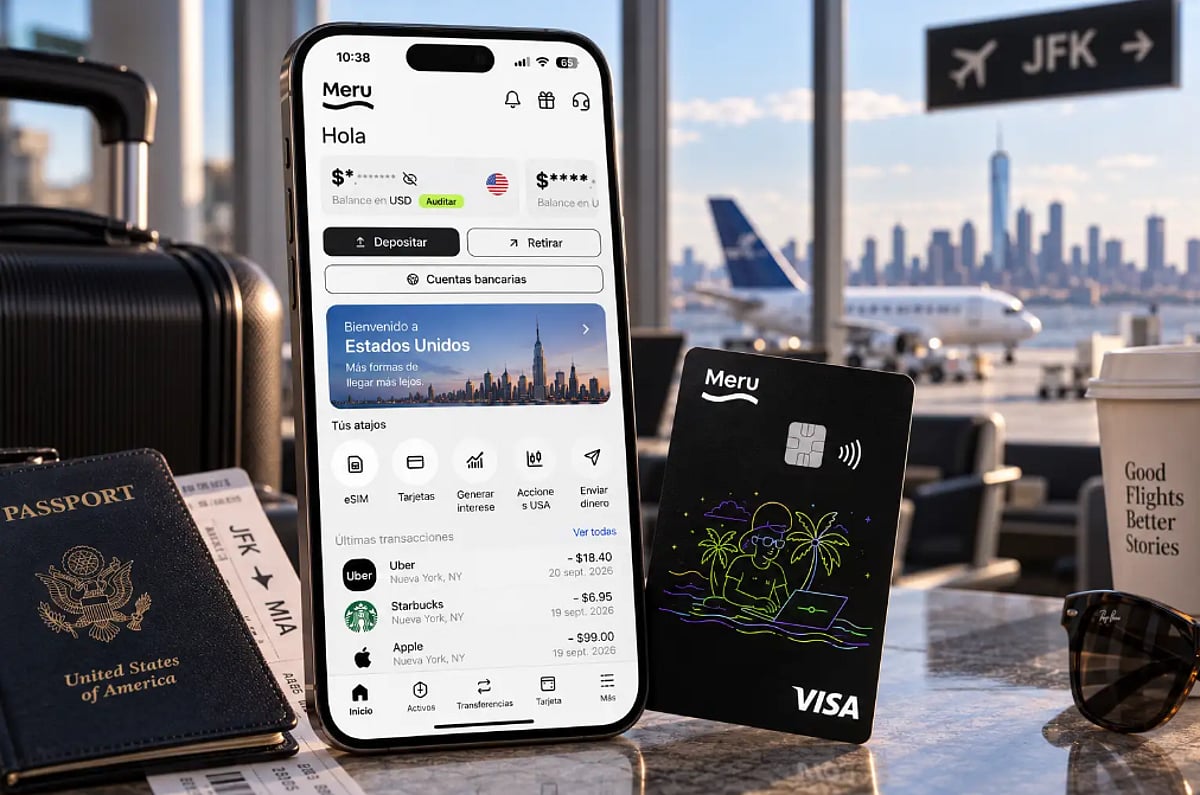
    Meru has undergone a significant transformation, evolving from a stablecoin-focused crypto platform into a comprehensive global financial ecosystem. Now operating in more than 132 countries, the company offers a suite of services including digital dollars, international money transfers, decentralized finance (DeFi) tools, and access to US-listed stocks. With self-custody assets surpassing $1.5 billion, Meru exemplifies how crypto infrastructure is being repurposed to serve broader financial needs.

    Stablecoins as a Foundation

    Stablecoins were the cornerstone of Meru’s early development. These digital assets, typically pegged to fiat currencies like the US dollar, enable seamless transfers across blockchain networks while avoiding the volatility of cryptocurrencies such as Bitcoin and Ether. This technology allowed Meru to build cross-border payment solutions that bypass traditional banking intermediaries, reducing fees and settlement times from days to near-instantaneous.

    From Crypto Platform to Financial Ecosystem

    Meru’s evolution is evident in its expanding product lineup. Users can now hold digital dollars, send international transfers, and use the Meru Card to link their digital assets to everyday spending. The platform also integrates DeFi tools and stock trading, consolidating services that once required multiple apps and accounts. This integration narrows the gap between traditional finance and crypto, making financial tools more accessible.

    Expansion in Latin America and Spain

    Meru’s growth is particularly strong in Latin America and Spain, regions where cross-border economic activity and mobility drive demand for flexible financial solutions. In Latin America, digital dollars offer a stable store of value and a means to move funds efficiently. Spain serves as a bridge to the region, leveraging cultural and economic ties. Meru’s platform is thus positioned to serve everyday transactions beyond crypto trading.

    Crypto Infrastructure Goes Mainstream

    Meru’s trajectory reflects a broader trend: the blurring line between traditional finance and the crypto world. Stablecoins and blockchain technology are no longer niche tools for digital asset trading; they are becoming the backbone for global financial services. By starting with stablecoin infrastructure and expanding into a full financial ecosystem, Meru demonstrates how crypto can outgrow its original boundaries to deliver practical, cross-border financial solutions.

  • Essential Crypto Glossary: 25 Key Terms Every Investor Must Understand

    Essential Crypto Glossary: 25 Key Terms Every Investor Must Understand

    Cryptocurrency has developed its own vocabulary spanning blockchain technology, trading, decentralized finance, and market analysis. Understanding the terminology does not eliminate investment risk, but it makes it easier to evaluate projects, exchange products, and market data without confusing fundamentally different concepts. Here are 25 terms investors should know before investing.

    Blockchain and Asset Basics

    1. Blockchain: A distributed database where transactions are grouped and recorded according to network consensus rules.
    2. Bitcoin: The largest cryptocurrency by market capitalization and the native asset of the Bitcoin network.
    3. Altcoin: A general term for cryptocurrencies other than Bitcoin.
    4. Stablecoin: A crypto asset designed to maintain a relatively stable value, commonly against currencies such as the US dollar.
    5. Token: A digital asset created on an existing blockchain rather than necessarily operating its own independent network.
    6. Wallet: Software or hardware used to manage blockchain accounts and signing keys.
    7. Private Key: Secret cryptographic information allowing a holder to authorize blockchain transactions.
    8. Seed Phrase: A sequence of words used to recover many self-custody cryptocurrency wallets.

    Trading Terminology

    1. HODL: Holding cryptocurrency for an extended period rather than reacting to short-term volatility.
    2. Market Capitalization: Token price multiplied by circulating supply.
    3. Trading Volume: The value of assets traded during a specified period.
    4. Liquidity: How easily an asset can be bought or sold without significantly changing its price.
    5. Slippage: The difference between an expected trade price and the actual execution price.
    6. Bull Market: A prolonged period characterized by broadly rising prices.
    7. Bear Market: A prolonged period of generally declining prices.
    8. Volatility: The magnitude and frequency of price fluctuations.
    9. Leverage: Borrowed exposure that magnifies both potential gains and losses.
    10. Liquidation: Forced closure of a leveraged position when collateral becomes insufficient.
    11. Open Interest: Outstanding futures or derivatives contracts that remain open.

    Blockchain and DeFi

    1. Gas Fee: A charge paid for computation or transactions on networks such as Ethereum.
    2. Smart Contract: Blockchain-based code that executes predefined instructions.
    3. DeFi: Decentralized finance applications providing activities such as trading, borrowing, and lending through blockchain protocols.
    4. Staking: Committing eligible crypto assets to proof-of-stake systems or related protocols in exchange for potential rewards.
    5. Total Value Locked: A measure of assets deposited into DeFi protocols, although methodologies can differ across data providers.
    6. DEX: A decentralized exchange where blockchain-based smart contracts or protocol infrastructure facilitate asset trading.

    Why This Matters

    Understanding crypto terminology helps investors interpret market data and distinguish fundamentally different risks. Metrics such as market capitalization, trading volume, and TVL measure different aspects of crypto markets, making basic terminology essential before evaluating tokens, protocols, or trading opportunities.

    Final Thoughts

    Knowing crypto terminology helps investors distinguish technology, market structure, and trading metrics. However, understanding terms such as staking, leverage, or market capitalization should be the beginning of research rather than a substitute for evaluating token economics, security, liquidity, and investment risk.

    Frequently Asked Questions

    What are the most important crypto terms for beginners?

    Beginners should understand blockchain, Bitcoin, wallets, private keys, stablecoins, market capitalization, and liquidity. These concepts provide a foundation for understanding how cryptocurrencies and markets operate.

    What does HODL mean in cryptocurrency?

    HODL refers to holding cryptocurrency for an extended period instead of reacting to short-term price movements. The term has become associated with long-term crypto investing strategies.

    What is market capitalization in crypto?

    Crypto market capitalization is generally calculated by multiplying a token’s current price by its circulating supply. It helps indicate an asset’s relative market size but does not measure liquidity.

    What is the difference between DeFi and a DEX?

    DeFi describes blockchain-based financial applications covering activities such as trading, lending, and borrowing. A DEX is a specific type of decentralized platform or protocol used to facilitate crypto trading.

    What does TVL mean in cryptocurrency?

    Total Value Locked (TVL) measures assets deposited into DeFi protocols under a given methodology. It can indicate protocol usage but should not be treated as a standalone measure of investment quality.

    Disclaimer: This article is for informational purposes only and does not constitute financial advice. Cryptocurrency investments carry risk, and you should conduct your own research before making any investment decisions.

  • Crypto in 2026: The Macro Forces Shaping Bitcoin and Ethereum Markets

    Crypto in 2026: The Macro Forces Shaping Bitcoin and Ethereum Markets

    Crypto stopped trading on its own terms a while back. Bitcoin and Ethereum now move with the same signals that shake stocks and bonds: interest rates, inflation, the dollar, and job numbers. The thread connecting all of it is liquidity. Fed policy shifts financial conditions, and financial conditions decide how much capital investors are willing to put into assets that don’t pay a yield.

    The Fed’s Rate Hike Resets Expectations

    On September 16th, the Federal Reserve raised its benchmark rate by 25 basis points to a range of 3.75% to 4.00%. It was the first hike in three years, and the vote was unanimous. For most of 2026, the conversation had centered on when rate cuts might arrive. That conversation flipped. The Fed’s updated projections showed roughly 16 of 18 officials expecting at least one more increase before the year ends.

    For crypto, this matters in a direct way. Low rates loosen liquidity and push investors toward riskier assets. High rates tighten it and pull money toward safer ground. A hiking cycle raises the cost of holding something like Bitcoin, which pays no interest while it sits in a wallet.

    Inflation and Jobs Data Set the Pace

    Inflation numbers don’t just move markets for a single trading session. They shift expectations around future rate decisions, and those expectations shape how funds position their crypto exposure for weeks or months afterwards. The Fed’s own statement pointed to inflation still running well above its 2% target, which was the core justification for the hike.

    Jobs data plays a similar role from a different angle. In August, US employers added 162,000 jobs, and unemployment held at 4.1%. A steady labor market gives the Fed room to keep policy tight if inflation stays sticky. Weaker numbers would pull in the opposite direction. Markets watch this release as closely as the rate decision itself.

    Dollar and Treasury Yields Quietly Set the Tone

    Bitcoin tends to weaken when the dollar strengthens, particularly when that strength reflects tighter financial conditions in the US. The link isn’t fixed or permanent, but it shows up often enough to matter.

    Treasury yields work through a similar mechanism. When government bonds pay more, they raise the bar for what a riskier asset needs to offer before it looks worth holding. That’s the opportunity cost at work: money doesn’t sit idle, but it goes wherever the return looks strongest relative to the risk.

    Oil Prices Add a Second Layer

    Oil doesn’t move Bitcoin on its own. It moves inflation first. Higher oil prices push inflation expectations up, which pushes the Fed toward holding rates or hiking further, which keeps liquidity tight, which then filters into how much capital flows into crypto. It’s a chain, not a straight line.

    Brent crude has traded above USD 100 a barrel through September, driven largely by supply disruptions tied to conflict in the Middle East. That pressure fed directly into the inflation numbers behind the Fed’s decision this month.

    Crypto Still Writes Its Own Chapters

    Macro conditions set the weather. What happens inside individual crypto assets is a separate story. Spot Bitcoin ETF flows, stablecoin liquidity, on-chain activity, protocol revenue, and regulatory moves all shape how a given token performs, sometimes independent of what the Fed just announced. A project with strong fundamentals can hold its ground even when the broader backdrop turns hostile, and a weak one can fall further even when conditions ease.

    Anyone tracking this space needs to watch several signals together rather than one in isolation. Fed decisions set the monetary tone. Inflation and jobs data shape what comes next. The dollar and Treasury yields reveal the state of financial conditions more broadly. Oil adds a layer of inflation risk that can arrive from outside the usual channels. And on the crypto side, ETF flows, stablecoin activity, and regulatory shifts explain why one asset can diverge sharply from the pack.

    Final Thought

    The next real test isn’t the September hike itself but whether the Fed follows through in December. A second increase would confirm a genuine shift in the rate cycle rather than a one-off correction, and that distinction will matter more to crypto positioning than any single headline number this year.

  • Column Launches Unified Stablecoin and Banking Platform for USDC and USDT Payments

    Column Launches Unified Stablecoin and Banking Platform for USDC and USDT Payments

    Column has introduced four financial infrastructure products that bring stablecoins, card issuing, global banking, and multicurrency accounts together on a single platform. Announced on September 16, the rollout enables fintech companies to use USDC and USDT alongside traditional bank accounts, cards, and payment networks.

    Column co-founder William Hockey said the launch completes a multi-year effort to build the company’s technology stack. In a company post, Hockey stated, “We have finally completed that build.” He added that the products are already handling billions of dollars for fintech companies, including Ramp, Brex, Bilt, Mercury, Slash, and Kapital.

    Stablecoin Services Integrated with Bank Payment Rails

    Column’s stablecoin service allows businesses to send and receive USDC and USDT while converting funds to and from US dollars at any time, 24/7. The company built the service directly into its banking core, so customers do not need to prefund balances with a separate provider before making a stablecoin transfer. The platform connects stablecoin activity with both US and international payment rails.

    For example, a business receiving USDC from Mongolia could convert the funds into dollars, split the money, send one portion to a US community bank through FedNow, and convert another into euros for a SWIFT payment. Column said the entire process can take place within seconds via its APIs and operates around the clock, including weekends and holidays.

    Card Issuing Combines Banking, Processing, and Capital

    Column also launched a card issuing product after building its own issuer processor. The service brings together the issuing bank, processing system, and capital into a single integration. Customers can use the platform to create credit, debit, prepaid, and stablecoin-backed card programs on the Visa and Mastercard networks. Column had previously sponsored card programs but now controls the processing layer, allowing it to manage card authorization and settlement within the same system that supports its banking products. This reduces the number of separate providers fintech companies need when launching card programs. The processor has direct connections to Visa and Mastercard and runs on the same core infrastructure used for Column’s other banking services.

    Global Banking and Multicurrency Accounts

    The third product extends Column’s account and card infrastructure to verified customers outside the United States. Businesses can offer US dollar or local currency accounts and cards to eligible users in other markets while using the same compliance tools and APIs used for domestic customers. Column did not publish a full list of supported countries, so availability depends on its banking and verification coverage.

    Column also introduced multicurrency accounts that allow customers to receive, hold, and send foreign currencies. Users can convert supported currencies to and from US dollars instantly and connect payments to international systems, including SEPA Instant. Supported currencies include euros, British pounds, and Canadian dollars, among others.

    Together, the four products enable fintech companies to connect stablecoins, bank accounts, cards, and foreign currency payments through one platform. Column said the services work together because they use the same underlying infrastructure. The company did not provide separate transaction volumes for each product, but Hockey noted the services are already moving billions of dollars for fintech customers.

  • Velocity Secures $10M Extension as Visa and Circle Join Its Stablecoin Infrastructure Push

    Velocity Secures $10M Extension as Visa and Circle Join Its Stablecoin Infrastructure Push

    Velocity, a London-based stablecoin payments startup, has added $10 million to its Series A round, bringing the total to $48 million. The extension was joined by Visa Ventures, Circle Ventures, and Ripple, alongside three other investors. The funding will support the company’s infrastructure for enterprise treasury, settlement, and liquidity operations using stablecoins.

    The latest raise comes just over two months after Velocity announced its initial $38 million Series A on July 14, led by Dragonfly and FirstMark, with participation from Ripple. The new extension adds Visa Ventures, Circle Ventures, Haun Ventures, Translink Capital, and Mirana Ventures to the cap table.

    Velocity builds systems that allow banks, acquirers, merchants, and payment providers to integrate stablecoin settlement, liquidity, and treasury operations without replacing existing payment infrastructure. The company aims to make money movement more continuous and reduce reliance on prefunding and settlement outside traditional banking hours.

    Visa has noted that stablecoins are playing an increasingly important role in moving value across its ecosystem. Rubail Birwadker of Visa stated that companies like Velocity can help expand stablecoin use for customers and partners. Velocity founder and CEO Eric Queathem emphasized that the new investors bring valuable insight as the company scales its stablecoin infrastructure.

    With the backing of Circle Ventures and Ripple, Velocity gains investors directly tied to regulated stablecoins, payments, and institutional finance. Translink Capital adds connections to corporate and institutional partners across Asia. The company plans to use the new capital to support issuers, acquirers, payment providers, financial institutions, and merchants worldwide, connecting stablecoins with existing banking, treasury, and settlement systems.

  • Visa Connects On-Chain Credit with Stablecoin Card Programs to Boost Working Capital Access

    Visa Connects On-Chain Credit with Stablecoin Card Programs to Boost Working Capital Access

    Visa has introduced an on-chain credit model that links VisaNet settlement data with blockchain lending infrastructure. The initiative aims to help stablecoin-linked card programs and fintechs obtain working capital more efficiently.

    By combining payment performance data with on-chain credit markets, Visa enables lenders to assess financing needs more accurately while supporting faster and more transparent capital access. The company’s On-Chain Analytics Dashboard reveals that over $694 billion in stablecoin-denominated loans have moved through on-chain lending protocols since 2020, though most activity has remained within crypto markets. Visa now seeks to connect these lending systems with businesses reliant on payment settlement and working capital.

    Visa currently supports more than 160 stablecoin-linked card programs across its network, with payment volume on these programs growing nearly 200% year-over-year. The company’s stablecoin settlement volume has surpassed a $20 billion annualized run rate—a more than fifteenfold increase from the previous year. However, emerging payment companies often struggle to secure funding during rapid growth, as traditional lenders typically require greater scale, longer operating histories, or manual underwriting. Visa believes blockchain-based lending can address these barriers when lenders receive trusted settlement data, with smart contracts automating funding, collateral management, and repayment.

    Visa highlighted its work with Credit Coop as an early example. Credit Coop provides working capital and settlement financing for stablecoin-linked card programs through smart contracts. With customer approval, the company combines Visa settlement data with on-chain transaction records to assess credit performance and support automated settlement financing. Since 2023, this model has supported over $2.5 billion in cumulative financed settlement volume with zero defaults. The infrastructure has processed more than 3,000 borrowing events and 9,000 repayment events on-chain, creating a programmable and auditable financing record.

    This initiative extends Visa’s broader stablecoin strategy, which includes the Visa Stablecoin Platform, stablecoin settlement, expanded card programs, and digital asset services for financial institutions. Visa views on-chain credit as another bridge between traditional payment systems and digital asset infrastructure, with potential applications across lending, treasury management, and settlement services.

  • Crypto Market Update: Ethereum Reserves at Multi-Year Low, Liquid Recovers 3,400 BTC, Visa Stablecoin Volume Soars

    Crypto Market Update: Ethereum Reserves at Multi-Year Low, Liquid Recovers 3,400 BTC, Visa Stablecoin Volume Soars

    Ethereum Exchange Reserves Plunge to Multi-Year Low

    Ethereum’s supply on cryptocurrency exchanges has fallen to a fresh multi-year low as the altcoin’s price continues to strengthen against Bitcoin. According to CryptoQuant data, the total supply of Ethereum on all exchanges stood at approximately 14.88 million ETH as of Tuesday, down from around 21.30 million ETH on July 1, 2025. This represents a net withdrawal of over 6.4 million ETH over the past 14 months. Reserves on Binance, the world’s largest exchange, have also slipped to about 3.74 million ETH, the lowest level in three months.

    Liquid Sidechain Recovers 3,400 BTC After Reserve Drain

    Bitcoin’s Liquid sidechain received 3,400 BTC back into its federation wallet on September 7, following a reserve drain incident. The partial recovery restores assets backing L-BTC, the sidechain’s Bitcoin-linked token, although withdrawal access remains disrupted and public bridge nodes are still listed as experiencing a major outage. The transaction was confirmed in Bitcoin block 965950, and Blockstream’s status page continued to report an active security incident as of September 8. The self-described white-hat hackers had previously left an on-chain message asking, “Is that ok?” before returning the funds.

    Visa’s Stablecoin Settlement Volume Exceeds $20 Billion Annualized

    Visa has announced that its stablecoin settlement volume has surpassed a $20 billion annualized run rate, representing a more than 15-fold increase year over year. More than 160 stablecoin-linked card programs are now live globally in Visa’s fiscal second quarter, with payment volume on those programs jumping nearly 200% compared to the previous year. Visa noted that this growth is creating a working-capital requirement for card issuers, who must fund daily settlement obligations before collecting payments from cardholders. Some early-stage programs require only a few million dollars and settle daily, making traditional warehouse facilities less economical.

    Ethereum’s Hegota Upgrade: FOCIL Gets Top Priority

    The Ethereum Foundation’s protocol team has published its first unified technical priority list for the upcoming Hegota upgrade, classifying 62 Ethereum Improvement Proposals (EIPs). Around 60 researchers and engineers across nine teams participated in the evaluation. Notably, EIP-7805, also known as FOCIL (Fork-Choice Inclusion Lists), received the only unanimous ‘S’ rating, the highest tier of commitment for mandatory deployment. FOCIL will allow users to guarantee the inclusion of valid transactions without relying on centralized block builders, mitigating censorship risks at the consensus layer. The Hegota upgrade also lays the groundwork for native private transaction integration and quantum resistance preparation by late 2029.

    Fractal Bitcoin Halving: Block Reward Reduced to 6.25 FB

    Fractal Bitcoin has successfully completed its first halving, reducing the block reward from 25 FB to 12.5 FB. The milestone, activated on September 8 via the FIP-102 consensus upgrade, also brought forward the network’s second halving, cutting the reward further to 6.25 FB. According to a post on X, network nodes and indexing services operated normally during the first 10 minutes after activation. The proposal does not increase FB’s total supply or create a separate supply for tokens distributed through Bitcoin.

    Frequently Asked Questions

    1. How much Ethereum is currently held on exchanges?
    CryptoQuant data places Ethereum exchange reserves at about 14.88 million ETH, down from roughly 21.30 million ETH in July 2025.

    2. How much Bitcoin did Liquid recover?
    Liquid received 3,400 BTC back into its federation wallet on September 7, partially restoring reserves behind L-BTC, though bridge services remain disrupted.

    3. How large is Visa’s stablecoin settlement business?
    Visa’s stablecoin settlement volume has surpassed a $20 billion annualized run rate, with over 160 stablecoin-linked card programs live globally.

    4. What is FOCIL in Ethereum’s Hegota upgrade?
    FOCIL, or EIP-7805, is designed to improve transaction inclusion and reduce reliance on centralized block builders. It received the only unanimous top-tier rating in the Hegota technical review.

    5. What happened to Fractal Bitcoin’s block reward?
    Fractal Bitcoin’s FIP-102 upgrade reduced the block reward from 25 FB to 12.5 FB and brought forward another reduction to 6.25 FB, without increasing the token’s total supply.

    Disclaimer: This article is for informational purposes only and does not constitute financial advice. Cryptocurrency investments are risky and may result in loss of capital. Always conduct your own research before making investment decisions.