Tag: digital payments

  • India Proposes MDR on UPI Transactions Above Rs 2,000: What It Means for Users

    India Proposes MDR on UPI Transactions Above Rs 2,000: What It Means for Users

    India’s Unified Payments Interface (UPI) has transformed digital payments by offering free transactions, but it could soon see a major policy shift. The central government has proposed amendments to the Payment and Settlement Systems Act, 2007, allowing banks and payment service providers to charge a Merchant Discount Rate (MDR) on select UPI transactions in the future.

    The final decision is pending, but the proposal suggests an MDR of 0.25% to 0.4% for merchant UPI transactions above Rs 2,000, while person-to-person (P2P) transfers would remain free. Government officials have not set a timeline for implementation.

    Impact on High-Value Transactions

    MDR is a fee merchants pay to banks and payment service providers for processing digital payments. Unlike UPI, credit and debit card payments already include MDR, typically borne by the merchant rather than the customer.

    According to official estimates, only 5% of all UPI transactions exceed the proposed Rs 2,000 threshold. However, these high-value transactions account for nearly 65% of total transaction value, presenting a significant revenue opportunity for the payments ecosystem.

    UPI continues to grow rapidly, facilitating approximately 23.7 billion transactions worth Rs 29.9 lakh crore, cementing its status as one of the world’s largest real-time payment networks.

    An official explained the limited consumer impact: “Even if implemented, 95% of transactions will not face the merchant discount rate. Besides, not all businesses will pass on the fees, which will be a small amount.”

    Long-Term Industry Prospects

    Industry executives believe allowing a limited MDR on high-value merchant transactions could create a more sustainable business model for payment companies. Since UPI currently generates little direct transaction revenue, banks and payment providers argue that additional income would fund technology upgrades, improve payment infrastructure, and support future innovation.

    According to Jefferies’ analysis, merchant UPI transactions above Rs 2,000 represent roughly 67% of merchant payment value despite accounting for only about 4% of transaction volume. The brokerage estimates that introducing MDR for this segment could generate Rs 5,000 crore to Rs 10,000 crore in annual revenue for the digital payments industry, potentially benefiting companies like Paytm and Pine Labs.

    Industry sources expect the government to introduce a cap on the maximum fee charged. As one source noted, “Unlike credit cards, there is no funding cost involved, so it makes sense to have a ceiling once the costs are covered.”

    For now, the proposed amendment only creates the legal framework to enable MDR. The government has not confirmed whether merchant charges will be introduced, what the final rates will be, or when such a policy could take effect. Until then, UPI transactions remain free under the existing system.

  • Moneyview Review: All-in-One Financial App for Loans, UPI, Credit Tracking & Investments

    Moneyview Review: All-in-One Financial App for Loans, UPI, Credit Tracking & Investments

    Overview

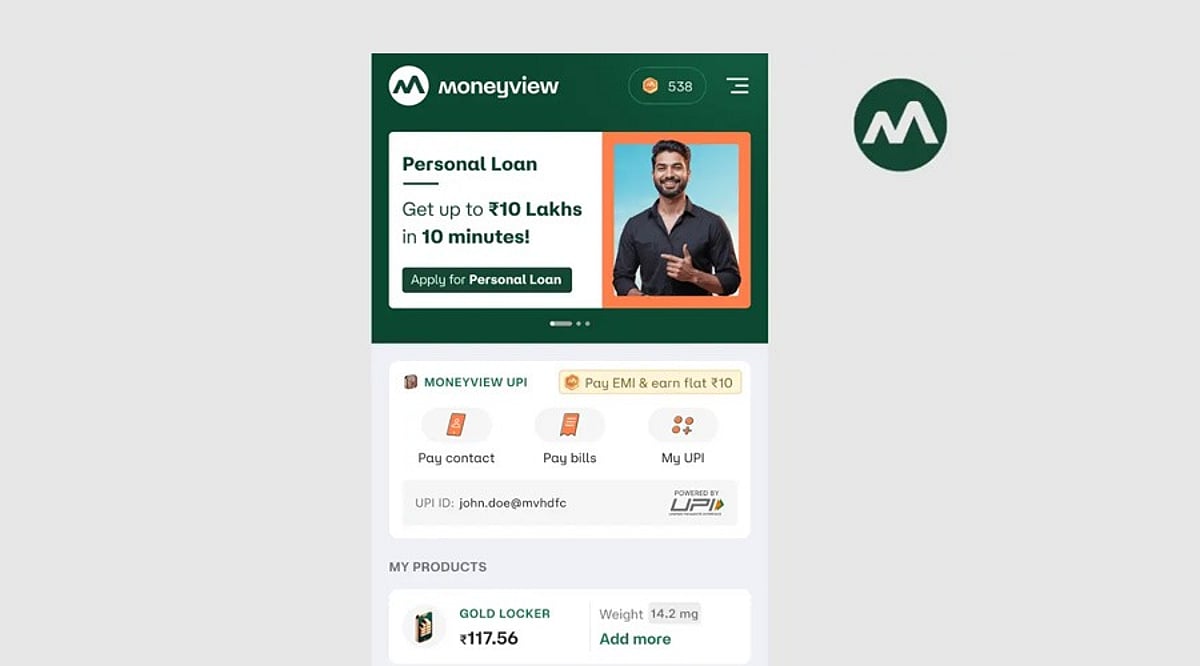
    Moneyview is a comprehensive financial services portal that allows users to manage loans, track credit scores, make UPI payments, open fixed deposits, invest in gold, and obtain insurance — all from a single mobile application. By leveraging AI-powered credit scoring, quick loan approvals, secure digital payments, and investment tools, it simplifies personal finance management.

    General Information

    • Founded: 2014
    • Platform Support: Web, Android, iOS
    • Download: Available on official app stores

    Key Features

    • Instant digital loans for individuals, businesses, and domestic needs.
    • AI-driven credit tracker providing free credit score reports.
    • Moneyview UPI with 256-bit encryption and ISO 27001:2022 certification.
    • All-in-one platform for gold investments, fixed deposits, insurance, and credit cards.

    Benefits

    • Integrated financial management for better control over money.
    • Quick loan approvals with minimal documentation.
    • Free credit score monitoring to aid financial planning.
    • Secure digital payments and investments through reliable instruments.
    • Savings, insurance, and loans accessible within a single app.

    Challenges

    • Loan eligibility depends on creditworthiness and partner lender policies.
    • Interest rates and terms vary based on customer profile.
    • Some financial products are limited to specific geographic regions.
    • Special bank accounts require additional verification.
    • Investment returns and insurance benefits are subject to partner terms.

    Subscription Information

    Moneyview is free to download and use for basic services like credit management, UPI payments, and EMI calculators. Financial products such as personal loans, home loans, business loans, credit cards, fixed deposits, car insurance, and gold investments come with varying eligibility criteria, partner terms, interest rates, and charges.

    Support Options

    • Help Center & Learning Resources: FAQs, loan guides, EMI calculators, security resources, product information, grievance redressal, and financial education materials.
    • Customer Support: Email, phone assistance, customer care, grievance redressal, and partner support for financial products.

    Conclusion

    Moneyview is a versatile digital banking platform that combines lending, savings, investments, insurance, and credit monitoring. Its AI-powered convenience, robust security, and diverse product range make it a strong choice for managing personal finances. Users seeking highly specialized banking services or global banking may want to explore alternative platforms.

  • How Sameer Nigam Built PhonePe Into India’s Digital Finance Powerhouse

    How Sameer Nigam Built PhonePe Into India’s Digital Finance Powerhouse

    As India surged ahead in adopting digital payments at an unprecedented scale, a handful of entrepreneurs worked quietly behind the scenes to drive that transformation. One key figure is Sameer Nigam, founder and CEO of PhonePe, who turned a fledgling idea into one of the nation’s biggest fintech success stories.

    From a simple payment app to a comprehensive digital solution for millions of Indian consumers, PhonePe’s evolution reflects Nigam’s unwavering vision. His journey from engineer to entrepreneur is a blend of technical expertise and business acumen. With a computer science degree from the University of Mumbai and the University of Arizona, plus an MBA from Wharton, Nigam honed his skills at Shopzilla in the US before co-founding Mime360, a digital content distribution company later acquired by Flipkart. That acquisition introduced him to India’s booming e-commerce scene, where he held leadership roles in engineering and marketing.

    During those years, as India underwent digital transformation, Nigam spotted a critical gap in payment systems. In 2015, he co-founded PhonePe with Rahul Chari and Burzin Engineer. At a time when the Unified Payments Interface (UPI) was still nascent, the founders bet on its future rather than building a digital wallet. That bet paid off spectacularly. The 2016 demonetization campaign accelerated India’s shift to digital payments, and PhonePe surged ahead with its intuitive interface, fast bank integration, and easy onboarding for first-time digital users.

    Today, PhonePe is far more than a payments app. It offers insurance, mutual funds, lending, stock investments, merchant solutions, and app discovery. Nigam’s leadership philosophy centers on trust. Instead of aggressive marketing, he focused on building reliable technology capable of handling massive transaction volumes without hiccups. This engineering-first approach helped PhonePe thrive within India’s rapidly evolving digital payment ecosystem.

    Nigam also understood India’s diverse consumer base. By simplifying services and offering them in multiple languages, PhonePe reached users in metropolitan, suburban, and rural areas. For many Indians, the app was their first experience with digital financial services.

    Beyond payments, Nigam envisioned a complete digital ecosystem. Under his guidance, PhonePe expanded into wealth management, insurance distribution, lending, and merchant services. The launch of the Indus Appstore marked its entry into digital commerce, signaling ambitions far beyond fintech. This diversification is central to Nigam’s strategy of building a multi-product platform.

    Colleagues describe Nigam as a leader who prioritizes product-centricity and experimentation. His engineering mindset fosters a culture of innovation. Rather than chasing media hype, he lets the company’s products and performance speak for themselves, earning him recognition as a key fintech opinion-maker in India.

    As India moves deeper into the digital era, Nigam’s influence extends beyond PhonePe’s growth metrics. He has made digital payments a routine practice for small businesses and consumers alike. The future of India’s fintech industry may involve artificial intelligence, embedded finance, digital commerce, and greater financial accessibility. Given PhonePe’s trajectory, Nigam intends to be at the forefront of that evolution.

    This is not just an entrepreneurial success story; it is a story of reshaping an entire nation’s relationship with finance. Sameer Nigam has cemented his place as one of the architects of India’s digital financial revolution.

  • India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

    India’s Top 10 Fintech Companies Driving Financial Inclusion in 2026

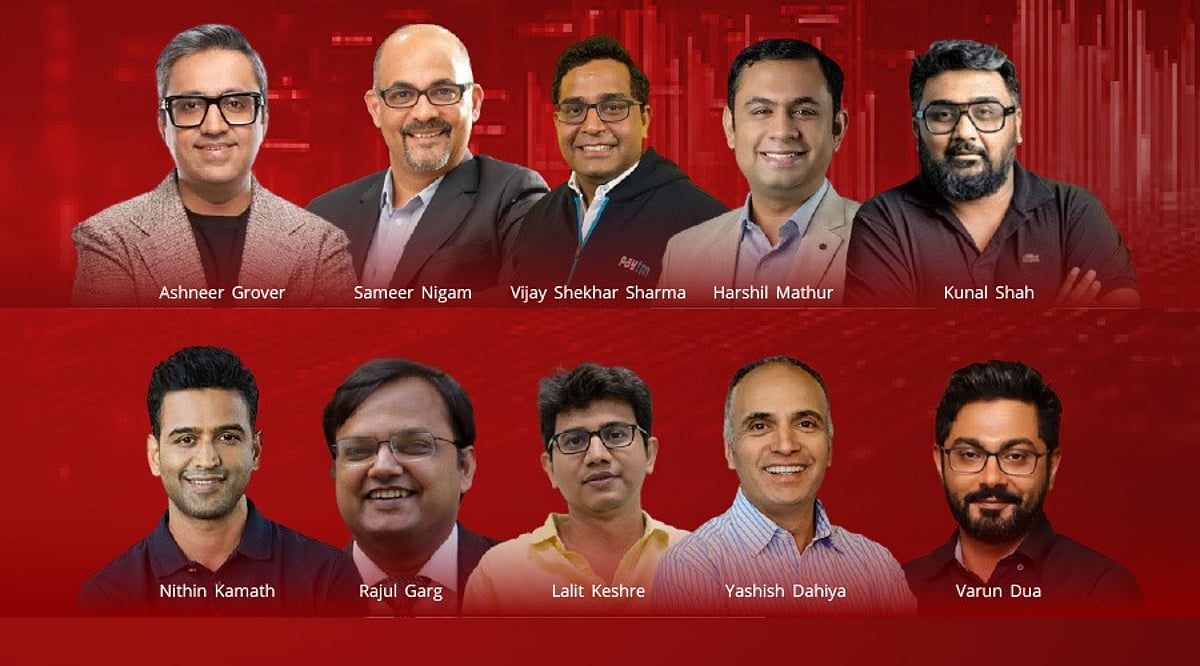
    India’s fintech revolution has transformed digital finance through UPI, AI, and mobile-first innovation. From payments and investing to insurance and lending, the country’s top 10 fintech companies are driving financial inclusion, serving millions of users, and reshaping the future of banking.

    Overview

    India processes over 13 billion UPI transactions monthly, with the fintech market expected to exceed $150 billion by 2025, highlighting its rapid digital finance growth. The top 10 fintech firms lead payments, investing, insurance, and lending, serving millions of users while reshaping India’s financial ecosystem. AI, UPI, Aadhaar, and the Account Aggregator framework power these platforms, enabling faster services, smarter lending, and greater financial inclusion across India.

    The Leaders Redefining India’s Financial Landscape

    PhonePe

    PhonePe stands as India’s largest digital payments platform. Founded in 2015 by Sameer Nigam, Rahul Chari, and Burzin Engineer, it commands the UPI ecosystem with over 600 million registered users. The company’s revenue crossed ₹5,000 crore in FY24. Its platform spans payments, insurance, digital gold, and mutual funds. An IPO targeting a valuation between $9 billion and $10.5 billion remains on the horizon.

    Paytm

    Vijay Shekhar Sharma founded Paytm in 2000, making it one of India’s oldest fintech institutions. It began as a mobile recharge tool and expanded into wallets, merchant payments, lending, and wealth management. Annual revenues hover above ₹7,000 crore. Despite regulatory headwinds in recent years, Paytm holds a deep merchant network that keeps it embedded in India’s payment infrastructure.

    Razorpay

    Harshil Mathur and Shashank Kumar launched Razorpay in 2014 to solve a clear gap: businesses needed a reliable, developer-friendly payment gateway. The company now processes over $150 billion in annual payment volume and carries a valuation of approximately $7.5 billion. Its product suite covers payment gateways, business banking, payroll automation, and lending products used by thousands of Indian startups and enterprises.

    CRED

    Kunal Shah founded CRED in 2018 around a single insight: financially responsible people deserved better rewards. The platform targets high-credit-score users, offering reward points for credit card bill payments and expanding into personal loans, rent payments, and vehicle services. CRED’s valuation stands at around $6.4 billion, with estimated revenues crossing ₹2,000 crore in FY24.

    Zerodha

    Nithin Kamath and Nikhil Kamath built Zerodha in 2010 to lower the cost of investing. Discount brokerage and a clean trading interface on the Kite platform democratized equity markets for millions of retail investors. Revenue crossed ₹6,000 crore, and the company’s valuation sits between $3 billion and $4 billion. Zerodha remains profitable without external funding, which sets it apart in a sector that often burns capital for growth.

    Groww

    Lalit Keshre, Harsh Jain, Neeraj Singh, and Ishan Bansal founded Groww in 2016 to make investing simple for first-time users. The platform covers mutual funds, stocks, ETFs, IPOs, and fixed deposits under one roof. Its clean design and financial literacy focus helped it attract millions of young investors. Groww became a unicorn and continues expanding its wealth-tech offerings across India.

    Pine Labs

    Pine Labs traces its roots to 1998, making it one of the sector’s most seasoned players. Founded by Rajul Garg, the company built a merchant payment ecosystem spanning over one million touchpoints. Its POS machines and digital finance products serve retail chains and small merchants alike. Valuations range between $5 billion and $6 billion. Pine Labs bridges the offline and online commerce divide at meaningful scale.

    PB Fintech

    Yashish Dahiya founded PB Fintech in 2008, and it operates two major platforms: Policybazaar and Paisabazaar. Policybazaar became India’s largest online insurance marketplace, while Paisabazaar helps consumers compare loans and credit products. The company reported revenue growth of 33% year-on-year in recent results. Its market capitalization ranges between $4 billion and $5 billion.

    BharatPe

    Ashneer Grover and Shashvat Nakrani launched BharatPe in 2018 to serve a neglected segment: small merchants. The company introduced zero-fee UPI QR codes for shopkeepers and followed up with merchant loans and POS solutions. Its revenue surpassed ₹1,000 crore, and its merchant network now covers millions of micro and small retailers. BharatPe remains central to financial access for India’s informal business sector.

    ACKO

    Varun Dua founded ACKO in 2016 to reinvent insurance distribution. Traditional agents and lengthy paperwork gave way to a mobile-first platform where users buy, renew, and claim policies entirely online. ACKO offers motor, health, and travel insurance with faster claim settlements. Its digital-first model has attracted a growing customer base, and the company stands among India’s most prominent insurtech names.

    What These Leaders Share

    Several common threads run through all ten companies on this list: each built its product around mobile-first access, reaching users traditional banks could not. All ten leverage UPI, Aadhaar, or the Account Aggregator framework as foundational infrastructure. AI now powers credit scoring, fraud detection, and customer support across most platforms. Financial inclusion remains a stated goal, whether the customer is a salaried professional or a street-side vendor.

    Final Words

    India’s top fintech leaders did not simply build successful businesses. They rewired how a nation of 1.4 billion people manages money. Each company on this list solved a specific friction point, whether that was payment acceptance for merchants, affordable brokerage for retail investors, or instant insurance for urban professionals. The result is a financial ecosystem that is faster, cheaper, and more accessible than it was even five years ago. The next phase will demand more: regulatory clarity, sustainable unit economics, and deeper penetration into rural markets. The foundations, however, are already strong. India’s fintech sector enters the second half of this decade not as a promising experiment but as a proven engine of economic transformation. The names above have earned their place at the forefront. Now comes the harder task of staying there.

  • India’s Fintech Revolution: Unlocking a Trillion-Dollar Market Opportunity

    India’s Fintech Revolution: Unlocking a Trillion-Dollar Market Opportunity

    India’s financial landscape has undergone a remarkable transformation over the past decade. What began as a push toward digital payments has evolved into a thriving fintech ecosystem that is reshaping how millions save, borrow, invest, and transact daily.

    Traditional banking with its long, tedious paper forms has given way to financial services accessible at the tap of a smartphone. The country’s robust digital public infrastructure, expanding internet access, and a young, tech-savvy population have created fertile ground for fintech innovation.

    Today, India boasts one of the world’s largest digital payment ecosystems, alongside a growing network of startups building tools for lending, insurance, wealth management, and embedded finance. With artificial intelligence (AI) emerging as a new layer of innovation, many industry experts believe India’s fintech sector is entering its next growth phase — one that could eventually make it one of the country’s trillion-dollar industries.

    UPI Became a Game Changer

    The launch of the Unified Payments Interface (UPI) in 2016, created by the National Payments Corporation of India (NPCI), gave a huge boost to the fintech revolution. UPI enables instant payments from one bank account to another via mobile phones.

    Consumer behavior shifted dramatically. QR codes are now ubiquitous across the country — from roadside tea stalls and vegetable vendors to shopping malls and multinational corporations. Digital payments are no longer confined to urban users; they have become accessible in smaller towns and rural areas.

    The success of UPI opened the door for further fintech innovations. Startups began crafting offerings for lending, saving, investing, and insurance based on users’ digital payment histories.

    Booming Fintech Ecosystem

    India’s fintech applications extend far beyond payments. Fintech startups now operate across digital lending, wealth management, insurtech, personal finance, embedded banking, and cross-border payments.

    The large number of unbanked individuals and micro, small, and medium enterprises (MSMEs) has created immense opportunities for fintech companies to fill gaps left by traditional banking. These startups help individuals access banking services through alternative credit scoring, paperless onboarding, and quick loan approvals — even for those with low or no credit ratings.

    Digital lending has become a reliable source of working capital for small enterprises. Meanwhile, investment fintech platforms have opened up mutual funds, shares, and government securities to novice investors.

    AI Powering the Next Wave of Innovation

    Artificial intelligence is emerging as the backbone of fintech innovation. Organizations are using AI algorithms to detect fraud, automate customer service, and improve credit underwriting.

    Banks and fintech companies leverage AI to enhance compliance processes, monitor suspicious transactions, and reduce operational expenses. Loan approvals are faster, and risk assessment improves through the use of alternative data sources.

    As digital transactions increase, AI will be crucial for handling larger volumes securely and conveniently.

    Why Investors Remain Optimistic

    While global venture capital investment has experienced ups and downs, India continues to attract strong investment in fintech. This is not due to cyclical trends but to structural factors.

    The country’s growing digital economy, widespread smartphone usage, supportive government policies, increased internet penetration, and the world’s largest real-time payment system collectively create a solid foundation for future growth. Financial inclusion presents significant opportunities, as many Indians enter the formal financial system for the first time.

    Challenges on the Road Ahead

    Rapid growth is not without risks. Cybersecurity threats, digital fraud, and data privacy concerns have heightened focus on consumer safety. Regulations from the Reserve Bank of India are tightening, especially regarding digital lending and payment processes.

    Profitability remains an issue for many fintech companies operating with zero-cost or heavily subsidized products. Ultimately, consumer trust will be the deciding factor.

    The Trillion-Dollar Opportunity

    India’s fintech evolution extends beyond replacing cash with digital payments. It involves building a complete financial ecosystem where payment systems, lending services, investment platforms, insurance schemes, and commerce increasingly integrate across digital platforms.

    The coming decade will see increased partnerships among banks, fintech companies, regulators, and technology providers. Artificial intelligence, digital public infrastructure, and supportive policies will play pivotal roles in accelerating this process.

    Given the current momentum, India’s fintech sector could become one of the most notable success stories of the Indian economy — contributing to financial inclusion, capital generation, and the transformation of banking for over a billion people.

  • How Vijay Shekhar Sharma Bet on a Cashless India and Won

    How Vijay Shekhar Sharma Bet on a Cashless India and Won

    Every day, millions of Indians scan a QR code without a second thought. From roadside tea stalls and neighborhood kirana stores to taxi rides and hospital bills, digital payments have become part of everyday life. Long before that familiar QR sticker appeared across the country, Vijay Shekhar Sharma was betting that India’s relationship with cash would eventually change.

    From a Hindi-Medium Classroom to Big Dreams

    Sharma grew up in Harduaganj, a small town in Uttar Pradesh, in a Hindi-medium household where English was not spoken. When he entered engineering college in Delhi at fifteen, the coursework was not what slowed him down—the language was. Textbooks, lectures, and classroom conversations all arrived in a language he was still learning to read fluently, let alone speak with confidence. He has often said that English, not mathematics or physics, was the steepest climb of his early life. That struggle shaped how he approached everything afterward. Sharma taught himself English by reading everything he could find, and he carried the same self-taught instinct into technology.

    Building One97 Before Smartphones Took Over

    While still in college, he built indiasite.net, an early web content venture. He sold it two years later for a million dollars, a deal that gave him both confidence and capital for what came next. In 2000, he started One97 Communications, offering mobile content and services at a time when most of India had barely heard of the internet, let alone owned a smartphone. The dot-com crash tested that first venture severely. One97 survived by pivoting and adapting, a pattern Sharma would repeat throughout his career.

    The Bet That Became Paytm

    Those years also changed how Sharma viewed technology. While many internet companies were still thinking in terms of websites, he had become convinced that India’s next computing platform would be the mobile phone. Paytm began modestly, as a platform for prepaid mobile recharges, but the ambition behind it was never modest. Sharma wanted to turn the phone into a wallet—one that could hold money the way a physical wallet did and move it as easily as a text message.

    How Demonetisation Accelerated Paytm’s Growth

    For years, that vision grew steadily rather than explosively. Then, in November 2016, the government withdrew high-value currency notes from circulation overnight. Cash, the backbone of Indian commerce, disappeared from circulation almost instantly. Demonetisation did not create Sharma’s vision; it accelerated one that already existed. While demonetisation drove a surge in adoption, Paytm had already spent years building its payments infrastructure, merchant network, and consumer base before the policy took effect. Sharma became the public face of a shift the entire country was living through at once.

    The IPO That Changed the Conversation

    Growth on that scale eventually demands a different kind of scrutiny. In 2021, Paytm’s parent company, One97 Communications, went public in what was then India’s largest IPO, raising close to 18,300 crore rupees. The transition from startup darling to publicly listed company fundamentally changed the questions investors asked. Growth alone was no longer enough. Paytm’s listing was followed by a sharp decline in its share price as public investors questioned when, or if, the company would turn a profit. The optimism that had carried Paytm through a decade of private funding rounds met a far more skeptical audience.

    Regulatory Challenges and Rebuilding Trust

    If the IPO tested Paytm’s financial discipline, what followed tested its governance. The Reserve Bank of India moved against Paytm Payments Bank in 2024, citing persistent compliance concerns and ultimately restricting most of its operations. The action marked one of the biggest regulatory setbacks in Paytm’s history. Beyond the operational impact, it raised broader questions about governance, compliance, and how quickly fintech companies could scale while still meeting banking regulations. It forced Sharma into a period of restructuring and rebuilding, separating the payments bank from the broader Paytm ecosystem and working to reassure both regulators and customers that the business could operate within tighter compliance boundaries. Public markets demanded profitability. Regulators demanded stronger governance. Both pressures arrived within a few years of each other, and both forced Sharma to prove that Paytm could mature into an institution, not just remain a fast-growing startup.

    The Legacy of Vijay Shekhar Sharma

    Vijay Shekhar Sharma’s story mirrors the evolution of India’s digital economy itself. It began with a language barrier in a small town, accelerated through bold bets on mobile technology, and was tested by the realities of public markets and regulation. Sharma has often credited his upbringing for giving him the discipline to keep rebuilding after setbacks—a quality that has become as important as his willingness to take risks. His journey suggests that building a company at a national scale is less about getting a single decision right than about repeatedly adapting as technology, markets, and institutions evolve.

  • How Harshil Mathur and Razorpay Revolutionized India’s Digital Payments Ecosystem

    How Harshil Mathur and Razorpay Revolutionized India’s Digital Payments Ecosystem

    When Harshil Mathur and Shashank Kumar launched Razorpay in 2014, India’s online payment infrastructure was a mess of failed transactions, clunky integrations, and limited options for businesses trying to accept money digitally. Twelve years later, Razorpay processes over $180 billion in annualized total payment volume, has onboarded more than 12 million merchants, and filed a confidential DRHP with SEBI in June 2026, targeting a public listing valued at $5 to $6 billion. For Mathur, the journey from wireline field engineer to CEO of one of India’s most consequential fintech companies is anything but accidental.

    From Jaipur to IIT Roorkee to a Bold Bet

    Born in 1991 into a middle-class family in Jaipur, Rajasthan, Mathur developed an early fascination with technology and coding. He completed a degree in metallurgical engineering from IIT Roorkee in 2013 and joined Schlumberger as a wireline field engineer, a technically intensive role that lasted just eight months before the pull toward building something of his own won out. In December 2014, he co-founded Razorpay with Kumar around a straightforward insight: India’s businesses desperately needed a clean, developer-friendly API to accept online payments, and nothing available delivered that reliably.

    Y Combinator and the Developer-First Growth Engine

    In 2015, Razorpay got into Y Combinator’s Winter batch, one of the world’s most selective startup programs. The YC period sharpened the company’s product thinking and opened the door to early investors. Early growth was built almost entirely on developer trust; Razorpay’s clean API documentation and reliable integration made it the default payment gateway for startups, SMEs, and eventually larger enterprises. By 2020, the company had crossed the $1 billion unicorn mark. By December 2021, a $375 million Series F round valued it at $7.5 billion, backed by Peak XV Partners, Tiger Global, Ribbit Capital, Lightspeed, and Singapore’s GIC.

    Building Beyond Payments

    Mathur’s strategic ambition for Razorpay was never limited to a payment gateway. Under his leadership, the company expanded into RazorpayX, a neobanking platform now serving over 40,000 businesses with payroll, corporate cards, and connected banking; Razorpay Capital for merchant credit; and Magic Checkout, a one-click product reportedly reducing cart abandonment by 22%. In January 2026, Razorpay received RBI’s payment aggregator cross-border license, enabling transactions across 130-plus currencies in over 180 countries, and the company has established operations in Singapore and Malaysia.

    The IPO Moment

    Razorpay’s planned stock market debut is the most significant milestone on the horizon. The company filed a confidential DRHP with SEBI on June 12, 2026, targeting Rs 5,000 to Rs 6,000 crore through fresh shares and an offer for sale, with Axis Capital, Kotak Mahindra Capital, JPMorgan, and Citi appointed as lead managers. The targeted $5 to $6 billion IPO valuation is a markdown from the $7.5 billion 2021 peak, reflecting broader compression in fintech valuations and a public market that now demands profitability alongside growth. Razorpay’s FY25 revenue grew 65% to Rs 3,783 crore, though a net loss of Rs 1,209 crore, driven by ESOP costs and one-time reverse-flip tax liabilities from its 2025 domicile shift back to India, is a narrative that Mathur will need to tell convincingly to public-market investors.

    The Leader Behind the Company

    Mathur’s leadership style is widely described as product-first, technically grounded, and collaborative. He has consistently credited the broader Razorpay team and his co-founder rather than positioning himself as the singular force behind the company’s rise. He is also an active angel investor with a portfolio of over 22 companies, has been recognized on the Forbes 30 Under 30 Asia list, and has been a vocal voice in India’s startup community on digital policy issues. What makes his story particularly resonant is the consistency of the original thesis: building reliable, developer-first financial infrastructure for Indian businesses was not a fashionable idea in 2014. A decade on, it has become the foundation of how a significant share of India’s digital economy moves money.

    Why This Matters

    India’s digital economy depends on reliable payment infrastructure, and entrepreneurs like Harshil Mathur have played a significant role in building it. His journey demonstrates how solving a fundamental business problem with technology can create lasting impact, inspire future founders, and accelerate innovation across an entire industry.

  • Emirates Integrates Crypto.com Pay for UAE Flight Bookings, Supporting Dubai’s Cashless Vision

    Emirates Integrates Crypto.com Pay for UAE Flight Bookings, Supporting Dubai’s Cashless Vision

    Emirates has launched Crypto.com Pay for eligible UAE residents booking flights through its website and mobile app. Customers can now pay from a crypto wallet, while every ticket settles in Emirati dirham. The service went live in late July 2026 and currently excludes other currency markets.

    Crypto Payments Enter Emirates Checkout

    The mobile process starts when customers choose Crypto.com Pay during checkout. The Emirates app then redirects them to the Crypto.com app, where they approve the payment from their available wallet balance. After approval, customers return to the Emirates app and receive their booking confirmation and electronic ticket. The process requires an existing Crypto.com account, but it removes the need for cards or bank transfers.

    Desktop users follow a similar route through emirates.com. They scan a QR code at checkout, approve the transaction inside the Crypto.com app, and receive confirmation on the Emirates website. The airline has not identified the cryptocurrencies customers can use. Still, payments come directly from balances held inside eligible Crypto.com wallets.

    Emirates said the service targets younger customers who manage payments and other financial activities through smartphones. Access remains limited to eligible UAE residents during the first stage.

    Regulated Dubai Entity Handles Settlement

    Crypto.com processes the payments through Foris DAX Middle East FZE, its Dubai entity. The company holds a Stored Value Facilities license from the Central Bank of the United Arab Emirates. The central bank granted the authorization in May 2026. Crypto.com then became the first Virtual Asset Service Provider in the UAE to secure this type of license.

    The framework covers stored balances that customers deposit before using them for payments. Therefore, Crypto.com manages the payment service, while Emirates avoids operating as a crypto service provider. Emirates still prices and settles each ticket in dirhams. Crypto.com converts the customer’s crypto balance before funds reach the airline, so Emirates needs no internal crypto payment infrastructure.

    Crypto.com uses a similar system for payments to Dubai government bodies. Under that arrangement, the provider converts digital assets into dirhams before transferring funds to government accounts.

    Launch Supports Dubai Cashless Strategy

    Emirates and Crypto.com first outlined the integration through a memorandum of understanding in July 2025. The companies completed the regulated payment launch roughly one year later. The service also supports Dubai’s Cashless Strategy, which targets about 90% digital transactions across government and private-sector payments by the end of 2026. The program forms part of the D33 Economic Agenda.

    What makes this launch different from earlier airline crypto payment options? Emirates embeds the service directly into its platforms, while a central-bank-regulated provider manages payment processing and dirham settlement. airBaltic first accepted Bitcoin in 2014 and later added other digital assets through BitPay. Travala.com also accepts more than 90 cryptocurrencies across over 600 connected airlines.

    However, Travala.com acts as an intermediary between customers and airlines. Emirates instead keeps the booking contract directly between the passenger and the carrier. For now, eligible UAE residents can use Crypto.com Pay for dirham bookings. Emirates has announced no expansion into other markets or currencies.

    Conclusion

    Emirates now offers Crypto.com Pay to eligible UAE residents through its website and app. Crypto.com handles conversion and dirham settlement under its central bank license. The service expands regulated crypto payments into direct airline bookings while access remains limited to the UAE market.

  • How Digital Payments Are Revolutionizing Small Business Growth Beyond Lending

    How Digital Payments Are Revolutionizing Small Business Growth Beyond Lending

    Digital payments have evolved far beyond simple transaction processing. Today, they serve as a powerful engine for small businesses, enabling them to streamline operations, attract a broader customer base, and accelerate growth.

    In India, systems like UPI and Aadhaar-enabled banking now power a significant share of MSME payments. These technologies make transactions faster and more secure, while reducing the reliance on cash.

    Faster digital checkouts cut down waiting times, eliminate the need for cash handling, and automatically record every transaction for easier accounting. This operational efficiency allows business owners to focus more on strategy and less on manual tasks.

    Every digital payment generates valuable data. Business owners can track customer trends, identify peak sales hours, and manage inventory more effectively, leading to smarter, data-driven decisions.

    Accepting digital payments also opens doors to online shoppers, delivery platforms, and customers outside the local area. This expanded reach helps small businesses compete in a larger marketplace.

    Security is another key benefit. AI-powered fraud detection, real-time monitoring, and secure payment systems protect businesses and build trust with customers. Embedded payments within apps, POS systems, and digital platforms simplify checkout and improve cash flow through faster settlements.

    Beyond immediate transactions, digital payments support long-term business growth. Better recordkeeping, improved tax planning, customer rewards programs, and easier access to future credit are all made possible by a robust digital payment infrastructure.

    However, challenges remain. Cybersecurity threats, transaction fees, system outages, staff training requirements, and protecting customer data are ongoing concerns that small businesses must navigate.

  • Top Fintech Stocks to Watch in July 2026: Global and Indian Picks for Digital Payments and Lending

    Top Fintech Stocks to Watch in July 2026: Global and Indian Picks for Digital Payments and Lending

    The fintech sector continues to surge, offering investors a mix of high-growth opportunities and varied risk profiles. From global payments leaders to Indian digital-finance champions, these seven stocks provide exposure to digital payments, lending, cross-border finance, and financial technology innovation.

    PayPal (PYPL, US)

    PayPal stock trades at $56.08 with a market cap of $49.53 billion, a P/E ratio of 10.64, and a dividend yield of 0.74%. Growth drivers include rising digital payments, merchant services, and new products like cryptocurrency and buy now, pay later (BNPL). The stock is down 27.72% over the past year after peaking in 2025, with a 52-week range of $38.46 to $79.50.

    Risks: Intensifying competition (Visa, fintechs), margin pressure, regulatory scrutiny.
    Thesis: PayPal’s entrenched network and transition to AI-driven merchant tools and crypto features could revive growth, though near-term execution and macro uncertainty temper the outlook.

    Block, Inc. (SQ, US)

    Block trades at $77.15 with a market cap of $45.92 billion, a P/E of 63.33, and average daily volume of 4.9 million shares. Its 52-week range is $48.21 to $84.08. Key drivers are Cash App (payments, Bitcoin) and SMB payment terminals (Afterpay BNPL). Analysts give a Positive/Buy rating.

    Risks: High valuation, crypto volatility, consumer spending slowdown.
    Thesis: Block’s diversified fintech ecosystem (POS, digital bank products, crypto) drives strong revenue growth. Prudent reinvestment and expansion in developing markets and crypto can reward long-term holders despite short-term volatility.

    Adyen (ADYEY, Netherlands)

    Adyen’s market cap is $28.55 billion, stock at $9.01. The company powers payments for global merchants (Netflix, Shopify) and expands in Asia. FY25 net revenue grew 17%, but market cap dropped 50% YoY amid margin pressure. P/E is 23.7, and analysts rate it Buy on 30%+ long-term EPS growth.

    Risks: E-commerce slowdown, pricing competition, FX swings.
    Thesis: Adyen’s unified platform and global reach support above-market growth. Despite headwinds, its conservative profitability and digital commerce migration make it attractive.

    Wise plc (WISE, UK)

    Wise market cap is £9.28 billion, FY25 revenue £1.212 billion, profit before tax £565 million. It has 10 million+ users for low-cost cross-border transfers and multi-currency accounts. P/E is 24.8. Analysts rate it Buy.

    Risks: FX risk, competition from banks and fintechs, economic downturn cutting remittances.
    Thesis: Wise dominates peer-to-peer currency transfers with a trusted brand and asset-light model. As cross-border payments grow, Wise should deliver steady profit growth.

    One97 Communications (PAYTM, India)

    Market cap: Rs. 82,213 crore ($9.8 billion), FY25 revenue Rs. 6,494 crore (+5.7% YoY). Turned profitable in FY26 (est. profit $5.4 billion). Paytm’s digital payments, financial services (UPI, wealth, lending), and commerce platforms fuel India growth. Q1 FY26 revenue rose 28% YoY to Rs. 2,410 crore. Analysts raised target to Rs. 1,476.

    Risks: Regulatory changes, intense competition (Google Pay, banks), profitability execution.
    Thesis: India’s leading fintech super-app with immense scale. Government push for digital finance and expansion into banking/loans should drive outsized growth. Suits high-growth, India-focused investors.

    Bajaj Finance (BAJFINANCE, India)

    Market cap: Rs. 6,30,565 crore, FY25 net profit Rs. 16,779 crore, AUM Rs. 4.17 lakh crore. Bajaj Finance offers consumer loans, BNPL, insurance, and app-based lending. Stock up 10% in one year, near fair value per analysts. P/E is 32.6.

    Risks: Rising credit defaults (auto, MSME loans), higher borrowing costs, regulatory lending limits.
    Thesis: Blends fintech innovation (BFL app) with prudent risk management. Should deliver 20%+ annual growth, strong franchise and capital make it a core long-term holding in India.

    MercadoLibre (MELI, Argentina/US)

    Market cap: $91.2 billion, FY25 net revenues over $30 billion (Q126: $8.8 billion, +49% YoY). Net income $1.99 billion (2025 estimate). Dominates Latin American e-commerce and fintech (MercadoPago payments, credit). Trades at 46x earnings. Analysts: Moderate Buy.

    Risks: Latin America economic instability, high valuation, rising competition.
    Thesis: With 600M+ addressable users and increasing fintech penetration, MercadoLibre is uniquely positioned. Diversified model (commerce + fintech) should generate strong double-digit growth. High-risk, high-reward.

    Frequently Asked Questions

    1. Which fintech stocks are included in this July 2026 list? The seven companies are PayPal, Block, Adyen, Wise, MercadoLibre, One97 Communications (Paytm), and Bajaj Finance.
    2. Which stock may suit value-focused fintech investors? PayPal’s P/E of 10.64 is considerably lower than peers, though its valuation reflects competition and margin concerns.
    3. Which two Indian fintech stocks are covered? One97 Communications (Paytm) and Bajaj Finance — the former high-growth digital ecosystem, the latter established consumer lending.
    4. Which stock carries the highest growth and valuation risk? Block and MercadoLibre, due to valuation and execution risks, crypto volatility, consumer spending, and economic instability.
    5. Are fintech stocks suitable for conservative investors? Fintech can be volatile. Conservative investors may prefer Bajaj Finance or PayPal over speculative high-growth names.

    Disclaimer: This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before investing.