Tag: Financial Services

  • Wealth Management Firms Chase AI Adoption, Yet Most Remain Unprepared

    Wealth Management Firms Chase AI Adoption, Yet Most Remain Unprepared

    A recent HCLTech study highlights a significant disconnect in the wealth management industry: while nearly all leadership teams are pursuing artificial intelligence, very few have built the systems needed to truly transform their operations. The report, titled Hidden In Pl(AI)n Sight, suggests that firms recognize the need for change but are still far from executing it.

    AI Ambitions Versus Agentic Readiness

    According to the study, 98% of wealth management leadership teams are actively advancing an AI agenda. However, only slightly more than 7% are developing agentic AI capabilities — systems that can independently perform a sequence of tasks toward a defined goal, rather than simply responding to individual prompts.

    While 84% of respondents acknowledged that their operating models require a fundamental redesign to fully leverage AI, fewer than 10% are prepared for such a transition. These figures indicate that although firms understand the magnitude of the work ahead, most are still in the early stages of implementation.

    The research was conducted using a synthetic methodology. HCLTech, in collaboration with Evidenza, created 1,066 AI personas modeled on senior wealth management decision-makers across 17 markets. Industry practitioners, researchers, and subject experts helped design and validate the approach, meaning the percentages reflect modeled personas rather than a traditional survey of executives.

    Funding Efficiency While Ignoring Revenue Impact

    The report identifies three critical gaps between AI plans and business outcomes. First, firms tend to fund projects aimed at operational efficiency even when they acknowledge the need for broader change. Second, technology spending often outpaces investment in proprietary client data and insights. Third, measurement remains a weak point: companies track AI adoption but rarely measure whether these initiatives generate revenue or improve client value.

    Although 84% of leaders favor a major redesign of their operating models, only 12% measure the new revenue generated by these changes. Srinivasan Seshadri, HCLTech’s chief growth officer and global head of financial services, emphasized that clarity is essential. “The industry doesn’t have an investment problem. It has a choice problem,” he said.

    Executives in the study placed greater importance on client-derived data and behavioral insights than on cloud platforms, technology infrastructure, or AI partnerships as sources of competitive advantage. Nearly 80% also expect future leaders to combine AI with human expertise and external collaboration.

    Regional Confidence Varies Widely

    The study found notable regional differences in AI readiness confidence. The Asia-Pacific region led with 89% confidence, followed by North America at 84%. Europe trailed significantly at 38.3%. These figures reflect perceived readiness rather than actual deployment of agentic AI systems.

    HCLTech suggests that firms must connect AI investments with operational changes and measurable business outcomes. The research offers a snapshot of where modeled decision-makers see gaps today, not a prediction of how quickly those gaps will close.

    For wealth managers, the message is clear: adding AI tools is not the same as transforming the work those tools support. The industry’s enthusiasm for AI is evident, but meaningful progress in agentic capabilities remains limited.
  • AI in Banking: Sajeev Viswanathan on Connected Intelligence, Governance, and Fraud Prevention

    AI in Banking: Sajeev Viswanathan on Connected Intelligence, Governance, and Fraud Prevention

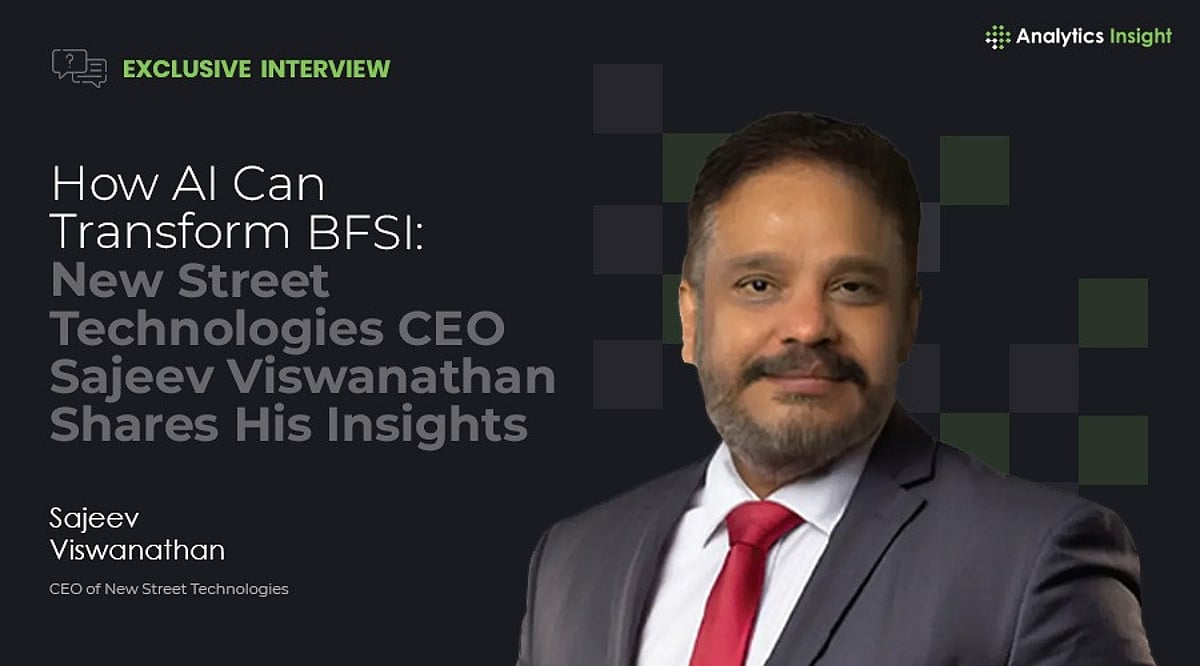
    In a recent interview, Sajeev Viswanathan, CEO of New Street Technologies, shared his vision for how artificial intelligence can transform the banking, financial services, and insurance (BFSI) sector. Rather than deploying AI as isolated point solutions, Viswanathan argues that financial institutions must build a connected, governed intelligence layer that spans the entire organization.

    According to Viswanathan, fragmentation occurs when AI is deployed as a collection of individual tools—such as a voice bot in one department, a coding assistant in another, and employees using consumer-grade LLMs for research. While each may solve a local problem, collectively they create new silos, data boundaries, and governance challenges. The solution is not to ban these tools but to provide a common foundation: a shared layer for identity, audit, version control, and domain intelligence.

    Viswanathan emphasizes the importance of Domain Intelligence Models (DIMs)—permissioned, shared intelligence that multiple processes and products can draw upon, with an optional interface to external LLMs when needed. Keeping AI decoupled from production execution is also critical. When AI-generated designs pass through maker-checker approval before deterministic engines run them, institutions achieve consistency and auditability by design.

    On fraud detection and regulatory compliance, Viswanathan notes that industry-specific AI models—shaped around BFSI transaction patterns, SWIFT message structures, KYC/AML workflows, and regulatory reporting formats—can identify anomalies that general-purpose models miss. However, the real strength comes from the architecture: separating AI that flags or designs from the deterministic engine that executes, ensuring explainability, auditability, and human oversight. Privacy is built in by allowing domain intelligence to be permissioned without moving sensitive customer data outside its governed environment.

    Viswanathan believes that as AI models become more accessible, differentiators will shift from model size to governance, deployment architecture, data strategy, and execution discipline. Banks that can implement regulatory changes in hours or launch new products in days on a well-governed platform will have a significant advantage. Key metrics like time-to-market and total cost of technology ownership become crucial.

    Regarding collaboration to combat financial crime, Viswanathan suggests that shared pattern intelligence and threat signals can be exchanged without compromising competitive advantage. Fraud typologies and money laundering patterns are not areas of competition; differentiation comes from customer experience, pricing, and product design. Federated approaches—where signals or models are shared while underlying data remains local—are particularly relevant. Regulator-sponsored or industry utility models also hold promise.

    Looking ahead, Viswanathan sees industry-specific AI ecosystems becoming as foundational as payment networks. Banks should prioritize three things: modernizing the operational core (not just customer-facing channels), embedding governance by design (audit trails, version control, maker-checker workflows, human oversight), and investing in domain intelligence rather than relying solely on generic AI tools. Ultimately, customers will choose a bank not because it uses AI, but because it responds faster, manages risk better, and earns their trust. AI may be the engine, but trust remains the defining differentiator.

  • Managing AI Token Costs in Financial Services: Strategies for Visibility and Control

    Managing AI Token Costs in Financial Services: Strategies for Visibility and Control

    What Is an AI Token Cost?

    An AI token is a small unit of text that an AI model processes. It can represent part of a word, a whole word, or punctuation. AI providers typically charge based on the number of tokens processed. Input tokens are the information sent to the model, while output tokens are the model’s response. Output tokens often cost significantly more than input tokens. For financial companies, token costs can escalate quickly. A customer chatbot may handle thousands of conversations daily, and an investment research system may process lengthy reports and filings. The number of users is only part of the equation — the amount of information processed matters just as much.

    Why AI Token Costs Are Hard to Control

    Traditional technology budgets are often easier to forecast. AI consumption can change with every interaction. A simple request might use few tokens, while another could include documents, previous conversations, and detailed instructions. AI agents add another layer of complexity: one user request can trigger multiple model calls, tool calls, and retries, all increasing the final bill. Financial companies also use different models for different tasks. Using the most powerful model everywhere can create unnecessary spending.

    How Financial Companies Can Track AI Spending

    The first step is creating clear visibility into AI consumption. Companies should know which teams use each model and track usage by application, workflow, and business function. Useful metrics include cost per request, cost per user, and cost per completed task. An AI gateway or proxy can help collect this information and connect API usage with teams, applications, and internal cost centers. The FinOps Foundation recommends API governance and proxy layers for stronger attribution. Financial companies should also establish clear ownership: technology teams control architecture, finance teams manage budgets, and security and procurement have important responsibilities.

    Reduce Costs Through Smarter Model Selection

    Model selection significantly affects AI spending. Not every financial task needs a premium model. A smaller model can effectively handle document classification or simple customer-service questions. More advanced models should be reserved for complex research or reasoning tasks. This approach is known as model routing — automatically sending requests to the most appropriate model based on complexity. Prompt design also matters: unnecessary instructions and repeated information increase token usage. Companies should remove irrelevant context and summarize older conversations before sending them again.

    Use Caching, Batching, and Workflow Controls

    Repeated information does not always need to be processed from scratch. Prompt caching can reduce repeated input-token costs, especially for financial applications using stable documents or instructions. Research systems may repeatedly reference the same datasets or regulatory materials. Batch processing can also lower costs for non-urgent workloads by processing large groups of tasks together. Agentic workflows require additional controls: limit unnecessary retries and repeated tool calls, and monitor agent loops and escalation paths. A McKinsey report identified caching, model selection, prompt optimization, and workflow controls as important AI cost levers.

    Build AI Cost Management Around Business Value

    Financial companies should not treat token spending as only an IT problem. The bigger question is whether that spending creates measurable business value. A cheaper model is not useful if it produces poor results, while an expensive model can be justified for high-value financial analysis. Companies should connect AI costs with measurable outcomes such as processing time, customer resolution rates, or analyst productivity. The emerging discipline of “tokenomics” focuses on this broader relationship, considering model selection, routing, workflows, infrastructure, and business value as a whole. AI costs will remain an important concern as adoption expands. Financial companies need visibility before optimization and governance before AI spending becomes difficult to control. The strongest approach combines finance, technology, security, and business teams. Token costs are only one part of AI economics — managing them effectively requires understanding the entire workflow behind each AI request.

  • OpenAI Unveils ChatGPT for Financial Institutions Powered by GPT-6 Astra

    OpenAI Unveils ChatGPT for Financial Institutions Powered by GPT-6 Astra

    OpenAI Launches ChatGPT for Financial Services

    OpenAI has launched a specialized version of ChatGPT designed specifically for banks and financial institutions. The new offering integrates financial data from multiple providers with the reasoning capabilities of GPT-6 Astra to support financial research, modeling, and client work.

    What ChatGPT for Financial Services Offers

    The service includes built-in financial data from providers such as Daloopa, PitchBook, LSEG News, and Crunchbase. This data covers earnings transcripts, financial statements, company information, and private companies. OpenAI hosts and indexes this data on its infrastructure, allowing financial teams to access the datasets without negotiating separate contracts or setting up individual connectors.

    Detailed citations are provided, helping users trace figures and claims back to their sources during analysis. For example, bankers can use the tool to examine a company’s adjusted EBITDA, identify the costs removed during the calculation, and understand how the figure could affect a valuation.

    GPT-6 Astra at the Core

    GPT-6 Astra powers ChatGPT for Financial Services. According to OpenAI, the model can work with financial documents, tables, figures, and supporting notes. It can analyze financial information, draw conclusions, and turn the results into documents, spreadsheets, and presentations.

    “GPT-6 Astra is state of the art across three of the core capabilities required for financial services work: information retrieval, financial reasoning, and artifact generation,” OpenAI said.

    Templates and Security

    The service allows administrators to upload and manage Excel, Word, and PowerPoint templates. This helps teams create research notes, valuation models, and pitchbooks that follow their firm’s existing format and style.

    OpenAI developed the product with input from financial firms including Morgan Stanley. ChatGPT for Financial Services is currently available to eligible financial institutions.

    OpenAI stated that it will not use company data to train its models by default. Data is encrypted during transfer and storage, adding security measures for financial organizations handling sensitive information.

  • Top 7 FinTech Innovations Reshaping Financial Services

    Top 7 FinTech Innovations Reshaping Financial Services

    The financial services industry is undergoing a profound transformation driven by cutting-edge technologies. From artificial intelligence to blockchain, these innovations are enhancing efficiency, security, and accessibility. Below are the seven biggest FinTech innovations that are changing the way we manage money and conduct transactions.

    AI-Powered Finance

    Artificial intelligence is revolutionizing financial operations by automating fraud detection, credit assessments, customer support, and personalized financial advice. AI tools process vast amounts of data in real time, improving speed and accuracy while strengthening overall decision-making.

    Blockchain Technology

    Blockchain provides a decentralized ledger for transaction records, smart contracts, and digital assets. By reducing the need for intermediaries, it enhances settlement efficiency, transparency, and trust across financial markets.

    Real-Time Payments

    Real-time payment systems enable instant fund transfers and immediate availability of money. This innovation helps consumers and businesses manage cash flow with greater speed and convenience, reducing reliance on traditional banking delays.

    Embedded Finance

    Embedded finance integrates payments, lending, insurance, and banking services directly into non-financial platforms. This makes financial tools accessible within everyday digital experiences, such as shopping or ride-hailing, while maintaining security.

    Open Banking

    Open banking leverages APIs and customer-permitted data sharing to connect financial accounts across institutions. This enables personalized services, broader product choices, and smarter financial decisions for consumers.

    Digital Identity

    Digital identity technologies streamline customer onboarding and authentication while reducing fraud. They help financial institutions verify users securely across increasingly digital channels, enhancing both convenience and security.

    RegTech

    Regulatory technology (RegTech) automates compliance monitoring, reporting, screening, and risk controls. It enables financial institutions to respond faster to regulatory requirements and reduce operational burdens.

    Additional innovations such as asset tokenization and agentic AI are also gaining traction, offering fractional ownership of real-world assets and autonomous execution of multi-step tasks like reconciliation and compliance checks. Together, these technologies are shaping the future of finance.

  • How AI Agents Are Revolutionizing Banking and Financial Services in 2026

    How AI Agents Are Revolutionizing Banking and Financial Services in 2026

    Artificial intelligence is moving far beyond simple chatbots in the banking sector. As of 2026, AI agents are handling complex tasks across credit assessment, fraud detection, customer service, and capital markets, fundamentally reshaping how financial institutions operate. A global study conducted by Cambridge Judge Business School, the Bank for International Settlements, the International Monetary Fund, and the World Economic Forum reveals that 81% of financial firms now use AI at some level, though only 14% consider it transformational for strategy and competitive advantage. This indicates widespread adoption but limited deep integration.

    AI Agents Go Beyond Chatbots

    The most significant shift is the emergence of AI agents that can perform multi-step tasks. Unlike chatbots that only answer questions, agents can review documents, check policy rules, identify missing data, prepare credit cases, and route them for human approval. Citi has developed Arc, an internal platform for AI agents used in research and task execution. Fiserv launched agentOS, a platform with policy controls, audit trails, and human oversight. This evolution positions AI as a work partner rather than a mere information source.

    Faster and Smarter Credit Decisions

    AI is transforming credit assessment by analyzing cash flow, account activity, income patterns, business data, and repayment history together—far beyond traditional forms and fixed checks. This wider view enables lenders to make faster decisions with less paperwork. BCG highlights agent-led credit journeys, faster credit review, and more personalized collections as key AI opportunities. Better data usage also helps lenders identify risk earlier.

    The AI Fraud Race

    Fraud detection has become an AI-versus-AI battle. Criminal groups use AI for fake identities, deepfakes, and phishing at scale. Banks now combine rules, machine learning models, graph analysis, and generative AI to detect unusual activity. The Federal Reserve has endorsed this multi-layered approach. Systems assess transactions alongside account links, device signals, merchant activity, and past behavior to reveal patterns missed by single-transaction checks.

    Customer Service: From Answers to Action

    AI assistants now go beyond answering balances and fees. They can help set savings targets, review expenses, and suggest plans. With proper permissions, they can even execute tasks like moving money or paying bills. Visa introduced an AI Financial Assistant in July 2026 for banks, noting that over 66% of surveyed Americans who used generative AI had sought financial advice through it. This creates a path from advice to approved action.

    Specialist AI in Capital Markets

    Banks use specialized models for market research, risk checks, liquidity forecasts, portfolio management, and foreign exchange. In August 2026, Citi, HSBC, and Standard Chartered adopted Ant International’s Falcon Time-Series Transformer Model 2.0, which reportedly cuts FX hedge and allocation costs by over 60%. Specialist AI models now play a stronger role across financial markets.

    Trust and Control Matter More Than Ever

    AI brings serious risks: model errors, data access issues, fraud, cyber threats, and poor decisions. The Financial Stability Board issued a June 2026 consultation on responsible AI use in finance, focusing on generative and agentic AI. The UK Financial Conduct Authority also warned about risks to firm operations, customer journeys, competition, fraud, and cybersecurity. Strong controls are as important as model quality.

    The Next Bank Model

    The next major change will come when AI agents gain secure access to core bank systems. A customer could grant an agent a clear task, expense limit, and permission to act, allowing it to compare products, move money, pay bills, or manage cash within set rules. This transforms AI from support to core system component. The strongest banks will combine robust data capabilities, modern infrastructure, useful AI agents, and firm controls. The central race now is about safe AI use at scale.

    Key Takeaways

    • AI agents now handle complex banking tasks across credit, fraud, research, and customer service.
    • Banks use AI to improve speed, accuracy, and personalization across financial services.
    • Strong governance, cybersecurity, privacy, and human oversight remain essential for safe AI adoption.

    Frequently Asked Questions

    How is AI changing banking in 2026?

    AI is transforming credit decisions, fraud detection, customer service, compliance, research, and other core banking processes.

    What are AI agents in banking?

    AI agents can complete multi-step tasks such as checking documents, applying rules, and preparing cases for human approval.

    Can AI improve fraud detection?

    Yes. Banks combine AI models, rules, and graph analysis to identify unusual transaction patterns and potential fraud.

    How does AI affect customers?

    AI provides faster support, personalized financial guidance, and with proper approval, helps customers complete financial tasks.

    What are the main risks of AI in finance?

    Key risks include cyber threats, data privacy issues, model errors, fraud, and poor decisions without suitable human oversight.

  • How AI Is Building Adaptive Financial Ecosystems: Insights from Equiniti India’s Engineering Head

    How AI Is Building Adaptive Financial Ecosystems: Insights from Equiniti India’s Engineering Head

    Artificial intelligence is rapidly transforming financial services, enabling organizations to modernize legacy operations without compromising trust, security, or regulatory compliance. Beyond improving operational efficiency, AI is helping financial institutions accelerate software development, automate complex workflows, enhance decision-making, and deliver better customer experiences.

    For companies with long-standing industry expertise, the real opportunity lies in adopting AI responsibly. Strong governance, transparency, and human oversight are becoming just as important as innovation, ensuring businesses can unlock AI’s potential while maintaining the confidence of clients and regulators.

    Jyoti Prakash Dash, Head of Engineering at Equiniti India, believes AI will go far beyond automation to reshape how financial services are designed and delivered. In an exclusive interview, he shares Equiniti India’s AI strategy, the evolving role of engineering leaders, workforce readiness in the GenAI era, and how intelligent financial ecosystems will define the industry’s future.

    Modernizing a 200-Year Legacy with AI

    Dash explains that AI enables Equiniti to modernize complex financial services operations while preserving the trust, accuracy, and regulatory compliance clients expect. The focus is on responsible AI adoption that enhances productivity, decision-making, and customer outcomes through strong governance, transparency, security, and human oversight.

    Engineering Leadership in the AI Era

    The role of engineering leadership has evolved from managing delivery to orchestrating teams with AI capabilities. Success now depends on driving AI adoption, establishing guardrails, building AI-ready talent, and accelerating innovation without compromising quality, security, or compliance.

    Where AI Is Creating Value

    Equiniti India is embedding AI across software engineering, testing, operational processes, and data-driven decision-making. The impact is already visible through improved developer productivity, faster delivery, enhanced quality, and increased automation, allowing teams to focus on higher-value innovation and customer outcomes.

    Skills Engineers Need in the AI Era

    Engineers must develop AI fluency alongside strong fundamentals in architecture, systems thinking, data, security, and governance. At Equiniti India, significant investment is being made in AI enablement, communities of practice, hands-on learning, and responsible AI adoption to prepare teams for the future.

    Long-Term Vision: Intelligent, Adaptive Ecosystems

    Dash’s vision is to move beyond automation and build intelligent, adaptive financial services ecosystems. AI will enable better decision-making, greater personalization, stronger risk management, and faster innovation, creating sustainable competitive advantage for clients and transforming how financial services are delivered.

  • CRED’s Next Move: What Lies Ahead for Kunal Shah’s Fintech Platform

    CRED’s Next Move: What Lies Ahead for Kunal Shah’s Fintech Platform

    CRED has emerged as one of India’s most prominent fintech platforms, and questions are mounting about its next phase of growth and innovation. Founded by Kunal Shah, the company initially gained traction by rewarding users for timely credit card payments while cultivating a premium financial community.

    Beyond bill payments, CRED has expanded into lending, payments, financial products, and money management solutions. After years of rapid expansion, the company’s future focus is expected to sharpen on stronger monetization, deeper customer engagement, and sustainable business growth.

    India’s fintech market is becoming increasingly competitive, with digital payment platforms and financial technology companies launching new products for consumers. CRED’s ability to attract high-value users remains a key advantage as it explores fresh opportunities in the evolving financial services sector.

    The company faces challenges including profitability expectations, intensifying competition, shifting regulations, and the need to maintain long-term customer trust. Future growth could depend on expanding financial services while delivering greater value beyond traditional payment experiences.

    CRED’s next chapter will be closely watched as the fintech industry moves toward deeper digital banking and personalized financial solutions.

  • Freedom Holding Corp. Enters Turkish Banking with Acquisition of Turkish Bank A.Ş.

    Freedom Holding Corp. Enters Turkish Banking with Acquisition of Turkish Bank A.Ş.

    Nasdaq-listed Freedom Holding Corp. has completed the acquisition of a 99.32% stake in Turkish Bank A.Ş., marking its formal entry into Türkiye’s banking sector and laying the groundwork for an integrated financial and digital platform. The transaction was executed through its subsidiary, Freedom Finansal Hizmetler A.Ş., and the bank has been renamed Freedom Bank A.Ş. following the transfer of control.

    The Acquisition Is Only the First Step

    The deal was finalized after receiving approval from Türkiye’s Banking Regulation and Supervision Agency (BDDK) and the Turkish competition authority. Freedom Holding plans to strengthen the bank’s capital position, upgrade its IT infrastructure, develop digital channels, launch new products, and improve operational efficiency.

    According to the BDDK, more than 120 million digital bank accounts have been opened in the country, with approximately 85% of the population using mobile banking. Turkish customers are already accustomed to advanced mobile-banking services, meaning the new platform must compete not only on product range but also on app usability, transaction speed, and overall customer experience.

    Türkiye occupies a special place in Freedom Holding Corp.’s global growth strategy. The country serves as a geographical bridge between Europe and Asia and a strategic gateway connecting the world’s largest financial markets.

    Why the Ecosystem Needs Its Own Bank

    Freedom Holding Corp. began building its Turkish infrastructure in 2022 with the establishment of Freedom Finansal Hizmetler A.Ş., created to support investments in banking, insurance, capital markets, payment systems, and other financial-services segments. In 2025, after approval from Türkiye’s Capital Markets Board, Freedom Yatırım Menkul Değerler A.Ş. was formed as the group’s local brokerage platform.

    The bank acquisition complements Freedom’s expansion into Türkiye’s capital markets. The group now has a banking platform on which to build its own ecosystem in the country. Banking services provide regular customer contact through accounts, cards, payments, transfers, deposits, and lending products, placing the acquired bank at the center of the future platform.

    Testing Freedom’s Kazakhstan Model in Türkiye

    In Kazakhstan, Freedom Holding has already built an ecosystem combining banking, brokerage, investment, insurance, payment services, e-commerce, travel, ticketing, and entertainment. The group plans to draw on this experience in Türkiye.

    “In Kazakhstan, we built an ecosystem in which financial and everyday services operate through a single SuperApp, which has become the country’s fastest-growing digital service,” said Timur Turlov, founder and CEO of Freedom Holding Corp. “We are now bringing this model to Türkiye, where customers already have high expectations of their banks. Our task over the next few years is to strengthen the bank’s capital base and technological capabilities so that an ecosystem can develop rapidly around it.”

    The group’s experience in Kazakhstan demonstrates that financial and lifestyle services can be combined on a single digital platform. Türkiye will show how successfully the model can scale beyond the home market.

    Freedom Holding Corp. operates in 22 countries, including Kazakhstan, the United States, Cyprus, Poland, Spain, Uzbekistan, and Armenia, with its principal executive office in New York. Its shares trade under the ticker FRHC on Nasdaq, the Kazakhstan Stock Exchange, and the Astana International Exchange.

    The company strengthened its financial position in fiscal year 2026, which ended March 31. Revenue increased 9% year-on-year to $2.19 billion, while net income more than doubled to $153.3 million from $76.2 million a year earlier. Total assets rose 33% to $13.16 billion. By March 2026, the Freedom ecosystem served more than 14 million customers.

    In June 2026, S&P Global Ratings upgraded the credit ratings of four Freedom subsidiaries to BB- with a Stable outlook, while affirming the holding company’s long-term issuer credit rating at B-, also with a Stable outlook.

  • 7 Undervalued Indian Stocks for Long-Term Growth in August 2026

    7 Undervalued Indian Stocks for Long-Term Growth in August 2026

    Undervalued stocks are those trading below their intrinsic value, offering potential for long-term investors who seek strong fundamentals and sustainable growth. As India’s economy is projected to expand by over 6% in FY27, sectors like banking, financial services, infrastructure, and capital markets are well-positioned for wealth creation. Here are seven undervalued stocks to consider for long-term growth this August.

    1. Tamilnad Mercantile Bank Ltd

    Market Cap: Rs. 14,179 crore
    Tamilnad Mercantile Bank (TMB), trading at Rs. 894, has maintained solid asset quality and steady profitability while expanding its retail loan book. With a conservative lending approach and enhanced digital banking capabilities, this regional bank offers attractive long-term prospects. Established in 1921, TMB serves retail customers and MSMEs.

    2. Godawari Power and Ispat Ltd

    Market Cap: Rs. 20,501.30 crore
    Godawari Power and Ispat benefits from India’s infrastructure and manufacturing boom. Its integrated steel business, captive power generation, and strong balance sheet help sustain healthy margins despite commodity price fluctuations.

    3. Can Fin Homes Ltd

    Market Cap: Rs. 10,861 crore
    Trading at Rs. 816, Can Fin Homes is a housing finance company (HFC) registered with the National Housing Bank. Canara Bank holds a 29.99% stake. The company focuses on smaller-ticket housing loans to salaried and self-employed borrowers, with stable asset quality and steady loan growth supporting its long-term outlook.

    4. ICICI Securities Ltd

    Market Cap: Rs. 29,149 crore
    ICICI Securities, trading at Rs. 896, provides institutional and retail broking, financial product distribution, merchant banking, and advisory services. Rising retail investor participation and vibrant equity markets continue to drive its brokerage business.

    5. Motilal Oswal Financial Services Ltd

    Market Cap: Rs. 52,429 crore
    Founded in 1987, Motilal Oswal operates across 550+ cities with 2,500+ business locations and over 1.6 million customers. Trading at Rs. 869, the company generates diverse revenue streams through its diversified financial services model, capitalizing on India’s growing financialization.

    6. Gujarat Mineral Development Corporation Ltd (GMDC)

    Market Cap: Rs. 22,686.10 crore
    GMDC is a key player in Indian mining, with exposure to lignite, bauxite, manganese, and other minerals. Government infrastructure spending and rising industrial demand underpin its strong long-term prospects.

    7. Angel One Ltd

    Market Cap: Rs. 27,785 crore
    Angel One is a diversified financial services company engaged in stock, commodity, and currency broking, institutional broking, margin trading, depository services, mutual fund distribution, NBFC lending, and insurance corporate agency. Its broad service suite positions it well for continued growth.

    Final Thoughts: These stocks appear undervalued under current market conditions, but investors should conduct their own research on valuation, earnings quality, and risks. A diversified, long-term approach is the best way to navigate market volatility.