Tag: fintech

  • Kunal Shah’s CRED: From Credit Card Rewards to a $4.5 Billion Financial Ecosystem

    Kunal Shah’s CRED: From Credit Card Rewards to a $4.5 Billion Financial Ecosystem

    Kunal Shah founded CRED in 2018 with a simple yet powerful idea: reward creditworthy consumers for paying their credit card bills on time. What started as a members-only platform has since transformed into a comprehensive financial ecosystem spanning payments, lending, insurance, wealth management, and lifestyle services.

    Starting with Credit Card Payments

    CRED’s initial offering targeted disciplined credit card users. Members could manage multiple cards, track spending, receive payment reminders, and understand their credit behavior. By linking timely payments to rewards, CRED turned a routine financial task into an engaging experience. Today, the platform processes more than 40% of India’s credit card bill payments and serves 17 million monthly members.

    Building a Broader Payments Platform

    CRED expanded its payment capabilities around its core customer base. It introduced UPI payments through CRED Pay, enabling users to scan QR codes and earn rewards, along with tap-to-pay on supported Android devices. In June 2026, CRED launched multibill payments and autopay for credit card bills up to Rs. 2 lakh, with over 70% of members holding multiple credit cards.

    Expansion into Lending, Wealth, and Insurance

    The company’s next phase moved beyond payments. CRED’s lending business now manages Rs. 24,000 crore in assets for top financial institutions. It also launched Yosemite, an invite-only society called Sovereign, a co-branded RuPay credit card with IndusInd Bank, and tools for tracking asset portfolios and long-term investments. Later additions include Cash by CRED and an AI-powered credit coach.

    Technology at the Center

    Technology remains the backbone of CRED’s model, connecting payments, credit management, rewards, and financial services. The platform relies on encrypted data and transaction systems. Its lending operation partners with banks and NBFCs, with CRED acting as a lending service provider. In June 2026, CRED received final RBI authorization to operate as a payment aggregator. The company also developed CRED codelens, a system delivering 4x AI acceleration using Amazon Bedrock.

    Meta’s $900 Million Investment

    CRED reached a major milestone in June 2026 when Meta led a Rs. 8,550 crore ($900 million) Series H funding round, valuing CRED at approximately $4.5 billion post-money. Meta became a minority investor without access to customer data. Concurrently, Shah stepped away from his operating role as CEO to join Meta’s global leadership team. Miten Sampat, who joined CRED in 2020 and led strategy and finance, became interim CEO.

    From Payments App to Financial Ecosystem

    CRED’s journey reflects a deliberate strategy of expanding services for financially active consumers. The company now generates about Rs. 3,200 crore in revenue and is profitable, with a full stack of licenses. An eventual IPO remains a long-term goal. With Shah moving to Meta, CRED’s next phase will continue under its existing board and leadership, expanding its financial services footprint.
  • Apple Pay’s India Debut Could Begin With Axis Bank as First Partner

    Apple Pay’s India Debut Could Begin With Axis Bank as First Partner

    Apple Pay Prepares for India Launch

    Apple is preparing to bring its Apple Pay service to India, with Axis Bank expected to be its first banking partner for the rollout, according to people familiar with the matter. The service could launch in India as soon as next month, starting with support for Axis Bank credit cards.

    Discussions With HDFC Bank and ICICI Bank

    Apple has also held discussions with HDFC Bank and ICICI Bank about adding their cards to Apple Pay, but those talks have not yet resulted in final commercial agreements, according to two sources. Apple and the three banks declined to comment to Reuters on the discussions.

    Apple Pay is designed to allow iPhone users to make contactless payments using tokenized versions of their card details. Card information is stored on the device, so users can pay without opening another payment app. Apple is expected to add more banks through separate agreements over time, allowing the service to expand gradually after its initial rollout.

    Entering a UPI-Dominated Market

    Apple Pay will enter a payments ecosystem where UPI accounts for a major share of digital transactions. According to Reuters, UPI represented 84% of India’s digital payment volume. The National Payments Corporation of India has also introduced a tap-and-pay option using near-field communication technology, giving smartphone users another way to make contactless payments.

    Recent changes in payment rules have also created room for Apple Pay. The Reserve Bank of India allowed biometric authentication for card payments last year, supporting card transactions through features such as Face ID and Touch ID.

    Apple’s Growing Presence in India

    The India entry comes as Apple gains ground in the country’s smartphone market. Counterpoint Research data cited by Reuters shows Apple’s market share reached 8%, twice its level in 2022. India is now among Apple’s largest smartphone markets.

    Axis Bank had about 16.26 million active credit cards in July, according to RBI data, making it the fourth-largest card issuer in India after HDFC Bank, SBI Cards, and ICICI Bank. An Apple Pay launch would give Apple a foothold in India’s contactless card payment segment, and its expansion will likely depend on adding more banks and card networks to the service.

  • Agentic AI Reshapes Banking, Payments, and Fintech: Key Insights

    Agentic AI Reshapes Banking, Payments, and Fintech: Key Insights

    Agentic AI is poised to revolutionize the financial sector by moving beyond simple customer service to autonomously handling complex banking tasks, payments, and fraud detection. This technology enables AI agents to analyze spending, execute transactions, and offer personalized financial advice, all while reducing manual effort and improving efficiency.

    Smarter Banking Decisions

    Agentic AI can analyze a customer’s spending habits, understand their financial goals, compare available options, and take approved actions. From moving money between accounts to managing recurring payments, these systems make everyday banking more automated, faster, and user-friendly.

    AI-Powered Payments

    Instead of manually completing every step of a payment, an AI agent can identify bills, check payment details, and complete transactions after receiving permission. It also monitors upcoming expenses and reminds users about payments, making digital transactions more convenient and organized.

    Fraud Detection Gets Proactive

    Traditional fraud systems react to unusual activity after it occurs. Agentic AI continuously monitors transactions, customer behavior, and account activity to spot risks earlier. It can investigate unusual patterns, request additional verification, and alert financial institutions, enabling faster threat response.

    Personalized Financial Services

    By studying a customer’s financial activity, Agentic AI offers tailored services such as spending pattern analysis, expense management suggestions, and savings planning. Unlike basic recommendation tools, AI agents can follow through on approved actions, turning suggestions into practical steps.

    Faster Fintech Operations

    Fintech companies handle large volumes of customer requests, transactions, compliance checks, and data. Agentic AI automates repetitive processes and coordinates tasks across systems, reducing manual work and allowing teams to focus on complex issues, product development, and business decisions.

    A New Role for Human Bankers

    Agentic AI does not eliminate the need for human employees. Instead, it handles routine tasks while bankers focus on areas requiring judgment, relationships, and complex financial advice. Human oversight remains essential, especially when AI agents make decisions involving money, sensitive data, or financial risk.

    The Road Ahead for Agentic Finance

    Agentic AI is pushing banking and fintech toward services that act rather than simply respond. Customers may increasingly rely on AI agents to manage routine financial tasks across accounts and services. This shift raises important questions about security, privacy, accountability, consent, and the degree of control customers grant AI systems.

  • Money in Motion: The Key Technologies Transforming Digital Finance

    Money in Motion: The Key Technologies Transforming Digital Finance

    Digital finance is evolving at unprecedented speed. From artificial intelligence to biometric authentication, a range of technologies is changing how consumers and institutions handle money. Here is a closer look at the innovations reshaping payments, banking, and financial services.

    Artificial Intelligence

    AI is changing how banks and financial apps handle everyday money tasks. It can detect unusual transactions, assess risks, answer customer questions, and offer personalized financial services. AI also helps institutions process large amounts of data quickly, making digital payments and banking services faster, safer, and more responsive.

    Blockchain

    Blockchain provides a shared digital record that can track transactions without relying on a single central database. The technology supports cryptocurrencies, smart contracts, and other financial applications. Banks and businesses are exploring blockchain for faster settlements, cross-border payments, digital assets, and records that are easier to verify and trace.

    Mobile Payments

    Smartphones have become a central part of everyday finance. Users can pay bills, transfer money, shop online, and make purchases at physical stores through banking apps and digital wallets. QR codes and near-field communication have further simplified payments, reducing the need for cash and cards.

    Cloud Computing

    Cloud computing gives financial institutions flexible computing power and storage through internet-based systems. Banks use cloud infrastructure to run applications, manage data, and launch digital services without relying entirely on traditional hardware. It also supports faster updates and helps financial platforms handle changing customer demand.

    Open Banking

    Open banking allows customers to share financial information with authorized third-party services through secure APIs. This connects bank accounts with budgeting apps, payment platforms, lending services, and other financial tools. By making data easier to access with permission, open banking is creating more connected digital financial experiences.

    Biometric Authentication

    Biometric authentication uses features such as fingerprints, facial recognition, or voice patterns to confirm a user’s identity. It has become common across smartphones and financial applications, helping users access accounts and approve transactions. Biometrics make authentication quicker while adding another layer of identity verification to digital financial services.

  • Column Launches Unified Stablecoin and Banking Platform for USDC and USDT Payments

    Column Launches Unified Stablecoin and Banking Platform for USDC and USDT Payments

    Column has introduced four financial infrastructure products that bring stablecoins, card issuing, global banking, and multicurrency accounts together on a single platform. Announced on September 16, the rollout enables fintech companies to use USDC and USDT alongside traditional bank accounts, cards, and payment networks.

    Column co-founder William Hockey said the launch completes a multi-year effort to build the company’s technology stack. In a company post, Hockey stated, “We have finally completed that build.” He added that the products are already handling billions of dollars for fintech companies, including Ramp, Brex, Bilt, Mercury, Slash, and Kapital.

    Stablecoin Services Integrated with Bank Payment Rails

    Column’s stablecoin service allows businesses to send and receive USDC and USDT while converting funds to and from US dollars at any time, 24/7. The company built the service directly into its banking core, so customers do not need to prefund balances with a separate provider before making a stablecoin transfer. The platform connects stablecoin activity with both US and international payment rails.

    For example, a business receiving USDC from Mongolia could convert the funds into dollars, split the money, send one portion to a US community bank through FedNow, and convert another into euros for a SWIFT payment. Column said the entire process can take place within seconds via its APIs and operates around the clock, including weekends and holidays.

    Card Issuing Combines Banking, Processing, and Capital

    Column also launched a card issuing product after building its own issuer processor. The service brings together the issuing bank, processing system, and capital into a single integration. Customers can use the platform to create credit, debit, prepaid, and stablecoin-backed card programs on the Visa and Mastercard networks. Column had previously sponsored card programs but now controls the processing layer, allowing it to manage card authorization and settlement within the same system that supports its banking products. This reduces the number of separate providers fintech companies need when launching card programs. The processor has direct connections to Visa and Mastercard and runs on the same core infrastructure used for Column’s other banking services.

    Global Banking and Multicurrency Accounts

    The third product extends Column’s account and card infrastructure to verified customers outside the United States. Businesses can offer US dollar or local currency accounts and cards to eligible users in other markets while using the same compliance tools and APIs used for domestic customers. Column did not publish a full list of supported countries, so availability depends on its banking and verification coverage.

    Column also introduced multicurrency accounts that allow customers to receive, hold, and send foreign currencies. Users can convert supported currencies to and from US dollars instantly and connect payments to international systems, including SEPA Instant. Supported currencies include euros, British pounds, and Canadian dollars, among others.

    Together, the four products enable fintech companies to connect stablecoins, bank accounts, cards, and foreign currency payments through one platform. Column said the services work together because they use the same underlying infrastructure. The company did not provide separate transaction volumes for each product, but Hockey noted the services are already moving billions of dollars for fintech customers.

  • Why Keeping Humans in the Loop Is Critical for AI-Driven Financial Crime Compliance

    Why Keeping Humans in the Loop Is Critical for AI-Driven Financial Crime Compliance

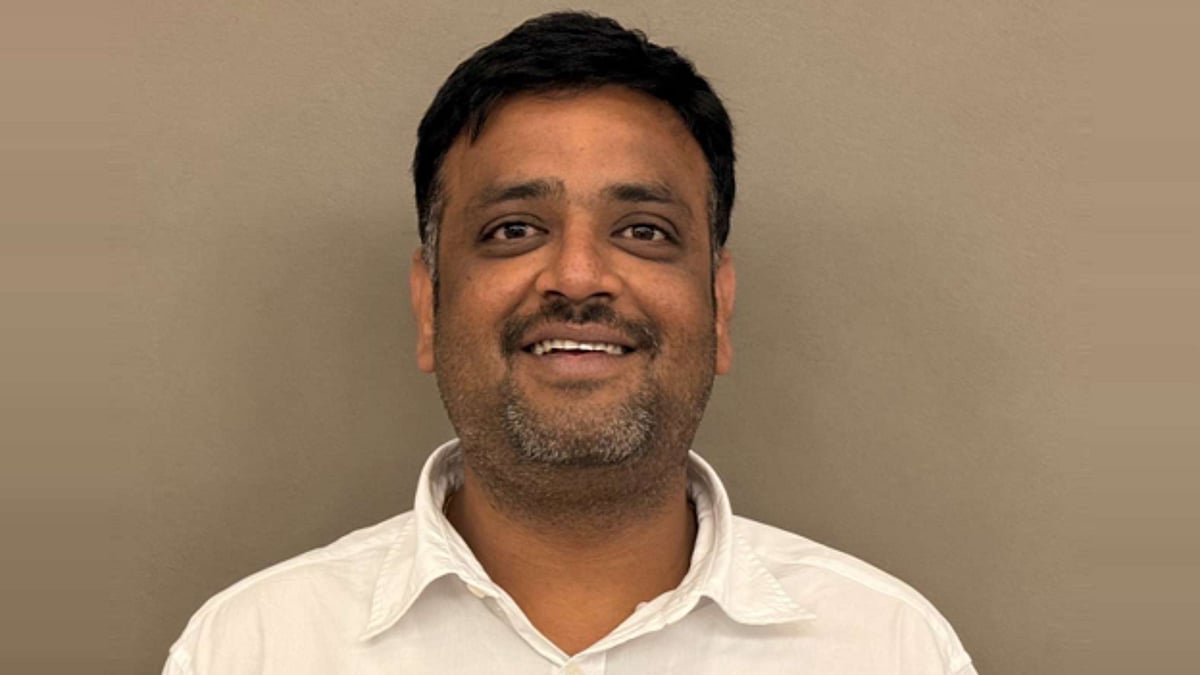
    The debate over artificial intelligence in financial crime compliance is often framed as a choice between automation and human judgment. Sriramakrishna Vadlamudi, a veteran in enterprise financial services technology, argues that this framing is fundamentally flawed. Instead of turning a dial between the two, the best systems redesign where and how humans engage.

    Vadlamudi, who has spent nearly a decade working on anti-money-laundering compliance automation, points out a common pitfall: institutions conflate automating data validation, case routing, and narrative drafting with automating the decision itself. This conflation quietly erodes oversight while maintaining the appearance of procedural compliance.

    He designed a system that automates data validation and routing, cutting manual processing errors by roughly 40 percent. The tool reduces rework and delays, but it deliberately does not dispose of cases. Structured checkpoints remain where a person must review and approve before a case closes. This design decision preserves meaningful human judgment.

    Vadlamudi warns that automating too little fails to deliver efficiency, but automating too much turns human review into a rubber stamp. The latter is worse than no review, because it creates a record of oversight that never actually occurred. He notes that institutions getting this wrong often treat a model’s recommendation as sufficient justification, quietly eroding the oversight regulators rely on.

    One of his most impactful insights is that explainability is not merely a data-science requirement; it is a compliance control. A model that cannot produce a defensible explanation for an individual decision represents an audit gap, not just a technical shortcoming. He built a feature-attribution approach that surfaces the specific factors driving a model’s score in a form that compliance investigators can evaluate, rather than a number to accept or reject blindly.

    Looking ahead, Vadlamudi sees agentic AI taking on multi-step investigative and drafting work. He argues that each intermediate step an agent takes must be auditable, just as an analyst’s actions would be. An agent that reaches a defensible conclusion through unreconstructable steps has been trusted, not overseen.

    His recommendation to institutions is straightforward: human checkpoints should be first-class design requirements from the start, not compliance overlays retrofitted after a model works. Retrofitting is more expensive and less convincing to examiners. The institutions that manage this well will not necessarily have the most capable models; they will be the ones that can still answer the fundamental question: who decided, on what basis, and can they show it?

  • Sitharaman Calls AI a ‘Double-Edged Sword’ for Fintech, Urges Human Oversight and Smart Regulation

    Sitharaman Calls AI a ‘Double-Edged Sword’ for Fintech, Urges Human Oversight and Smart Regulation

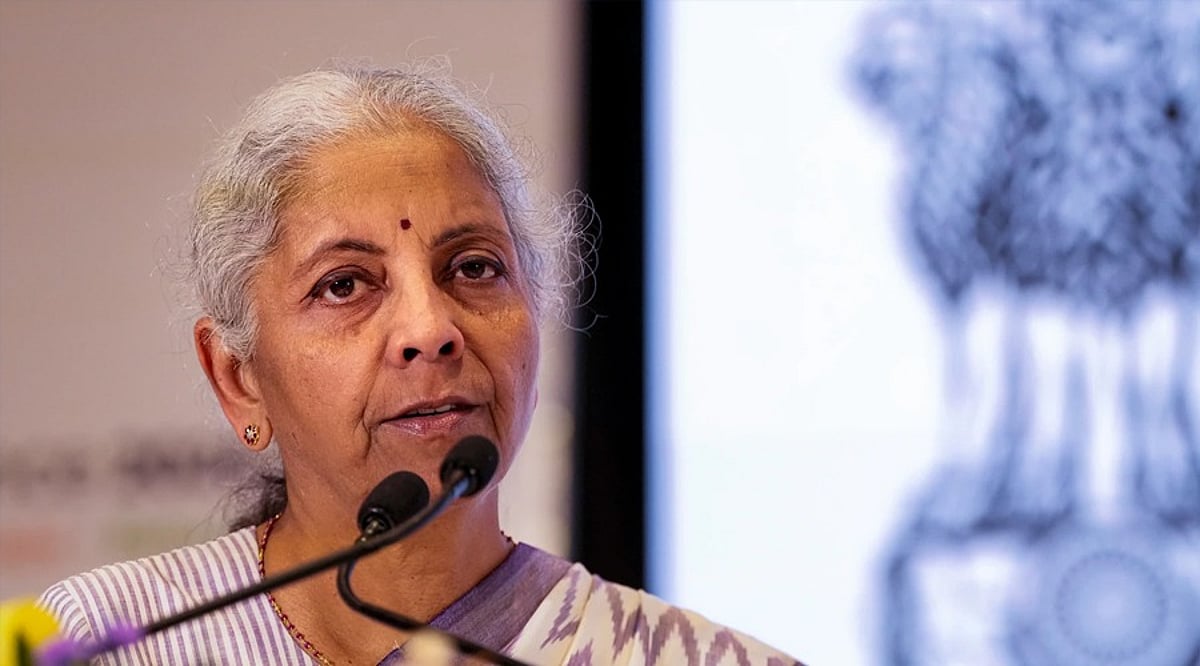
    Finance Minister Nirmala Sitharaman warned about the dual nature of artificial intelligence at the Global Fintech Fest 2026 in Mumbai, describing AI as a ‘double-edged sword’ that can both enhance and endanger financial systems. Speaking to a gathering of industry leaders, she highlighted the potential for AI to improve fraud detection and operational efficiency, but cautioned that the same technology could amplify cyber threats, systemic risks, and even influence public opinion and elections.

    Sitharaman emphasized that while AI can assist judgment, ultimate responsibility must remain with humans and institutions. She called for stronger oversight as financial firms increasingly rely on automated systems for fraud monitoring, risk assessment, and customer services. The minister argued that faster technology should not come at the cost of resilience in critical financial infrastructure.

    She advocated a ‘soft-touch regulation’ approach, developed in consultation with the Reserve Bank of India, aimed at fostering innovation without creating unnecessary barriers. Sitharaman welcomed the RBI’s recognition of the Unified FinTech Forum as a self-regulatory organization under its SRO-FT framework, noting that this reflects the evolving regulatory needs of India’s expanding fintech ecosystem.

    Higher-risk AI applications should face deeper scrutiny before deployment and throughout their lifecycle, she said, urging regulators, company boards, and senior executives to understand how these systems influence financial outcomes. The minister also proposed a federated industry platform to help Indian technology companies navigate cross-border rules on data, taxation, cybersecurity, and financial regulation.

    Sitharaman also called on the RBI to advance its wholesale and retail Central Bank Digital Currency pilots. Her broader message placed resilience alongside efficiency as a central requirement for India’s AI strategy, signaling that fintech companies will face greater expectations around accountability, cybersecurity, and responsible AI deployment.

    The Global Fintech Fest drew around 8,000 organizations, with technology-related entities accounting for 43% of participants and fintech firms representing another 20%. Sitharaman noted that young Indians are already building companies and shaping future economic growth, underscoring the importance of developing technology systems that can withstand failures and misuse.

  • Visa and ONDC Join Forces to Revolutionize Tourism Discovery in India

    Visa and ONDC Join Forces to Revolutionize Tourism Discovery in India

    Visa and the Open Network for Digital Commerce (ONDC) have announced plans to explore a collaboration aimed at enhancing tourism discovery and digital commerce in India. The announcement was made at the Global Fintech Festival 2026.

    The proposed partnership seeks to help travelers find destinations, tourism experiences, itineraries, and local businesses through digital channels. Visa and ONDC will assess how Visa’s digital commerce and discovery capabilities can integrate with ONDC’s open network infrastructure.

    Digital Tourism Discovery Network

    The initiative will focus on leveraging open network technology, trusted digital commerce, and digital tools to improve how travelers search for tourism services. The envisioned system could allow users to discover cities, attractions, travel plans, and businesses through connected digital services.

    Suresh Sethi, Visa Group Country Manager for India and South Asia, noted that open networks have become a vital part of India’s digital development. He emphasized that travelers increasingly expect digital tools to help plan journeys and find relevant experiences. “Tourism can be a very important asset where ONDC can serve as the digital infrastructure for tourism in the country,” Sethi said at the Global Fintech Festival 2026.

    Sethi also highlighted the growing use of digital agents to build travel plans and help users discover services. He suggested that a tourism network could bring together information about cities, travel itineraries, experiences, and small businesses in a connected digital system. “Everything related to tourism, whether discovering experiences, cities or travel itineraries, as well as small and medium businesses of the ecosystem can potentially be housed in one place,” he added.

    Connecting Travelers with Local Businesses

    ONDC views tourism as part of its broader mission to create digital markets for sellers while offering buyers more choices. The network already operates across sectors such as retail, financial services, and logistics.

    Hrushikesh Mehta, Chief Business Officer for Financial Services at ONDC, revealed that the network has processed over 500 million lifetime transactions. He explained that ONDC now sees tourism as another area where its open commerce model can connect buyers with service providers. “At ONDC, our North Star is creating markets for sellers and choice for buyers, whether it is in retail, financial services, logistics or tourism,” Mehta said.

    Mehta also noted that ONDC has received support from the Ministry of Tourism and Culture for its tourism track. However, he stressed the need for stronger participation from the demand side. “We are very keen to work with Visa to see what we can do together to make that happen and help connect travellers with the diverse experiences that India has to offer,” he stated.

    Expanding Access to India’s Tourism Services

    Under the proposed collaboration, Visa and ONDC will explore ways to connect travelers with tourism providers across different destinations and regions. They will also assess how digital discovery tools can make local tourism businesses more accessible.

    The approach could cover travel experiences, destination information, itineraries, and services offered by small and medium enterprises. It may also provide an additional digital channel for tourism operators participating in ONDC’s open network.

    Visa would contribute its digital commerce and discovery capabilities, while ONDC would provide its open network infrastructure. No launch date or detailed rollout plan has been announced yet. For now, the initiative remains in the exploration phase, with both organizations evaluating potential models for tourism discovery and digital commerce to serve domestic and international travelers across India.

  • NPCI Unveils UPI Tap & Pay and AI-Powered My UPI: What You Need to Know

    NPCI Unveils UPI Tap & Pay and AI-Powered My UPI: What You Need to Know

    The National Payments Corporation of India (NPCI) has rolled out two major upgrades to the Unified Payments Interface (UPI) ecosystem: UPI Tap & Pay for contactless transactions and My UPI, an AI-driven customer support platform. Announced at the Global Fintech Fest 2026, these features aim to make digital payments faster, simpler, and more secure.

    UPI Tap & Pay: Simplifying Everyday Transactions

    With UPI Tap & Pay, users can make payments at compatible point-of-sale (PoS) terminals simply by tapping their smartphone. No need to open a specific UPI app — just unlock your phone and tap. The feature leverages Near Field Communication (NFC) technology to connect with the payment terminal.

    Key details:

    • Supports UPI payments and RuPay credit cards on UPI.
    • Transactions up to Rs. 5,000 can be completed without entering a UPI PIN. For amounts above Rs. 5,000, PIN authentication is required.
    • Designed to eliminate multiple steps from the traditional scan-and-pay process, making small, frequent payments quicker.

    NPCI clarified that the Rs. 5,000 threshold applies specifically to the PIN-less Tap & Pay experience and should not be confused with other UPI transaction or wallet limits.

    My UPI: AI-Powered Unified Dashboard

    My UPI is an AI-powered customer support platform built on NPCI’s small language model, FiMI. It serves as a single-window interface for all UPI-related services, including:

    • Access to payment information across multiple apps and banking relationships.
    • Transaction support and security controls for rapid response to suspected fraud.

    The platform simplifies management of UPI services, reducing the need to jump between different banking apps.

    UPI’s Continued Growth

    The new features arrive as UPI processes record-breaking transaction volumes. In August 2026 alone, UPI handled 24.51 billion transactions worth Rs. 29.82 trillion, underscoring the need for faster, more intuitive payment tools.

    With Tap & Pay and My UPI, NPCI is positioning UPI to remain at the forefront of India’s digital payment revolution.

  • Mint Money Expands Fintech App with NPCI Bharat Connect Bill Payments

    Mint Money Expands Fintech App with NPCI Bharat Connect Bill Payments

    Mint Money, the fintech app from HT Media Group, has expanded its personal finance platform with a new bill payments feature powered by NPCI Bharat Connect. The announcement was made at Global Fintech Fest 2026 in Mumbai on September 10.

    Bill Payments, Reminders, and Auto Pay

    Through the new integration, users can track bills, receive reminders, make instant payments, and enable Auto Pay directly within the Mint Money app. Eligible transactions may also earn rewards, according to the company. The service is built on Bharat Connect, part of the NPCI-operated Bharat Bill Payment System (BBPS).

    Puneet Jain, CEO – Digital at HT Media Group, said the company designed Mint Money to combine financial information with services that support smarter financial decisions. “With Bill Payments, we are taking that mission into everyday money management,” Jain said.

    More Than Bill Payments

    The app continues to offer free credit score checks, personalized credit guidance, personal loan discovery, and credit card recommendations. Loan offers range from Rs. 5,000 to Rs. 20 lakh, with repayment tenures between six and 60 months. Depending on the borrower’s profile, annual percentage rates can range from 10.5% to 36%, with interest rates starting at 11% and processing fees from 1.5% to 5% of the loan amount.

    Eligible users may also see loan options of up to Rs. 5 lakh in about five minutes, subject to lender approval. An EMI and personal loan interest calculator helps users estimate costs before applying.

    AI Tools and Credit Features

    Mint Money also includes Credit Safe, which helps users assess whether a loan fits their financial situation, and Credit Score Builder, which provides personalized steps to understand and improve credit profiles. The app’s Money Guru AI coach answers common financial questions, while financial content from Mint remains available in the same platform.

    Mint Money said it plans to use the Hindustan Times Group’s content network, which reaches about one in four Indians, to bring its tools to users beyond major metropolitan areas. The new bill payments feature is available now in the app.