Tag: venture capital

  • How to Discover Recently Funded Startups in 2026: A Complete Guide for Investors and Professionals

    How to Discover Recently Funded Startups in 2026: A Complete Guide for Investors and Professionals

    In 2026, the startup ecosystem is moving at record speed. Funding announcements arrive daily across sectors like artificial intelligence, climate tech, fintech, healthcare, and enterprise software. For investors, recruiters, journalists, and business developers, tracking these newly funded companies is essential to spot emerging opportunities early. The most effective approach combines multiple sources rather than relying on a single database. This guide outlines the key strategies to find recently funded startups quickly and reliably.

    Why Tracking Funded Startups Matters

    A fresh funding round often signals a period of rapid growth. Startups typically expand their teams, launch new products, and enter new markets soon after raising capital. Sales teams can target expanding companies ahead of competitors, recruiters can identify hiring hotbeds, and investors can gauge sector momentum. Tracking funding also reveals broader economic trends—heavy investment in certain areas indicates where capital and innovation are flowing.

    Start with Dedicated Startup Databases

    Specialized intelligence platforms remain the backbone of funding research. Crunchbase, PitchBook, and Tracxn compile extensive data on funding rounds, investors, valuations, acquisitions, and leadership teams. These tools allow you to filter by funding stage, location, industry, amount raised, and announcement date. For example, you can find AI startups in India that secured seed capital or European fintech companies closing Series B rounds. While premium tiers offer deeper analytics, even free versions provide valuable insights into funding patterns.

    Follow Venture Capital Firms Closely

    Venture capital firms often announce investments before they appear in mainstream business news. Firms like Sequoia Capital, Accel, Lightspeed, Peak XV Partners, Andreessen Horowitz, and General Catalyst regularly share portfolio updates, founder interviews, and investment theses on their websites and social channels. Following these firms on LinkedIn and X (formerly Twitter) gives you an early look at startups that may soon gain wider attention. VC announcements also signal which sectors they believe will drive future growth.

    Monitor Business News and Startup Newsrooms

    Traditional business news outlets remain a vital source. Sites such as TechCrunch, Fortune, Bloomberg, CNBC, and regional startup publications cover funding news and M&A activity throughout the year. Journalists add context that databases lack—founder quotes, competitive positioning, and market analysis, helping you understand not just which companies raised money, but why. Industry newsletters have also become powerful tools, delivering curated funding round summaries directly to your inbox.

    Leverage Social Media as an Early Signal

    LinkedIn is one of the fastest channels for funding news. Entrepreneurs often announce investments alongside news about hiring, product launches, or expansion. Following key investors, founders, incubators, and venture capitalists can reveal opportunities before any official press release. X remains relevant for real-time updates, especially during startup conferences where funding announcements are made live.

    Watch Accelerators and Incubators

    Many high-growth startups secure institutional funding shortly after completing accelerator programs. Organizations like Y Combinator, Techstars, Antler, and university-backed incubators showcase promising companies during Demo Days. Monitoring these cohorts gives you a window into potential unicorns. Startups often raise seed or Series A rounds right after graduation, making accelerators a fertile ground for early discovery.

    Use AI-Powered Monitoring Tools

    Artificial intelligence has transformed startup research. AI-driven news aggregators, alert systems, and research assistants can scan thousands of sources simultaneously, filtering funding leads based on your keywords and criteria. You can set up notifications for specific sectors like AI, clean energy, healthcare, or cybersecurity, ensuring you never miss fresh funding news even in fast-moving fields.

    The Smartest Strategy: Combine Multiple Sources

    No single platform captures every funding announcement. Some startups debut their funding on LinkedIn, while others first appear on VC blogs or regional publications before hitting global databases. For the most complete picture, draw on startup databases, business journalism, social media, VC announcements, and AI alerts. This multi-source approach not only identifies newly funded companies but also provides richer context about industry trends, investor confidence, and emerging markets. In today’s competitive startup landscape, timely information is a strategic asset. Developing a systematic method for monitoring funding announcements pays dividends for any professional looking to stay ahead.
  • Regulatory Hurdles Slow India’s Startup Funding as VCs Tighten Scrutiny

    Regulatory Hurdles Slow India’s Startup Funding as VCs Tighten Scrutiny

    India’s startup ecosystem remains a vibrant hub for entrepreneurship, but the pace of venture capital investment has slowed as investors grow more selective amid regulatory uncertainty. Data shows a decline in private equity and venture capital funding, and experts warn that stricter digital policies could dampen long-term growth.

    VC Investments Decline in the Second Quarter

    According to current industry figures, private equity and venture capital (PE-VC) funding in India totaled $6.45 billion during the second quarter of 2026—3% less than a year ago and 42% below the previous quarter. This deceleration reflects increasing caution among investors, who now favor startups with sound business models and clear paths to profitability over rapid expansion.

    It is important to note that investor interest has not vanished. Instead, firms have tightened their due diligence processes and are concentrating on companies with strong fundamentals and reliable revenue streams.

    Regulatory Environment Adds to Investor Concerns

    Beyond funding challenges, policy uncertainty has emerged as a significant hurdle for India’s startup community. An analysis by Oxford Economics, commissioned by Digital Prosperity Asia (DPA), indicates that stricter digital industry regulations could reduce venture capital funding by up to 25% annually through 2035. This would also lead to fewer startups, jobs, and innovations.

    Industry representatives emphasize that predictable, innovation-friendly regulation is critical for entrepreneurs making long-term investment decisions.

    Source: Oxford Economics report commissioned by Digital Prosperity Asia (DPA).

    Capital Is Becoming More Selective

    Despite the funding slowdown, India remains one of the world’s largest startup ecosystems, with over 150,000 DPIIT-registered startups. Investments continue to flow into artificial intelligence, deep technology, healthcare, and enterprise software—but they are now driven by business fundamentals rather than growth potential alone.

    The current environment suggests that startups with strong governance and efficient capital allocation will find it easier to secure funding compared to those without.

    Long-Term Outlook Depends on Confidence

    While opportunities in India’s startup landscape remain plentiful, experts believe rebuilding investor trust will require stable regulations that nurture innovation. A balanced approach—protecting users while promoting entrepreneurship—could sustain India’s position as a leading startup nation.

    As investors become more selective, entrepreneurs must focus on profitability and operational efficiency to attract funding.

  • Why Boring Fintech Ideas Are Building the Next Unicorn Startups

    Why Boring Fintech Ideas Are Building the Next Unicorn Startups

    Fintech innovation is shifting from flashy consumer apps to essential financial infrastructure. Founders solving routine but critical challenges are building businesses with stronger revenue models, higher customer retention, and lasting competitive moats. These seemingly ordinary ideas could define the next generation of fintech unicorns.

    A Shift From Growth Stories to Infrastructure Bets

    Payment processing, banking data, expense management, and accounts payable rank among the least exciting categories in software. They also produce some of the largest private valuations in tech. Investors once rewarded growth at any cost. Now they reward recurring revenue, sticky customers, and infrastructure that businesses cannot easily rip out. Boring problems tend to score high on all three.

    Venture funding into fintech startups reached $51.8 billion in 2025, a 27% jump over 2024. A large share of that capital chased companies fixing operational chores rather than building flashy new consumer apps. A founder pitching a slicker banking app now competes for attention against a founder pitching a faster way to close the books, and the second group is winning more term sheets.

    Four Companies, Four Very Different Outcomes

    Stripe processes $1.9 trillion in annual payment volume and stays profitable, which lines up with its jump to a $159 billion valuation this year. Plaid took a rougher road. Its bank-data APIs still power thousands of fintech apps, but its valuation sits at $8 billion as of February 2026, down from a $13.4 billion peak in 2021.

    Ramp moved in the opposite direction. The expense-management platform rose to a $44 billion valuation in June 2026, nearly tripling in a year after adding AI-driven spend controls and crossing $1 billion in annualized revenue. Tipalti, which automates supplier payments across 190-plus countries, has held a valuation of nearly $8.3 billion since 2021, backed by $200 million in fresh debt financing last year.

    Then there is Brex. The corporate card company once matched Ramp’s valuation, peaking at $12.3 billion in 2022. Capital One bought it in April 2026 for $5.15 billion, well under half that peak. Brex shows that a boring, defensible niche is not a guarantee on its own. Ramp out-executed it on the same playing field, building software revenue and AI tooling while Brex leaned on card interchange. Boring fintech does not win by default. It wins when a team pairs an unglamorous problem with sharp execution.

    Why Switching Costs Beat Slick Design

    What ties the winners together is structural, not stylistic. Payment rails and payables systems sit deep inside a customer’s finance stack. Ripping one out means re-plumbing accounting, compliance and vendor relationships, so switching costs stay high long after the initial sale. Regulatory complexity works the same way: tax rules, anti-money laundering checks, cross-border compliance. It slows new entrants and rewards whoever has already cleared the paperwork. None of that shows up in a product demo, but it shows up in valuation charts.

    Scale reinforces the moat once a company clears that early complexity. Stripe now handles roughly 1.6% of global GDP in payment volume. Plaid connects more than 8,000 fintech apps to over 12,000 banks, a network effect a new entrant cannot easily replicate from scratch. Ramp serves more than 70,000 businesses and grew transaction volume by 170% year over year in early 2026, a pace that outstrips almost every consumer fintech app on the market. These are not viral products. They are systems that get embedded once and stay embedded for years.

    What This Means for the Next Wave of Founders

    Founders chasing the next fintech unicorn might learn more from an invoicing platform than from a crypto exchange. The formula favors teams that pick a specific, recurring financial pain point, build the compliance and integration work competitors will not bother with, and let switching costs do the defending. Speed still matters. Ramp climbed from a $13 billion valuation to $44 billion in just over a year by expanding beyond its original card product into a full spend management suite. Standing still in a boring category is still a losing move.

    Boring is not a strategy on its own. Stripe, Ramp, and Tipalti show that solving everyday financial problems with strong execution can build highly valuable businesses. Brex proves that the same category can just as easily produce a discounted exit. The next fintech unicorn will not announce itself with a flashy demo. It will look like a payment API, an expense dashboard, or a payables tool that quietly becomes impossible to remove.

    Final Thoughts

    The next fintech unicorn is unlikely to be built on hype alone. Startups that solve essential financial problems, execute consistently, and become deeply embedded in business operations will be better positioned to create lasting value and attract long-term investor confidence.

  • India’s Startup Ecosystem Enters a New Era: Prioritizing Profitability, Public Markets, and Deep-Tech Innovation

    India’s Startup Ecosystem Enters a New Era: Prioritizing Profitability, Public Markets, and Deep-Tech Innovation

    India’s startup ecosystem is entering a defining phase. The years of easy capital, rapid expansion, and soaring valuations have given way to a more measured approach. Investors are asking tougher questions, founders are focusing on sustainable growth, and public markets are emerging as a key source of capital.

    The shift marks a turning point for a sector that transformed India’s business landscape over the past decade. With more than 1.59 lakh DPIIT-recognized startups and over 1.66 million jobs created, the ecosystem remains one of the country’s strongest engines of innovation. The challenge now is not whether startups can grow, but whether they can build durable businesses while maintaining momentum.

    Why Profitability Has Become a New Benchmark

    Previously, success for startups was mostly measured by how many rounds of funding they managed to raise, and at what valuations. The whole idea was to push hard on customer acquisition and growth while ignoring profitability, or assuming it could come later. But now, the dynamics of success have shifted. Higher interest rates, greater investor caution, and a generally hard-edged funding environment have pushed startups to rethink what matters most. Just growing revenue isn’t enough anymore. Investors want clearer signals, such as solid unit economics, operational efficiency, and a path toward profitability.

    This shift is already visible in the Indian tech space. Many startups are either turning profitable or at least trimming losses, suggesting a more careful, disciplined approach to management.

    Public Markets Are Reshaping Startup Ambitions

    Another major change is the growing role of public markets. The IPO is now an option available to mature startups. Companies that relied heavily on venture capital funding in their early days are now raising capital through stock offerings on public exchanges. This brings a new level of accountability. The importance of sound governance, financial transparency, efficient cash flow management, and business sustainability outweighs the hype about growth in the public markets environment. Startup founders now focus on such matters much earlier than ever before.

    Beyond Bengaluru and Mumbai

    India’s entrepreneurial journey is no longer confined to a few metro cities. Young entrepreneurs from tier-II and tier-III cities are setting up companies across sectors such as fintech, logistics, healthcare, education, and more. Internet connectivity, digital payment systems, and access to an online workforce have significantly lowered barriers, even for those working outside traditional startup hubs. Smaller cities themselves have become emerging markets, as technology adoption rises and consumer spending power increases steadily. This geographic expansion has diversified the startup landscape in the country.

    Deep-Tech Emerges as the Next Frontier

    Consumer internet businesses dominated India’s startup ecosystem for much of the past decade. The next wave may come from deep-tech sectors. Firms engaged in artificial intelligence, semiconductor design, robotics, climate technology, space technology, and sophisticated software have become a major area of interest for investors. However, deep-tech firms face specific challenges: large sums of capital, long gestation periods, and specific talent requirements. Nevertheless, investors and policymakers recognize that India’s future economic success will depend on its capacity to develop innovative deep technologies.

    Challenges That Refuse to Disappear

    The ecosystem must not ignore its problems. Investments remain selective, especially for early-stage startups. Investors prefer startups with proven business models and revenue streams. Startups face a talent shortage, particularly in areas such as artificial intelligence, chip design, and advanced engineering. Some regulations could pose challenges, especially for startups without sufficient funds to comply. Uncertainty about the global economy adds yet another problem: slow growth in key markets could negatively impact investments and expansion.

    What Comes Next for Indian Startups

    The startup ecosystem in India is transitioning from its teenage phase to adulthood. The focus will shift from chasing valuations to building robust companies. Profitability will serve as a competitive advantage. Corporate governance systems are improving. Capital markets have opened new ways to raise money. Deep technology innovation leads to opportunities beyond consumer-facing offerings. The coming decade could witness more stable businesses rather than eye-catching funding rounds. It will be imperative for entrepreneurs to strike the right balance between innovation, financial prudence, scalability, and performance.

    This is a pivotal time for the Indian startup ecosystem. The decisions made by entrepreneurs and investors will determine whether India succeeds in nurturing future global leaders or falls short.

  • India vs Silicon Valley and China: How Its Startup Ecosystem Stacks Up

    India vs Silicon Valley and China: How Its Startup Ecosystem Stacks Up

    Three decades ago, the global startup conversation belonged almost entirely to Silicon Valley. Then China built its own parallel universe of billion-dollar companies, moving so fast that Western observers could barely track the names. Today, a third force is demanding attention. India has quietly assembled one of the most significant startup ecosystems in the world, and the comparison is no longer a stretch—it is a conversation worth having in full.

    The Scale Argument

    India currently ranks third globally in total number of unicorns, behind the United States and China. As of 2026, India has produced over 115 unicorn companies, with a combined valuation running into hundreds of billions of dollars. The sectors span fintech, edtech, healthtech, logistics, SaaS, and consumer internet, reflecting an ecosystem with genuine breadth rather than concentration in one or two categories.

    Silicon Valley remains the undisputed leader in raw numbers and total capital deployed. The US venture capital market continues to dwarf every other geography, and the Bay Area alone houses more unicorns than most countries combined. China, despite regulatory headwinds in recent years, maintains a deep pool of mature tech giants including Alibaba, Tencent, ByteDance, and Meituan—companies that have scaled globally and built product categories entirely from scratch. India has not yet produced a company of that global reach, but its trajectory is pointing upward, driven by structural rather than temporary conditions.

    The Capital Picture

    Funding is where the comparison gets interesting. Silicon Valley still attracts the largest share of global venture capital, supported by a decades-old investor network, deep institutional familiarity with tech risk, and proximity to the world’s largest technology companies. The exit ecosystem in the US—including acquisitions and IPOs—is far more mature, making it easier for early investors to deploy capital with confidence. China built its startup boom on a combination of domestic capital, state support, and an enormous consumer market. Platforms like WeChat Pay and Alipay created financial infrastructure that startups could build on without reinventing the wheel. However, the government’s relationship with the tech sector has grown complicated, with major regulatory crackdowns reshaping operations, though the underlying market scale remains.

    India faces a more volatile funding environment. After a peak in 2021 and 2022, funding dropped significantly through 2023 and 2024 before stabilising. The correction forced a reckoning with unit economics and profitability—a healthy development. Indian startups that survived the funding winter did so by building leaner, more sustainable businesses. Several high-profile IPOs, including Zomato, Nykaa, and Paytm, have tested public market appetite for new-age tech companies, with mixed but instructive results.

    The Talent Engine

    Talent is one area where India holds a genuine structural advantage. The country produces millions of engineering graduates each year, and the quality at the top tier is internationally competitive. Indian-origin founders and executives hold leadership positions at some of the world’s most valuable technology companies, including Google, Microsoft, Adobe, and IBM. Silicon Valley has long benefited from Indian talent through immigration, but India itself is now keeping more of its best engineers and founders at home. Return migration is rising—experienced professionals who built careers in the US are coming back to build companies in India, bringing capital networks, product experience, and global market exposure.

    China’s talent pool is massive and technically strong, but increasingly insular. Export controls, geopolitical tensions, and restrictions on cross-border data flows have made it harder for Chinese tech companies to attract and retain international talent. India, by contrast, operates in English, follows common law, and maintains open capital account policies for foreign investors, all of which lower friction for international engagement.

    The Market Dynamics

    India’s domestic market is its most compelling long-term asset. With 1.4 billion people, a rapidly expanding middle class, and growing smartphone penetration in tier-two and tier-three cities, the addressable market for consumer technology is enormous and still largely untapped. Silicon Valley startups typically build for a global audience from day one, using the US as a launch market and expanding outward. Indian startups have historically built for India first, creating depth and defensibility but sometimes limiting global ambition. That is changing: Indian SaaS companies like Freshworks, Zoho, and Browserstack have built significant international revenue bases, proving the model works beyond domestic borders.

    China built its internet economy behind the Great Firewall, which had a paradoxical effect. It protected domestic companies from foreign competition and allowed them to scale without facing Google or Amazon. But it also cut them off from global markets in meaningful ways. Indian startups face full international competition at home, which forces sharper product thinking and validates their capabilities when they expand abroad.

    The Infrastructure Gap

    One honest limitation India must acknowledge is infrastructure. Silicon Valley benefits from world-class physical and digital infrastructure built over decades. China made infrastructure a national priority and executed at a speed and scale few countries can match—from high-speed rail to 5G networks to digital payment systems. India’s infrastructure story is improving but uneven. The Unified Payments Interface has become a genuine success, processing billions of transactions monthly and inspiring similar systems in other countries. Digital public infrastructure, including Aadhaar and the Open Network for Digital Commerce, is creating platforms on which startups can build. However, logistics, power supply, and connectivity outside major urban centres remain real constraints for companies trying to reach the full breadth of the Indian market.

    Where India Is Heading

    The most accurate assessment of India’s startup ecosystem is this: it is real, it is growing, and it is building on foundations that are durable. The comparison with Silicon Valley is premature in terms of capital depth and global company creation. The comparison with China is more nuanced—India holds advantages in global integration and English-language capability while China retains advantages in domestic market maturity and state-backed infrastructure.

    What India has built is a third model, one driven by a large domestic market, a strong talent base, a democratic regulatory environment, and an increasingly experienced investor class. The country does not need to replicate Silicon Valley or China to matter. Building its own version, at its own pace, on its own terms, is already changing the global startup conversation.

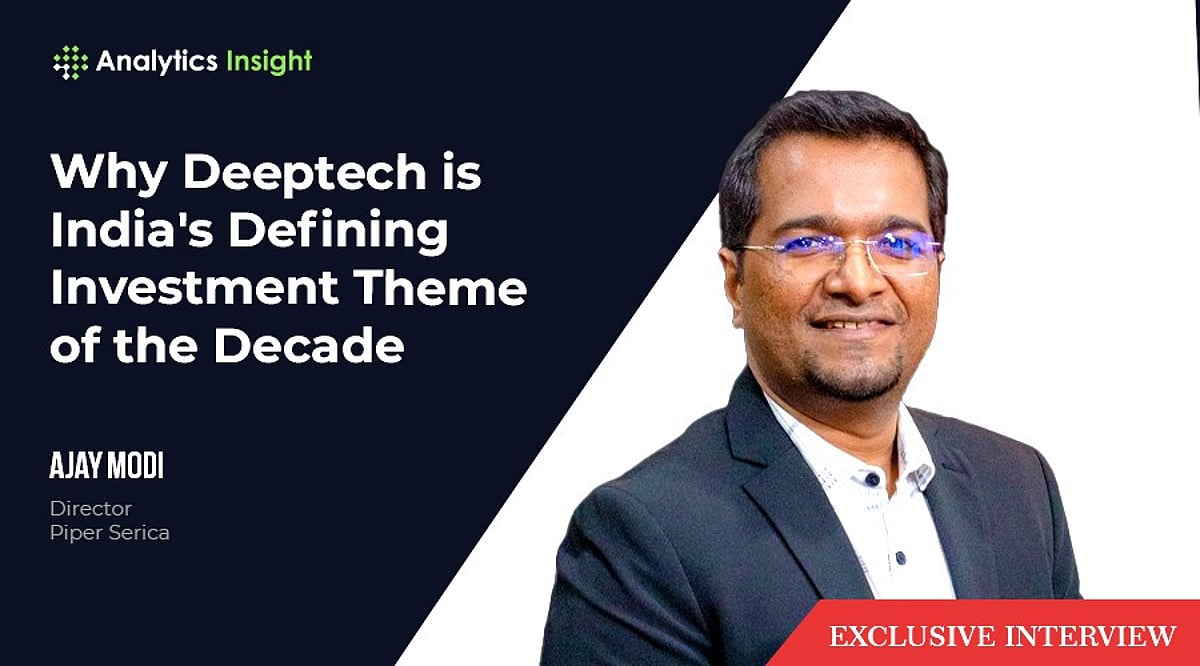
  • Why India’s Next Startup Wave Is Hidden in Supply Chains: Piper Serica’s Ajay Modi on Deeptech Investing

    Why India’s Next Startup Wave Is Hidden in Supply Chains: Piper Serica’s Ajay Modi on Deeptech Investing

    India’s venture capital story is being rewritten. The capital that once chased consumer internet growth at any cost is now flowing toward deep engineering, sovereign technology, and industrial capability. Ajay Modi, Director at Piper Serica, has been at the center of this shift. His firm’s portfolio spans laser space communication, edge AI chips, underwater robotics, airport operating systems, and India’s first resonance-based rocket ignition system.

    In this exclusive conversation with Analytics Insight, Modi breaks down why deeptech has become the defining investment theme of India’s next economic cycle and what it takes to build companies that matter inside strategic industries.

    How Venture Capital Priorities Are Evolving in India

    Indian tech startups raised about $7.4 billion in 2024, up 23 percent from 2023, with deeptech alone drawing around $1.6 billion and growing roughly 78 percent in a year. Nasscom and Zinnov now count more than 4,000 deeptech startups within a base of 32,000–35,000 tech ventures.

    Piper Serica’s Fund I has backed over 33 companies across deeptech, spacetech, defence, semiconductors, fintech infrastructure, and mobility. Newer deals concentrate in IP-led hardware, firmware, and system software. First founder meetings now open with orbit plans, chip architectures, or reliability data—not only GMV charts.

    This shift follows a reset after the 2020–2021 liquidity cycle, when capital largely chased consumer internet businesses that scaled fast on subsidies and marketing. Investors saw that scale without defensible capability created fragile companies once acquisition costs rose and capital tightened. Deeptech has become a clear winner from this correction.

    What Drives Interest in Spacetech, Semiconductors, Robotics, Defence, and Precision Manufacturing?

    Investor interest in these sectors rises where three lines meet: national policy support, large end demand, and a rewiring of global supply chains. India’s space economy stands near $8–8.5 billion and targets $40–45 billion by the early 2030s. More than 400 space startups have attracted over $500 million. In semiconductors and electronics, the Semicon India and component PLI stack targets around $300 billion of electronics output with deeper local value addition.

    On the talent side, founders now come from ISRO, DRDO, global chip companies, and top IIT labs. Piper Serica’s portfolio reflects this mix across spacetech, chip design, mobility electronics, cyber security, and industrial software.

    How India’s Manufacturing and Self-Reliance Push Shapes VC Decisions

    Electronics output in India has grown from about $10 billion in 2014 to roughly $115 billion today. Local factories now meet close to $110 billion of the $140 billion of domestic demand. Programmes like iDEX and IN-SPACe’s Technology Adoption Fund lower early revenue risk and lengthen runway for hardware and industrial companies.

    Piper Serica now treats such programs almost like demand pipelines. For venture investors, capital is shifting from funding user acquisition to funding companies that can become long-term infrastructure layers inside strategic industries.

    Opportunities in Aviation, Infrastructure, Electronics Systems, and Advanced Industrial Tech

    The next three to five years can be India’s most important industrial buildout in decades. In aviation, real value will sit in software and airport tech. At Chennai airport, Piper Serica’s portfolio company Blunav cut runway occupancy time by 22 percent across more than 3,500 flights. Electronics systems offer a second wave, while robotics, industrial AI, and autonomous inspection represent a third wave. The most valuable companies may be those hidden inside supply chains, compounding quietly through efficiency.

    How Evaluation Frameworks Differ for Industrial and Deeptech vs. Consumer

    Consumer investing focuses on speed and metrics like CAC, retention, and growth rate. Tech investing is engineering-led—investors test whether the core system works, is defensible, and runs reliably in demanding real-world settings. Diligence goes into IP strength, field reliability, manufacturing repeatability, regulatory paths, certifications, and integration risk. Timelines differ: consumer products can ship in weeks; deeptech teams may spend years hardening hardware and software. Competitive moats come from engineering depth and long contracts embedded inside customer operations.

    Technology Depth and Industrial Relevance Over Scale-Focused Growth

    India’s “easy growth” phase is over. Profitability, resilience, and defensibility sit at the centre of investment debates. Thrustworks Dynetics, a Piper Serica portfolio company, test-fired India’s first resonance-based rocket ignition system with only about ₹7 crore of seed funding—a sharp example of deep hardware success. Scale still matters, but the most sought-after companies now pair scale with hard engineering, proprietary systems, and real industrial relevance.