Category: Economics

  • The Key Factors Behind Natural Gas Prices: Weather, Storage, and LNG Exports

    The Key Factors Behind Natural Gas Prices: Weather, Storage, and LNG Exports

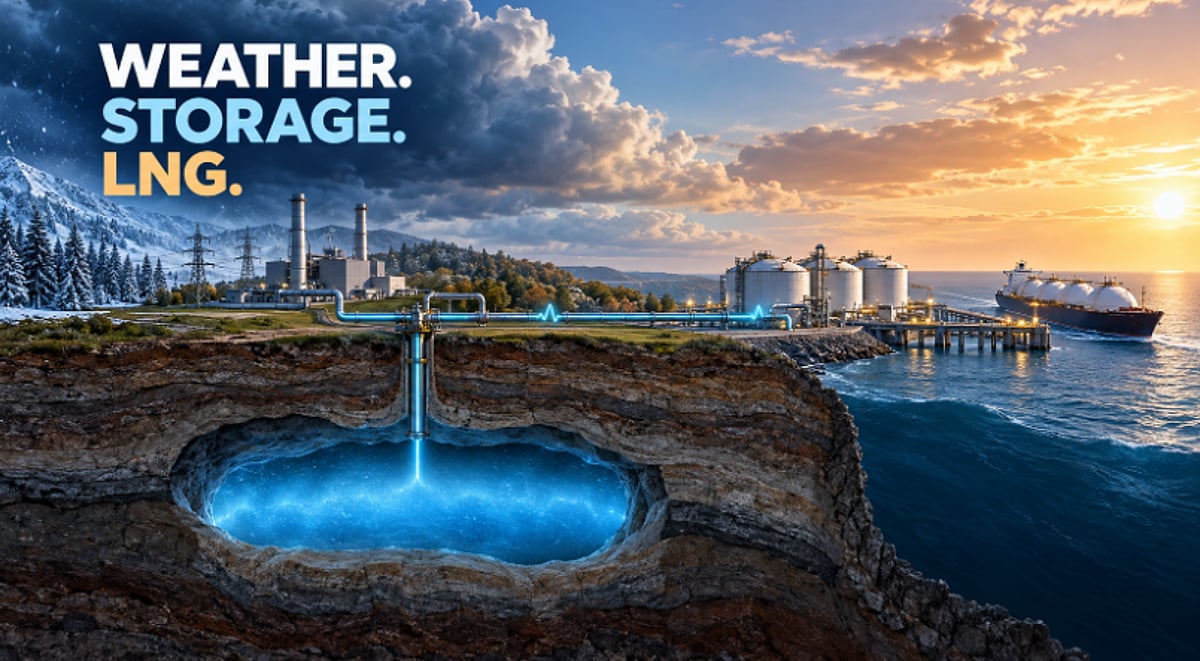
    Natural gas prices are shaped by a complex mix of weather patterns, storage levels, and LNG export demand. Understanding how these forces interact helps businesses and traders anticipate market movements and make informed decisions.

    Weather’s Immediate Impact on Demand

    Weather conditions directly affect natural gas demand. Cold spells increase heating needs, while heatwaves drive up electricity demand for air conditioning, which often relies on gas-fired power plants. Traders closely monitor weather forecasts, and even slight changes in predicted temperatures can cause price fluctuations before the actual weather arrives. The location of weather events matters too: a cold snap near a pipeline bottleneck can create local shortages even if other regions have ample supply.

    Storage as a Market Buffer

    Natural gas storage facilities provide a cushion against seasonal demand variations. However, the effectiveness of this buffer depends on storage capacity and deliverability rates. A large inventory is less useful if it cannot be withdrawn quickly enough to meet sudden demand spikes. Weekly storage reports are evaluated against market expectations: a withdrawal that seems large may actually be smaller than anticipated, leading to price drops, while a modest withdrawal can boost prices if the market expected an injection. Comparisons with historical norms are crucial for assessing market tightness.

    LNG Exports Link Domestic and Global Markets

    LNG terminals act as large consumers of natural gas. Increased export demand tightens domestic supply, while outages can free up gas for local use. Global events, such as a cold winter in Asia or European storage rebuilding, can influence US prices through competition for LNG cargoes. According to the International Energy Agency’s Q1 2026 review, global LNG production increased by nearly 7% in 2025, with three-quarters of that growth occurring in the second half. The correlation between European and Asian benchmark prices reached 0.955, highlighting the strong linkage between markets.

    Navigating Conflicting Signals

    Market analysis becomes challenging when indicators point in different directions. A cold forecast may support higher prices, but a mild storage report could limit gains. Timing differences between weather forecasts, storage data, and LNG flows add complexity. A comprehensive approach considers scenarios rather than a single prediction.

    Building a Practical Forecast

    Effective price forecasts rely on scenario analysis. By considering various combinations of weather, storage, and export conditions, businesses can prepare for different outcomes. Monitoring changes in underlying assumptions is more valuable than focusing solely on price targets. Regional pipeline conditions also deserve attention, as local shortages can occur even in a balanced national market.

    In conclusion, the interplay of weather, storage, and LNG exports creates a dynamic environment for natural gas prices. Recognizing how these forces interact allows market participants to develop more resilient strategies.
  • AI-Driven Export Boom Propels Taiwan’s Trade Surplus Toward $205.4 Billion

    AI-Driven Export Boom Propels Taiwan’s Trade Surplus Toward $205.4 Billion

    Taiwan’s central bank projects that the island’s trade surplus could reach a record $205.4 billion this year, fueled by a rapid expansion in artificial intelligence hardware manufacturing. This would be more than four times the $49.2 billion surplus recorded in 2018, when the US-China tariff dispute began.

    Taiwan Emerges as Key AI Manufacturing Hub

    The surge is closely tied to US efforts to build supply chains independent of China. Taiwan is becoming a critical node in the global AI supply chain, exporting servers and advanced semiconductors to the US while importing memory chips from South Korea and wafer fabrication equipment from Japan. Medium- and low-tech manufacturing is increasingly outsourced to ASEAN countries.

    The US trade deficit is expected to exceed $1.1 trillion, with Taiwan projected to become its third-largest source at $219.2 billion, behind Vietnam ($238 billion) and Mexico ($221 billion), and ahead of China ($156.4 billion).

    Electronics Manufacturing Shifts Away from China

    Taiwan’s electronics industry is moving away from the old model of producing goods in China for US markets. Instead, Taiwan now focuses on high-value, tariffed, and cybersecurity-sensitive products, while lower-tech assembly moves to the US or ASEAN. The share of locally produced exports hit a record 52.9% last year, up from 47.6% in 2018, while China’s share fell to 26.2%, down from 46.9%.

    Investment Flows Redirected to the US

    Taiwanese investment in China is declining as companies reassess strategies amid higher costs and geopolitical risks. The cumulative direct investment ratio in China dropped from 58.3% in 2017 to 18.8% from 2018 onward. Meanwhile, the US has become Taiwan’s most important investment destination, with the ratio rising to 18.7%. In 2023 and 2024, investment directed to the US accounted for 36.4% and 29.1% respectively, highlighting a broader shift toward the US, Japan, and Southeast Asia.

    These trends underscore Taiwan’s central role in the global AI supply chain and the ongoing realignment of manufacturing and investment flows away from China.

  • US 30-Year Bond Yield Reaches Highest Level Since 2004 Amid Sustained Selloff

    US 30-Year Bond Yield Reaches Highest Level Since 2004 Amid Sustained Selloff

    Overview

    The 30-year US Treasury yield climbed to 5.444% on Thursday, marking its highest level since 2004. The rise came as persistent selling pressure in global bond markets, combined with stronger-than-expected US economic data, renewed fears of inflation and further interest rate hikes by the Federal Reserve.

    The 10-year Treasury yield also rose, reaching 5.145%. Bond prices move inversely to yields, so the increase reflects continued weakness in Treasury prices.

    Strong US Data Fuels Rate Hike Bets

    The yield surge followed better-than-expected US economic figures. The S&P Global Purchasing Managers’ Index for services climbed to 58.7 in September from 56.5 in August, the highest level in nearly five years. The Manufacturing PMI also rose to 56.7, the highest in more than four years.

    According to market estimates, the Federal Reserve now has a 66% chance of raising interest rates in October, up from 53% earlier in the day. Just one month ago, the probability stood at less than 10%. The Fed increased rates during the previous week for the first time since 2023.

    Global Bond Markets Remain Under Pressure

    The pressure extends beyond US Treasuries. Bond markets worldwide have faced selling pressure for months due to higher energy prices, resilient economic growth, and concerns about elevated government debt. The US-Israeli war on Iran has pushed up energy prices, adding another source of inflationary pressure.

    Investors are closely watching Treasury auctions after a weak five-year note auction on Wednesday. The seven-year note auction later Thursday was expected to provide further clues about investor demand. The two-year US Treasury yield fell 1.8 basis points to 4.877%, while the gap between two- and 10-year yields stood at a positive 24.7 basis points.

    Jefferies chief US economist Thomas Simons noted that the long end of the Treasury market was ‘trading a bit better’ as investors assessed the latest moves.

  • India’s 7.8% GDP Growth and the 3,300-Point Sensex Drop: Understanding the Disconnect

    India’s 7.8% GDP Growth and the 3,300-Point Sensex Drop: Understanding the Disconnect

    India’s economy grew at a robust 7.8% in the first quarter of fiscal year 2027, but the stock market failed to celebrate. The Sensex, India’s benchmark equity index, lost approximately 3,300 points since August 31, and the Nifty 50 shed nearly 1,000 points. The sharp divergence between macroeconomic strength and market performance has left many investors puzzled.

    According to the Ministry of Statistics and Program Implementation, the Q1 FY27 GDP data was released on August 31. On that day, the Sensex closed at 76,957 and the Nifty at 24,080. By the morning of September 25, the Sensex had fallen to around 73,675 and the Nifty to about 23,075.

    Seema Srivastava, Senior Research Analyst at SMC Global Securities, attributed the market correction to three major factors: global macro pressure, crude oil and currency stress, and premium valuations combined with domestic sector pressures.

    Global Macro Pressure

    Rising US Treasury yields have made dollar-denominated assets more attractive, prompting global investors to shift funds away from emerging markets like India. This “risk-off” environment has created sustained liquidity pressure on Indian equities.

    Crude Oil and Currency Stress

    Geopolitical tensions have pushed crude oil prices higher. As a major importer of crude, India faces increased inflation and external balance pressures. A weakening rupee further raises the cost of dollar-denominated energy imports, adding to the strain.

    Premium Valuations and Domestic Sector Pressures

    Corporate earnings expectations have been hit across several key sectors. IT companies are contending with softer Western technology spending, while banks and non-banking financial companies (NBFCs) face higher funding costs. Additionally, investors have been booking profits after strong rallies, especially in stocks where valuations appeared stretched.

    “The market reacted to the classic ‘buy the rumour, sell the news’ dynamic,” Srivastava said, noting that institutional desks trimmed positions following the GDP announcement.

    The market’s response underscores a key distinction: GDP measures recent economic activity, but equities continuously price future earnings, liquidity, and global risk. Analysts expect volatility to persist, linked to crude prices, bond yields, currency movements, and foreign capital flows.

  • S&P Global Ratings Upgrades India’s FY27 GDP Forecast to 7%; RBI Rate Hike Expected

    S&P Global Ratings Upgrades India’s FY27 GDP Forecast to 7%; RBI Rate Hike Expected

    S&P Global Ratings raised India’s GDP growth forecast for fiscal year 2027 (FY27) to 7% on September 23, 2026, up from the previous estimate of 6.6%. The upgrade reflects stronger-than-expected economic activity, driven by robust consumption, industrial output, goods exports, and government investment.

    The ratings agency also expects the Reserve Bank of India (RBI) to implement a 25-basis-point rate hike during FY27, citing persistent inflation pressures and strong growth momentum. India recorded 7.8% growth in the June quarter, supporting the upward revision.

    S&P forecasts consumer inflation to average 5.1% in FY27, which could influence the RBI’s monetary policy. The agency noted that the balance of considerations is shifting toward higher interest rates, with risks from West Asia tensions and weather conditions adding to the outlook.

    Weather remains a concern, as cumulative rainfall stood 15% below normal through early September, potentially pressuring agricultural output and food inflation. Higher energy prices could further strain the rupee and inflation.

    The latest S&P forecast is above the RBI’s own projection of 6.7% and Fitch Ratings’ estimate of 6.4%, but aligns with Moody’s expectation of 7% growth for India in FY27. Looking ahead, S&P expects India’s growth to reach 7.2% in FY28 before easing to 7% in FY29, with domestic consumption and investment remaining central to the trajectory.

  • Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Brent and WTI Hold Above $100

    Global oil prices slipped about 1% on Friday, September 18, marking a third consecutive session of declines. Brent crude futures fell $1.01 to $103.77 a barrel, while West Texas Intermediate dropped $1.03 to $100.88. Both benchmarks stayed above the $100 level after closing roughly 1% lower on Thursday.

    Saudi Pipeline Disruption and Market Response

    Earlier in the week, prices reached four-month highs after crude loadings at Saudi Arabia’s Yanbu Red Sea export hub were suspended. An attack on Saudi Arabia’s East-West pipeline damaged three pumping stations, according to satellite imagery and industry sources, and prompted Riyadh to cancel some deliveries to Europe.

    Traders warned that a prolonged shutdown could remove as much as 4% of global supply. However, Saudi Arabia is now working to restore about half of the pipeline’s capacity within days and is offering additional crude cargoes to Asian refiners through ship-to-ship transfers off Oman’s Sohar port. US Energy Secretary Chris Wright said crude should begin flowing through the pipeline within days, helping to ease immediate supply fears.

    Geopolitical Risks Remain

    The market largely shrugged off fresh cross-border strikes between Saudi Arabia and Yemen’s Iran-backed Houthis on Thursday. At the same time, Iran’s Revolutionary Guards Navy reported that a Togo-flagged oil tanker was struck while attempting an ‘illegal passage’ through the Strait of Hormuz, adding to uncertainty in an already fragile market.

    Analysts Cautious on Outlook

    JPMorgan said it had no clear baseline view for oil markets for the first time since the start of the US-Israeli war on Iran. Peace talks between the US and Iran have not resumed since an interim agreement collapsed in June. The conflict is expected to be discussed at the UN General Assembly next week, with an Iranian delegation scheduled to attend.

    What to Watch

    Market attention now centers on whether Saudi Arabia can restore disrupted pipeline flows and reroute enough crude to limit the impact of the attack. Any delay in repairs or new escalation in the Middle East could quickly reverse the recent downward move in prices.

  • UK Inflation Reaches 3.1% in August as Fuel Costs Surge Ahead of Bank of England Rate Decision

    UK Inflation Reaches 3.1% in August as Fuel Costs Surge Ahead of Bank of England Rate Decision

    UK inflation climbed to 3.1% in August, up from 2.9% in July, marking its highest level in five months. The increase, driven by higher petrol, diesel, and airfare prices, matched economists’ forecasts and came just one day before the Bank of England’s (BoE) September policy meeting.

    Fuel Prices Drive August Inflation Higher

    The Office for National Statistics (ONS) reported that transport made the largest upward contribution to the annual inflation rate. Motor fuel prices rose sharply, with petrol increasing by 9.1 pence per litre between July and August, while diesel prices climbed by 14.2 pence per litre over the same period.

    Grant Fitzner, chief economist at the ONS, said: “Sharp price rises for petrol and diesel pushed inflation up again in August.” He added that higher long-haul airfares also contributed. Crude oil and fuel costs further raised manufacturers’ raw material and factory-gate prices.

    Core and Services Inflation Remain Stable

    Despite the headline rise, measures closely watched by the Bank of England held steady. Core CPI, which excludes energy, food, alcohol, and tobacco, remained at 2.6% for the fourth consecutive month. Services inflation also stayed at 3.4%.

    Neither measure accelerated in August, even as fuel costs pushed the headline rate above 3%. ONS labour data released earlier in the week showed regular pay growth at 3.5% in the three months to July, close to its weakest pace since 2020.

    Bank of England Prepares for Rate Decision

    The Bank of England will announce its interest-rate decision on September 17. Bank Rate currently stands at 3.75% after the Monetary Policy Committee (MPC) voted 6-3 in July to keep borrowing costs unchanged. Three members had supported a quarter-point increase to 4%.

    Financial markets were pricing in about a 20% chance of a quarter-point increase at the September meeting, according to Reuters. Charlotte O’Leary of the National Institute of Economic and Social Research said: “With limited evidence of second-round effects so far, we expect the MPC to hold rates tomorrow.” The BoE has identified energy prices as a key risk to inflation.

    At its July meeting, the Bank noted that energy prices had remained volatile since the Middle East conflict began. It stated that policy would depend on the scale, duration, and wider transmission of the energy shock.

    Producer Prices Add Pressure to Outlook

    Price pressures were stronger at the manufacturing level. Producer input prices rose 6.1% in the year to August, up from a revised 5.8% in July. Factory-gate output prices increased 3.7%, compared with a revised 3.3% increase a month earlier.

    The rise in inflation also comes as Prime Minister Andy Burnham’s government prepares for an October 28 budget. Chancellor John Healey said the Middle East war was affecting inflation across countries, feeding into household bills, shopping costs, and fuel prices. Official records show Burnham became prime minister on July 20, with Healey taking over as chancellor on the same date.

    Further increases in household energy bills could push headline inflation higher in the coming months because regulated domestic prices respond to wholesale energy costs with a delay. Goldman Sachs expects UK inflation to peak at 3.9% in early 2027. The BoE’s 2% inflation target remains the benchmark, while policymakers continue to track wages, services prices, and business costs for signs of pressure.

  • Oil Prices Surge Above $100, Fueling UK Inflation Concerns Ahead of Bank of England Rate Decision

    Oil Prices Surge Above $100, Fueling UK Inflation Concerns Ahead of Bank of England Rate Decision

    Oil prices climbed above $100 per barrel on Monday as Middle East attacks, Saudi pipeline disruptions, and shipping risks raised supply concerns. The surge has revived speculation that the Bank of England could raise interest rates later this year as higher energy costs add to UK inflation pressures.

    Oil Prices Rise as Saudi Pipeline Remains Shut

    Brent crude futures rose about 2.8% to $107.54 a barrel in early Monday trading, while West Texas Intermediate gained 2.9% to $102.93. Both benchmarks remained above $100 after oil gained about 8% last week. Saudi Arabia temporarily shut its East-West Pipeline after a drone attack. The route carries crude from the Arabian Gulf to the Red Sea port of Yanbu and allows Saudi exports to avoid the Strait of Hormuz. Industry sources said the outage could place up to 4% of global oil supply at risk if the pipeline stays offline.

    Shipping Risks Grow Around Hormuz and Bab el-Mandeb

    Tensions also rose around the Strait of Hormuz after a projectile struck a vessel on Sunday. The UK Maritime Trade Operations said the incident caused a fire and forced the crew to abandon the ship. Iranian authorities later said an unidentified munition hit an Iranian commercial vessel off the country’s coast. Meanwhile, Houthi forces reached Perim Island near the Bab el-Mandeb Strait, another major oil transit route, adding concern over shipping through the Red Sea. Omani Foreign Minister Badr Albusaidi announced the postponement of planned talks between Gulf states and Iran, reducing expectations of an immediate agreement on Hormuz shipping.

    Oil Surge Revives Bank of England Rate Hike Debate

    Higher oil prices have changed expectations for UK interest rates in financial markets. The Bank of England will announce its next policy decision on September 17. The bank rate currently stands at 3.75%, and the central bank has kept it unchanged since the conflict in the Middle East began earlier this year. The bank’s July meeting ended with a 6-3 vote to keep rates unchanged, while three members supported a quarter-point increase to 4%. Since then, energy prices have risen further. Markets now see a greater chance of a rate increase later this year, although a September move is still not the main expectation.

    Bailey Says Future Rate Moves Are Not Certain

    Bank of England Governor Andrew Bailey has cautioned against treating a rate increase as guaranteed. He told lawmakers that he wanted to dispel the idea that policymakers had a ‘secret plan’ for rates. He said future decisions would depend on economic data and events in the Middle East. Bailey also said market pricing included a risk premium linked to concerns about further energy price increases. At the same time, MPC member Megan Greene has raised concern that a longer oil shock could keep inflation expectations elevated. Traders will now watch UK inflation, labour market data, and oil prices before the September 17 decision.

    The outlook for crude prices remains closely tied to the East-West Pipeline, shipping security, and regional diplomacy. ING strategists said it was ‘unclear how severe any potential damage was’ to the Saudi pipeline. A faster restart or renewed Gulf-Iran talks could reduce supply concerns, while further disruptions could keep oil prices elevated.

  • How Solo Entrepreneurs and Small Partnerships Are Driving India’s Record Business Registrations in 2026

    How Solo Entrepreneurs and Small Partnerships Are Driving India’s Record Business Registrations in 2026

    India’s business registration data for 2026 reveals a clear shift in who is starting companies. One Person Companies (OPCs) and Limited Liability Partnerships (LLPs) have seen dramatic growth, and this surge is not coming from the typical venture-funded startup ecosystem. Instead, solo founders and small professional partnerships are formalizing their operations at an unprecedented rate.

    Two Structures, Two Different Audiences

    OPCs and LLPs serve distinct purposes. An OPC is designed for a single founder—a consultant, freelancer, or product builder who wants limited liability and a corporate identity without needing a co-founder to meet minimum shareholder rules. An LLP, on the other hand, suits two or more partners—often professionals like chartered accountants, lawyers, or small consultancies—who seek liability protection without issuing equity or reporting to a board.

    Both structures are now rising rapidly, driven by the same underlying trend: more entrepreneurs are choosing to formalize early rather than operating informally as proprietorships. According to Ministry of Corporate Affairs (MCA) data, roughly 6,281 OPCs were incorporated by mid-2025, a 26% increase year-on-year. LLP registrations jumped even more, from 61,769 to 86,476—a 40% rise in the 2025-26 period.

    Between January and April 2026 alone, India logged 1.31 lakh new business registrations across all entity types. Private limited companies still led with 85,560, but LLPs followed closely at 39,774, accounting for nearly 30% of all filings during that window. OPC numbers are smaller in absolute terms but are growing at a similar pace.

    Why OPC Registration Became More Attractive

    OPCs used to carry a major limitation: crossing ₹50 lakh in paid-up capital or ₹2 crore in turnover forced automatic conversion into a private limited company within six months. The 2021 amendment to the Companies (Incorporation) Rules removed that trigger. Now an OPC can scale its capital and revenue without being forced to change structure.

    The residency requirement also eased. Any Indian citizen can incorporate an OPC directly, and the minimum days spent in India dropped from 182 to 120. Combined with the fully online SPICe+ process—typically completed in 7 to 10 working days—OPC registration is no longer a niche option. Many solo founders now choose it as their first choice.

    Why LLPs Are Growing Even Faster

    LLPs appeal because of lower compliance costs. A private limited company must undergo a statutory audit every year regardless of turnover, plus hold board meetings and file detailed ROC reports. An LLP only needs an audit once turnover exceeds ₹40 lakh or partner contribution surpasses ₹25 lakh. Below those thresholds, annual filings are mostly limited to Form 8 and Form 11.

    For a two- or three-partner professional firm not seeking institutional funding, that compliance gap adds up significantly over time. This is a major reason LLP filings have outpaced overall registration growth this year.

    What Neither Structure Can Do

    Both OPCs and LLPs share a critical limitation: they cannot issue equity shares. That means no stock for investors and no ESOP pool. Founders chasing venture capital still default to private limited registration regardless of team size. Converting an OPC or LLP into a private limited company later is possible but requires NCLT approval, time, and expense. Founders who expect to need outside funding within a few years typically skip the detour entirely.

    The Bigger Picture

    India’s overall company registration numbers are running well above historical norms in 2026. The rise in OPC and LLP registrations reflects a specific shift: more solo founders and small professional partnerships are formalizing early instead of waiting until they outgrow a proprietorship. Neither structure is replacing private limited registration at the top of the funnel; they are filling a gap that private limited was never designed to address.

  • India’s Next Industrial Boom: Six Sectors Powering a New Technology Economy

    India’s Next Industrial Boom: Six Sectors Powering a New Technology Economy

    India’s Technology Economy Takes Shape

    India is undergoing a major transformation in how it builds and uses technology. According to a recent Jefferies report, six key industries are driving this shift: semiconductors, electronics, space, data centers, solar equipment, and aerospace.

    The numbers underline the momentum. India’s space industry has grown fivefold and is projected to reach USD 40-45 billion by 2030. Semiconductor investments have hit around USD 20 billion, with an additional USD 13 billion incentive plan in the works. Data centers have also seen explosive growth, expanding fivefold over the past five years and expected to hit 10 gigawatts in the next half-decade.

    Solar power remains one of India’s strongest sectors. The country is the world’s second-largest photovoltaic manufacturer, and by 2030, it aims to cover 90% of the entire solar value chain.

    Dipal Dutta, CEO of RedoQ, encapsulated the shift: “By expanding deep-tech capabilities across semiconductors, space systems, and next-generation data centers, the nation isn’t just participating in the global supply chain, it is actively rewiring it.”

    From IT Services to Building Technology

    India’s traditional technology story was centered on IT services, software, and outsourcing. Companies built software for global clients and handled tech work for businesses worldwide. The new model is broader and more ambitious. India is now striving to manufacture more of the technology it uses—chip plants underpin a local semiconductor industry, electronics factories move beyond assembly, data centers support cloud and AI services, and space and aerospace firms push deeper into global markets.

    The fundamental change is clear: India is transitioning from being a provider of technology services to becoming a builder of the hardware and systems that power them. If this growth trajectory continues, these six sectors could elevate India’s role in the global technology market significantly.