Tag: Oil Prices

  • Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Oil Prices Slip 1% for Third Day as Saudi Pipeline Repairs Ease Supply Fears

    Brent and WTI Hold Above $100

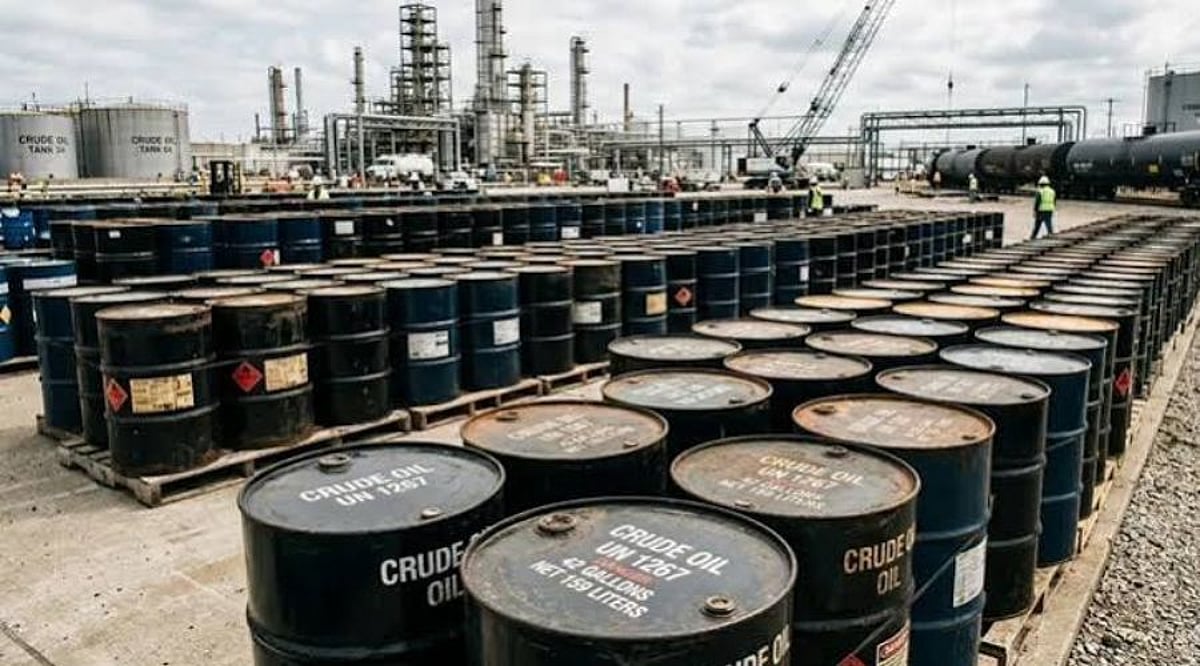
    Global oil prices slipped about 1% on Friday, September 18, marking a third consecutive session of declines. Brent crude futures fell $1.01 to $103.77 a barrel, while West Texas Intermediate dropped $1.03 to $100.88. Both benchmarks stayed above the $100 level after closing roughly 1% lower on Thursday.

    Saudi Pipeline Disruption and Market Response

    Earlier in the week, prices reached four-month highs after crude loadings at Saudi Arabia’s Yanbu Red Sea export hub were suspended. An attack on Saudi Arabia’s East-West pipeline damaged three pumping stations, according to satellite imagery and industry sources, and prompted Riyadh to cancel some deliveries to Europe.

    Traders warned that a prolonged shutdown could remove as much as 4% of global supply. However, Saudi Arabia is now working to restore about half of the pipeline’s capacity within days and is offering additional crude cargoes to Asian refiners through ship-to-ship transfers off Oman’s Sohar port. US Energy Secretary Chris Wright said crude should begin flowing through the pipeline within days, helping to ease immediate supply fears.

    Geopolitical Risks Remain

    The market largely shrugged off fresh cross-border strikes between Saudi Arabia and Yemen’s Iran-backed Houthis on Thursday. At the same time, Iran’s Revolutionary Guards Navy reported that a Togo-flagged oil tanker was struck while attempting an ‘illegal passage’ through the Strait of Hormuz, adding to uncertainty in an already fragile market.

    Analysts Cautious on Outlook

    JPMorgan said it had no clear baseline view for oil markets for the first time since the start of the US-Israeli war on Iran. Peace talks between the US and Iran have not resumed since an interim agreement collapsed in June. The conflict is expected to be discussed at the UN General Assembly next week, with an Iranian delegation scheduled to attend.

    What to Watch

    Market attention now centers on whether Saudi Arabia can restore disrupted pipeline flows and reroute enough crude to limit the impact of the attack. Any delay in repairs or new escalation in the Middle East could quickly reverse the recent downward move in prices.

  • Indian Stock Market Opens Higher as Falling Oil Prices Boost Sentiment: Nifty 50 Rises 64 Points, Sensex Gains 260 Points

    Indian Stock Market Opens Higher as Falling Oil Prices Boost Sentiment: Nifty 50 Rises 64 Points, Sensex Gains 260 Points

    The Indian stock market opened higher on Thursday, buoyed by a decline in global oil prices and mixed cues from international markets. The Nifty 50 index started the session at 23,334.70, gaining 64.1 points or approximately 0.28%, while the Bank Nifty advanced 117.1 points from its previous close. Meanwhile, the Sensex climbed 260.65 points to reach 74,575.24.

    Broader market participation improved, with the Nifty Midcap index rising 0.52% and the Nifty Smallcap index gaining 0.86%. The Indian rupee opened flat at Rs. 95.87 against the US dollar.

    Foreign Institutional Investors (FIIs) remained net sellers in the cash market on September 17, offloading shares worth Rs. 3,208.76 crore. In contrast, Domestic Institutional Investors (DIIs) were net buyers, purchasing Rs. 3,617.75 crore worth of equities.

    Sensex Outlook

    According to Sachin Gupta, VP of Technical Research at Choice Equity Broking Private Limited, the Sensex is expected to maintain its negative bias unless it breaks above the resistance zone of 74,700–75,000. On the downside, the 73,500–74,200 range serves as a critical support area. If the index falls below this level, selling pressure may intensify.

    Nifty 50 Outlook

    The Nifty 50 ended Thursday’s session 53 points higher, forming a small green candle with an upper shadow on the daily chart. The recent recovery has emerged from the key support zone around 23,100–23,000. However, the index lacks strength to reverse the prevailing trend of lower highs and lower lows.

    On the upside, the 23,400–23,500 zone poses strong resistance. A sustained move below 23,000 could trigger a deeper correction.

    Bank Nifty Outlook

    The Bank Nifty formed a long upper-shadow bearish candle, indicating strong supply at higher levels. The sharp rejection from the day’s high suggests sellers remain active. Immediate support is seen at 55,500–55,700, while resistance lies at 56,300–56,500.

    Gupta noted that the broader range for the Bank Nifty is likely to be 55,500–56,500, with a near-term sideways bias. An upside breakout above 56,500 would improve the technical structure, whereas a fall below 55,500 could add further downside pressure.

    Disclaimer: This article is for informational purposes only and does not constitute investment advice. Readers should conduct their own research before making any financial decisions.

  • US Stock Futures Rise as Oil Retreats and Fed Decision Looms

    US Stock Futures Rise as Oil Retreats and Fed Decision Looms

    US stock futures edged higher on Wednesday as investors focused on the Federal Reserve’s upcoming interest rate decision. Oil prices pulled back from recent highs, while Treasury yields remained near the 5% mark. The market also tracked fresh moves in technology stocks after two consecutive sessions of losses on Wall Street.

    At 7:00 a.m. ET, Dow E-minis were up 115 points, or 0.22%. S&P 500 E-minis gained 0.25%, and NASDAQ 100 E-minis rose 0.50%. Traders are pricing a 92.5% chance of a quarter-point rate increase, according to CME FedWatch data, up from 61.2% a week earlier. The Fed will announce its decision at 2 p.m. ET, with markets widely expecting a 25-basis-point hike that would lift the federal funds target range from 3.50%–3.75% to 3.75%–4.00%.

    Oil prices eased on Wednesday after a sharp rally the previous session. Brent crude fell below $108 a barrel, while West Texas Intermediate traded near $104. The drop followed U.S. industry data showing crude inventories rose by 7.1 million barrels in the week ended September 11. Despite the pullback, oil remained above $100 a barrel as supply concerns persist.

    The 10-year U.S. Treasury yield held around 5% after moving above that level on Tuesday, briefly reaching its highest since 2007. Higher bond yields have increased borrowing costs and added pressure on stocks, particularly companies reliant on heavy capital spending.

    In the technology sector, Intel led premarket gains with a more than 5% rise after reports that SK Hynix is in talks with the U.S. chipmaker about producing memory chips domestically. NVIDIA rose less than 1%, while Meta remained nearly flat. Microsoft and Apple edged slightly lower. The broader tech sector remains under scrutiny as AI executives call for a slower pace of advanced model development, raising questions about future spending on chips, data centers, and cloud infrastructure.

    Global markets also moved higher. Europe’s STOXX 600 gained around 0.3%, and a broad Asia-Pacific share index outside Japan rose 0.6%. Investors across major markets now await the Fed’s decision and remarks from Fed Chair Kevin Warsh, which will provide clues on the future path of interest rates. Oil prices, Treasury yields, and the Fed’s rate outlook remain the primary drivers of U.S. stock futures ahead of Wednesday’s opening bell.

  • MCX Gold Prices Rise 0.57% to Rs 1,51,670 as Oil Slips and Fed Decision Nears

    MCX Gold Prices Rise 0.57% to Rs 1,51,670 as Oil Slips and Fed Decision Nears

    Gold prices traded higher on the Multi Commodity Exchange (MCX) on Wednesday, September 16, as a modest pullback in crude oil prices and market anticipation of the US Federal Reserve’s monetary policy decision kept bullion in focus.

    October gold futures climbed 0.57% to Rs 1,51,670 per 10 grams, while September silver futures advanced 1.33% to Rs 2,35,195. The rise came even as the US dollar and bond yields firmed ahead of the Fed’s expected rate move.

    In the energy markets, Brent crude futures slipped 0.74% to USD 107.9 per barrel, while US West Texas Intermediate (WTI) eased 1.09% to USD 104.7 per barrel. According to the CME FedWatch Tool, markets are pricing in a 92.3% probability of a 25-basis-point rate hike by the Federal Reserve later today.

    Domestic Gold Prices

    In the Indian spot market, 24K gold rose by Rs 27 to Rs 1,53,440 per 10 grams, while 22K gold gained Rs 25 to Rs 1,40,650. City-wise, Mumbai and Kolkata quoted 24K gold at Rs 1,53,440, Delhi was at Rs 1,53,590, and Chennai at Rs 1,53,440.

    US Gold and Silver Prices

    Internationally, spot gold rose 0.8% to USD 4,328.39 per ounce. December-delivery US gold futures slipped 0.9% to USD 4,369.50. Meanwhile, spot silver added 1.5% to USD 64.60 per ounce, platinum edged 0.7% higher to USD 1,788.25, and palladium gained 1.6% to USD 1,309.80.

    Market Outlook and Key Levels

    Frank Walbaum, market analyst at trading platform Naga.com, noted that a hawkish Fed could pull gold lower, while softer messaging might ease rate-hike expectations and help the metal recover. He added that traders are also monitoring oil prices and developments in the Middle East.

    Key levels to watch internationally: gold has support at USD 4,310-USD 4,264 per troy ounce and resistance at USD 4,355-USD 4,400. Silver support is seen at USD 63-USD 62.20, with resistance at USD 64.40-USD 65.50 per troy ounce. On MCX, gold has support at Rs 1,50,150-Rs 1,49,400 and resistance at Rs 1,51,500-Rs 1,52,200, while silver has support at Rs 2,30,000-Rs 2,27,700 and resistance at Rs 2,34,400-Rs 2,37,000.

    Traders will now watch the Federal Reserve’s decision and commentary for near-term direction in bullion prices.

  • FTSE 100 Opens 101 Points Lower as Oil Prices and AI Concerns Weigh on UK Stocks

    FTSE 100 Opens 101 Points Lower as Oil Prices and AI Concerns Weigh on UK Stocks

    The FTSE 100 opened 101.11 points lower at 10,596.46 on Tuesday, as rising oil prices—driven by Saudi supply disruptions—and growing unease over the pace of artificial intelligence development dampened market sentiment. Brent crude futures fell 1.96% to USD 107.8 per barrel, while US West Texas Intermediate (WTI) declined 1.98% to USD 103.4 per barrel.

    Sterling was quoted at USD 1.3482 early Tuesday, just below USD 1.3581 at the London equities close on Monday. Versus the euro, the pound rose to EUR 1.1684 from EUR 1.1679.

    Gainers & Losers

    On the upside, Marks & Spencer Group climbed 1.38% to 375.90p. Kingfisher advanced 1.36% to 291.80p, while BAE Systems gained 0.80% to 1,955.50p. Babcock International Group rose 0.60% to 966.80p, Tesco added 0.48% to 483.20p, and GSK increased 0.46% to 1,863p.

    On the downside, London Stock Exchange Group fell 2.38% to 8,272p. Rio Tinto declined 1.85% to 7,074p, while Lion Finance Group dropped 1.64% to 13,190p. Diploma slipped 1.06% to 6,990p, AstraZeneca lost 0.63% to 12,078p, and Games Workshop Group edged 0.57% lower to 17,500p.

    Trustpilot Revenue Jumps

    Trustpilot Group, the online consumer review platform, reported H1 bookings rose 22% to USD 171.2 million and revenue up 23% to USD 151.4 million, as Enterprise and US demand accelerated growth from the prior year. Adjusted EBITDA grew 46% to USD 26.3 million from USD 18 million, with the adjusted EBITDA margin expanding 2.8 percentage points to 17.4%. However, operating profit fell 18% to USD 4.4 million, weighed down by USD 6 million in non-recurring items, including an AGCM fine and a provision for historical US sales taxes.

    Vacancies in the UK Declined

    Vacancies in the UK fell to 702,000 in the three months to August 2026, marking a fall of 8,000, official figures suggest. “Payroll numbers continued to edge down, with falls over the past year particularly evident in the retail and hospitality sectors,” Liz McKeown, director of economic statistics at the ONS, said. “Vacancies remain at their lowest level outside the pandemic period for more than a decade, with smaller businesses continuing to report that increased labor costs are affecting hiring decisions.”

    MJ Gleeson Cuts Dividend

    MJ Gleeson has declined to a pre-tax loss as the housing market remains subdued, prompting the housebuilder to cut its dividend. The builder posted a GBP 2.7 million pre-tax loss in the year to June and cut its dividend from 11p to five pence per share. “Recognizing that this subdued market may not improve anytime soon, we are focused on managing the business as efficiently as possible and taking a prudent stance on cash,” the group told shareholders. However, the number of homes sold was up 9.8% to 1,968, as evidence that it is in a “much stronger position to manage through the challenging market environment” than in recent years.

    Global Market View

    In the US, the S&P 500 lost 0.5%, the Nasdaq Composite fell 0.6%, and the Dow Jones declined 0.3%, while the ten-year Treasury yield briefly touched 5% before settling around 4.98%. In Asia on Tuesday, Tokyo’s Nikkei 225 declined 0.01% to 63,484.1, while China’s Shanghai Composite fell 0.54%. Hong Kong’s Hang Seng declined 0.94%, and South Korea’s Kospi dipped 0.85%. In India, both the Nifty 50 and the Sensex fell by 0.32% and 0.17%, respectively.

  • Oil Prices Surge Above $100, Fueling UK Inflation Concerns Ahead of Bank of England Rate Decision

    Oil Prices Surge Above $100, Fueling UK Inflation Concerns Ahead of Bank of England Rate Decision

    Oil prices climbed above $100 per barrel on Monday as Middle East attacks, Saudi pipeline disruptions, and shipping risks raised supply concerns. The surge has revived speculation that the Bank of England could raise interest rates later this year as higher energy costs add to UK inflation pressures.

    Oil Prices Rise as Saudi Pipeline Remains Shut

    Brent crude futures rose about 2.8% to $107.54 a barrel in early Monday trading, while West Texas Intermediate gained 2.9% to $102.93. Both benchmarks remained above $100 after oil gained about 8% last week. Saudi Arabia temporarily shut its East-West Pipeline after a drone attack. The route carries crude from the Arabian Gulf to the Red Sea port of Yanbu and allows Saudi exports to avoid the Strait of Hormuz. Industry sources said the outage could place up to 4% of global oil supply at risk if the pipeline stays offline.

    Shipping Risks Grow Around Hormuz and Bab el-Mandeb

    Tensions also rose around the Strait of Hormuz after a projectile struck a vessel on Sunday. The UK Maritime Trade Operations said the incident caused a fire and forced the crew to abandon the ship. Iranian authorities later said an unidentified munition hit an Iranian commercial vessel off the country’s coast. Meanwhile, Houthi forces reached Perim Island near the Bab el-Mandeb Strait, another major oil transit route, adding concern over shipping through the Red Sea. Omani Foreign Minister Badr Albusaidi announced the postponement of planned talks between Gulf states and Iran, reducing expectations of an immediate agreement on Hormuz shipping.

    Oil Surge Revives Bank of England Rate Hike Debate

    Higher oil prices have changed expectations for UK interest rates in financial markets. The Bank of England will announce its next policy decision on September 17. The bank rate currently stands at 3.75%, and the central bank has kept it unchanged since the conflict in the Middle East began earlier this year. The bank’s July meeting ended with a 6-3 vote to keep rates unchanged, while three members supported a quarter-point increase to 4%. Since then, energy prices have risen further. Markets now see a greater chance of a rate increase later this year, although a September move is still not the main expectation.

    Bailey Says Future Rate Moves Are Not Certain

    Bank of England Governor Andrew Bailey has cautioned against treating a rate increase as guaranteed. He told lawmakers that he wanted to dispel the idea that policymakers had a ‘secret plan’ for rates. He said future decisions would depend on economic data and events in the Middle East. Bailey also said market pricing included a risk premium linked to concerns about further energy price increases. At the same time, MPC member Megan Greene has raised concern that a longer oil shock could keep inflation expectations elevated. Traders will now watch UK inflation, labour market data, and oil prices before the September 17 decision.

    The outlook for crude prices remains closely tied to the East-West Pipeline, shipping security, and regional diplomacy. ING strategists said it was ‘unclear how severe any potential damage was’ to the Saudi pipeline. A faster restart or renewed Gulf-Iran talks could reduce supply concerns, while further disruptions could keep oil prices elevated.

  • Indian Markets Pause for Ganesh Chaturthi: Key Global Events to Watch This Week

    Indian Markets Pause for Ganesh Chaturthi: Key Global Events to Watch This Week

    The Indian stock market is closed today, September 14, in observance of Ganesh Chaturthi. Both the BSE and NSE are shut for trading in equity, derivatives, and securities lending and borrowing. The holiday follows the weekend, granting investors a three-day break.

    Trading will resume on Tuesday, September 15. The pre-open session begins at 9:00 AM, followed by normal trading from 9:15 AM to 3:30 PM. The market closing session runs between 3:40 PM and 4:00 PM on trading days.

    Upcoming market holidays include Mahatma Gandhi Jayanti (October 2), Dussehra (October 20), Diwali-Balipratipada (November 10), Prakash Gurpurb (November 24), and Christmas (December 25).

    The extended break arrives amid heightened global market activity. Oil prices have surged over USD 3 following fresh strikes involving Saudi Arabia and the Strait of Hormuz. Gold remains volatile as investors monitor crude prices, the US dollar, US-Iran tensions, and the US Federal Reserve’s upcoming rate decision. The Fed meeting is scheduled for September 15 and 16.

    A Pivotal Week for Investors

    Gold is traditionally viewed as a safe haven during uncertainty. However, rising oil prices are altering this dynamic. The global conflict has pushed crude higher, leading investors to expect the Fed to maintain elevated interest rates for longer.

    Higher rates can reduce gold’s appeal since the metal does not pay interest. This creates downward pressure on gold, even as broader market instability drives investors toward safe-haven assets.

    The market holiday offers a short pause, but the upcoming trading session is likely to be active. Oil price movements, the Fed’s decision, and gold trends will be critical signals for investors before making fresh decisions.

  • Geopolitical Turmoil and Its Ripple Effects on Global Stock Markets

    Geopolitical Turmoil and Its Ripple Effects on Global Stock Markets

    Key Takeaways

    • Oil is the transmission channel: A prolonged energy disruption can raise costs, inflation, and pressure corporate profits.
    • Import-heavy economies face greater risks: Higher oil prices can weaken currencies, increase import bills, and hurt domestic demand.
    • The biggest danger is stagflation: Sustained geopolitical shocks can combine higher inflation with slower growth, complicating central-bank decisions.

    A fresh oil shock has put global stocks under pressure. Brent crude crossed USD 100 per barrel on September 9 after new U.S.-Iran military strikes and Houthi attacks on Saudi cities. Brent reached USD 100.95, its highest level since July 24.

    The Dow Jones fell 0.75%, the S&P 500 fell 0.30%, and the Nasdaq fell 0.35%. European stocks also lost ground, while gold rose 1.5% to USD 4,418 an ounce. These moves show how a geopolitical shock can reach stocks through oil, inflation, rates, trade and company profits.

    Oil Turns a Military Shock into a Market Shock

    Oil often gives the first signal after a major conflict. A threat to oil fields, ports or the Strait of Hormuz can cut supply or raise fear of a supply cut. Higher crude prices raise costs for airlines, transport firms, chemical makers and factories. Consumers can also face higher fuel and food costs.

    The current shock has a wider effect. The 10-year U.S. Treasury yield stood at 4.794% on September 9, close to a recent three-year high. Higher energy costs can lift inflation, while higher inflation can push central banks toward higher rates. Higher bond yields then put pressure on stock values, with growth stocks under more pressure than firms with strong cash flow.

    The Federal Reserve now faces a harder choice. About 70% of economists expect the U.S. central bank to hold rates at its next policy session meeting, yet confidence in that view has weakened since August. U.S. inflation data can shift that view fast. Markets also expect the Bank of Japan to raise rates on September 17–18.

    Import-Heavy Markets Face a Sharper Hit

    India offers a clear example. On September 9, the rupee fell past the 95-per-dollar mark as Brent moved above USD 100. Mumbai’s stock index fell about 0.9%. The Reserve Bank of India likely used foreign exchange action and swaps to support the rupee and manage local liquidity. The rupee closed at 95.1050 per dollar, while the one-year implied dollar-rupee yield reached 3.16%, a three-month high.

    A weaker currency can lift import costs, while higher rates can reduce demand for homes, cars and business credit. Foreign funds can also leave local markets when global risk appetite falls. The IMF has warned that commodity importers face a larger financial shock than stronger economies.

    The Bigger Risk Sits Between Inflation and Growth

    Geopolitical tensions do not always cause a long stock market decline. Markets can absorb a short conflict if oil prices fall back and trade routes stay open. The danger grows when a military crisis turns into a long energy shock.

    The IMF expects global growth at 3.1% in 2026 and 3.2% in 2027 under the assumption of a limited Middle East conflict. It also expects global inflation to rise modestly in 2026 before a decline in 2027. A longer conflict, deeper geopolitical division or fresh trade tensions could weaken growth and unsettle markets.

    The IMF’s April 2026 financial stability report points to higher energy costs, lower equity prices, higher bond yields, capital outflows, currency pressure and leverage at non-bank financial firms. It also flags high valuations in artificial intelligence stocks as a source of wider market stress.

    If oil returns below USD 100, inflation pressure may ease and stocks may regain ground. If oil stays above that level for a long period, central banks may keep rates high for longer, which can weaken stock values and business demand.

    What Matters Most for Global Stocks Now

    The Strait of Hormuz remains a key market risk. A long disruption could raise energy costs across Asia, Europe and other import-heavy regions. Freight and supply costs could also rise, which would add pressure to company margins and consumer prices. The IMF has warned that a prolonged conflict could weaken growth and raise inflation much more sharply.

    Gold has shown its role as a defensive asset, while the Japanese yen reached a seven-month high. The U.S. dollar index slipped to 98.65. These moves show that investors still seek protection, yet higher oil prices also create pressure on major economies.

    J.P. Morgan’s mid-year outlook remained constructive on equities if the energy shock stays manageable. The key risk sits where war meets inflation. A short conflict may create a sharp but limited market shock. A longer crisis could raise oil prices, lift inflation, force tougher central bank policy and slow economic growth at the same time. That chain can turn a geopolitical event into a broad financial problem.

    FAQs

    1. How do geopolitical tensions affect stock markets?

    They can increase oil prices, disrupt trade, weaken currencies, raise inflation and increase uncertainty, leading investors to reduce exposure to riskier assets.

    2. Why is a rise in oil prices bad for stocks?

    Higher oil prices increase operating and transportation costs for many companies and can reduce consumer spending, corporate margins and economic growth.

    3. Which economies are most vulnerable to an oil shock?

    Oil-importing economies are generally more exposed because higher crude prices increase import bills, inflationary pressure and currency risks.

    4. Why do higher oil prices affect interest rates?

    Expensive energy can push inflation higher. Central banks may therefore delay rate cuts or maintain tighter monetary policy, which can weigh on equity valuations.

    5. Can geopolitical tensions create a long-term stock market decline?

    Not necessarily. Markets can recover if the conflict remains contained and oil prices normalize. A prolonged energy or trade disruption poses a much greater risk to global growth and equities.

  • US Stock Futures Climb Ahead of August CPI Report; Oracle Surges, Adobe Slides

    US Stock Futures Climb Ahead of August CPI Report; Oracle Surges, Adobe Slides

    US stock futures moved higher on Friday as investors prepared for the August consumer price index report. Oil prices eased from recent highs, while Treasury yields stayed close to multiyear peaks. Markets remained cautious after Wall Street recorded four straight sessions of losses.

    At 5:31 a.m. ET, Dow E-minis rose 276 points, or 0.53%. S&P 500 E-minis gained 0.54%, while NASDAQ 100 E-minis increased 0.57%. The gains followed another weak session on Thursday, when the Dow fell more than 300 points, the S&P 500 dropped 0.6%, and the NASDAQ Composite declined 0.7%.

    Investors now await the August CPI report. Economists expect consumer prices to rise 0.4% from July and 3.4% from a year earlier. Core CPI is expected to rise 0.2% monthly and 2.4% annually. The data arrives after a hotter producer price index, which increased 0.4% in August and rose 5.4% from a year earlier.

    The inflation readings come ahead of the Federal Reserve’s Sept. 15-16 meeting. Futures markets assign roughly a two-thirds to 70% chance of a 25-basis-point rate increase. Christopher Hodge, chief US economist at Natixis CIB Americas, said an inflation reading near expectations could reduce pressure on the Fed to raise rates.

    Oil prices moved lower on Friday but remained above $104 a barrel for Brent and near $100 for West Texas Intermediate. Shipping activity through the Strait of Hormuz has fallen sharply, and markets continue to monitor Middle East tensions. Bill Adams, chief US economist at Fifth Third Commercial Bank, noted that the surge in energy prices creates new upside risk for inflation.

    Treasury yields stayed elevated, with the 10-year near 4.94% after approaching 5% on Thursday. The 30-year yield reached about 5.3%. Higher bond yields can reduce demand for stocks as investors shift to lower-risk fixed-income assets.

    Oracle shares jumped about 7% in premarket trading after the company reported stronger quarterly revenue and profit. Its cloud infrastructure sales more than doubled, and it added more than $30 billion in AI cloud contracts during the quarter. Remaining performance obligations reached $664 billion. Adobe shares fell more than 2% after issuing a fourth-quarter revenue forecast below Wall Street expectations, though its adjusted earnings of $6.13 per share beat estimates.

    Nvidia gained in premarket trading, while ACV Auctions surged after Copart agreed to acquire it for nearly $1.9 billion. Friday’s market direction will depend heavily on the CPI reading as investors assess inflation, Treasury yields, oil prices, and expectations for the Federal Reserve’s next move.

  • Bitcoin Drops Below $77K as Hot PPI, Oil Surge, and Liquidations Pressure Crypto Market

    Bitcoin Drops Below $77K as Hot PPI, Oil Surge, and Liquidations Pressure Crypto Market

    The cryptocurrency market extended its decline after hotter US producer inflation, rising oil prices, and leveraged liquidations increased pressure across risk assets. Bitcoin fell below USD 77,000 after trading near USD 78,500 during the past 24 hours. Total market capitalization dropped to about USD 2.62 trillion as major altcoins also weakened.

    Trading activity increased as prices fell. The 24-hour market volume reached roughly USD 84.3 billion, up about 3.1%. Bitcoin dominance stood near 59%, while Ethereum remained below USD 2,500.

    Hotter PPI Revives Fed Rate Fears

    August US producer prices rose 0.4%, renewing concerns that inflation remains persistent. The reading increased expectations for tighter Federal Reserve policy at the September 15-16 meeting.

    Futures markets priced the chance of a rate increase near 70%, while economists had expected no change. The Fed kept its target range at 3.50% to 3.75% in July. Three policymakers favored a quarter-point increase at that July meeting. Higher interest rates can support the dollar and reduce demand for speculative assets, including Bitcoin, altcoins, and crypto-related stocks.

    Oil Spike and Liquidations Deepen Selling Pressure

    Brent crude reached USD 104 after gaining 5% on Thursday. Oil also climbed more than 10% during the week and reached its highest level in 112 days. Higher fuel costs can lift transportation, manufacturing, and consumer prices. This pressure can keep inflation elevated and give the Federal Reserve less room to support risk markets.

    Leveraged trading added another source of pressure. More than USD 190 million in long positions disappeared within one hour, including over USD 112 million linked to Bitcoin. Crypto ETF outflows also weighed on prices.

    Bitcoin Leads Broad Altcoin Market Weakness

    Bitcoin traded near USD 77,225 after losing momentum from recent highs. Ethereum held above USD 2,450 but remained below USD 2,500, while XRP fell more than 3% toward USD 1.34. BNB traded near USD 714, while Solana and Hyperliquid moved below USD 100 and USD 80, respectively. The declines showed that selling extended beyond Bitcoin into several major altcoins.

    Some tokens still gained despite the weaker market. Raydium rose more than 27.23%, while Ether.fi gained 9.60%, Aptos advanced 3.64%, and Polkadot added 2.10%. Zcash fell 13.23% but remained above USD 1,000. Meanwhile, the US Treasury completed a USD 5.1 billion debt buyback, bringing the weekly total to a record USD 17.7 billion.

    Attention now centers on the September 15-16 Federal Reserve meeting and whether tighter policy expectations continue pressuring risk assets.