
Tag: Oil Prices

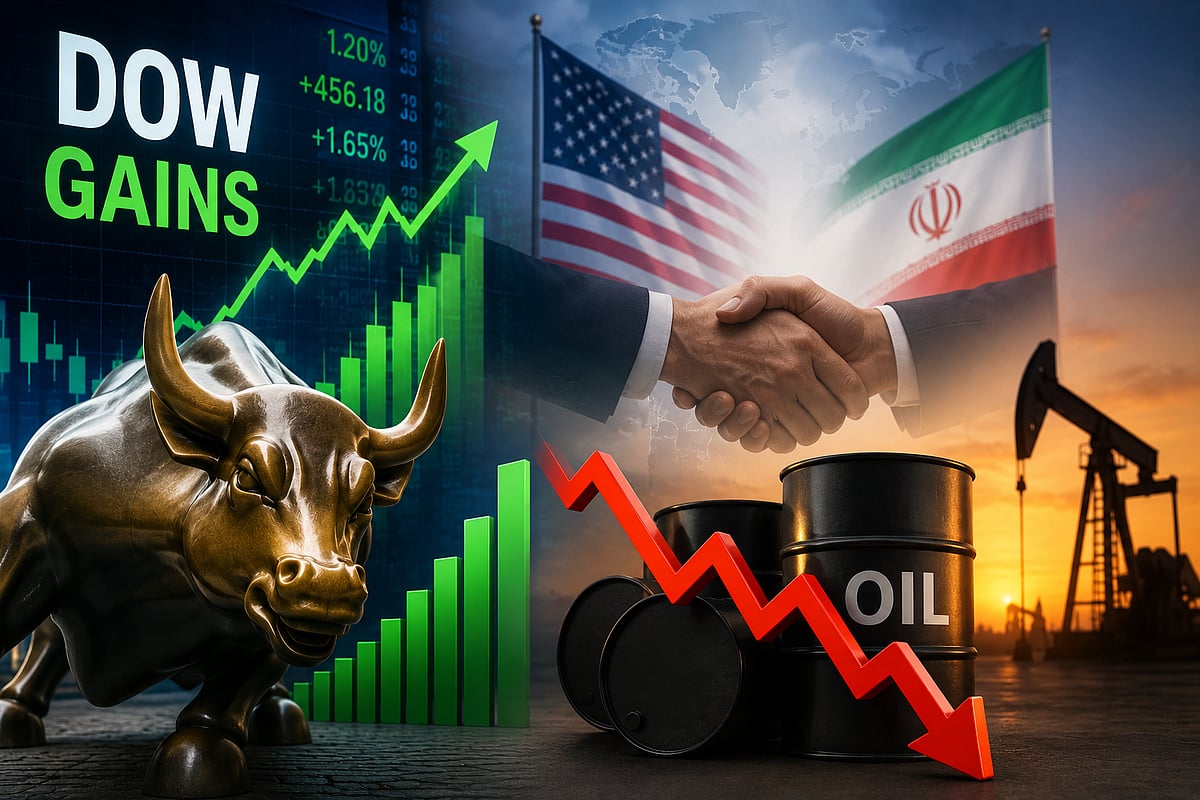
  • Dow Rises Over 300 Points as Oil Retreats on Renewed Iran-US Peace Diplomacy Hopes

    Dow Rises Over 300 Points as Oil Retreats on Renewed Iran-US Peace Diplomacy Hopes

    The Dow Jones Industrial Average surged more than 300 points on Friday as oil prices tumbled following reports that Pakistan may mediate renewed talks between the United States and Iran. The S&P 500 also advanced, while the NASDAQ remained under pressure due to declines in semiconductor stocks.

    Oil Retreat Fuels Market Optimism

    The Dow gained approximately 0.7%, buoyed by a roughly 3% rise in Apple shares. The S&P 500 added around 0.6%, while the NASDAQ struggled to hold gains as chip stocks slid. Brent crude fell more than 4% to trade near $95 per barrel after surpassing $100 earlier in the week. West Texas Intermediate also dropped about 4% to above $88. Lower oil prices alleviated concerns over inflation, transportation costs, and corporate expenses.

    Pakistan Explores Peace Talks Mediation

    According to Reuters, Pakistan is exploring a path to restart stalled negotiations between the U.S. and Iran. Three Pakistani sources indicated that China initiated the diplomatic effort. Pakistani officials discussed the plan with Iranian representatives during recent meetings. However, the sources noted that “obstacles to any talks with the US remain high.” China has significant trade and energy interests in the Gulf, and Pakistan maintains close ties with Beijing, Saudi Arabia, and Iran, complicating its potential mediator role.

    Geopolitical Risks Drive Oil Volatility

    Oil had climbed above $100 earlier amid ongoing conflict in the region, raising fears of supply disruptions across the Gulf and Red Sea. U.S. strikes on Iranian targets and attacks linked to Iran-backed groups kept energy traders focused on shipping routes and production risks. The Strait of Hormuz remains a major concern for China and other large oil buyers, as any disruption could restrict crude shipments and drive up global energy costs. Friday’s diplomatic report eased some of those fears, prompting traders to sell oil futures.

    Chip Sector Caps Broader Gains

    Semiconductor stocks declined even as the Dow and S&P 500 rose. Intel dropped about 3% after initially gaining on better-than-expected results. Broadcom and Advanced Micro Devices each lost roughly 2%, while Micron Technology fell about 5%. The Philadelphia Semiconductor Index declined more than 3% in early trading. Investors continue to question the pace of artificial intelligence spending after Alphabet and Tesla reported higher capital costs and cash usage. The cautious tone set the stage ahead of earnings from Microsoft, Amazon, and Meta.

    Corporate Moves and Sector Rotation

    Verizon advanced after raising its annual forecasts for adjusted profit and free cash flow. Real estate and communication services led gains in the S&P 500 as investors rotated into sectors less exposed to chip weakness. Citi raised price targets for Dell and Hewlett Packard Enterprise, with analyst Asiya Merchant maintaining buy ratings on both, citing demand for servers, networking equipment, and AI infrastructure. Citi lifted its HPE target to $74 from $70, implying about 55% upside from Thursday’s close.

    Fed Policy and Tariffs Add to Uncertainty

    Investors also assessed new U.S. tariffs of 10% and 12.5% on goods from 60 trading partners, linked to weak enforcement of forced-labor restrictions. The new duties followed the expiration of a temporary 10% global tariff. The Federal Reserve meets next week, with markets weighing inflation risks from energy costs. Futures pricing indicates about a one-in-three chance of an interest rate hike, up from 12% a week earlier. Fed Chairman Kevin Warsh has maintained the central bank’s focus on price stability and employment.

    Despite Friday’s gains, the Dow and S&P 500 are on track for small weekly losses. The NASDAQ is headed for a decline of more than 1%, as technology weakness offsets the relief from lower oil prices.
  • Ethereum Fees Plunge 51% as Transactions and Staking Reach All-Time Highs

    Ethereum Fees Plunge 51% as Transactions and Staking Reach All-Time Highs

    Ethereum’s quarterly fee revenue dropped 51% year-over-year to approximately $64 million in Q2 2026, even as transaction volumes and staking activity hit new records, according to a report from Bitwise. The decline stems from cheaper and more abundant blockspace rather than weakening demand.

    Revenue measured in ETH actually rose for the first time in over a year. Ethereum generated roughly $131 million in fee revenue during Q2 2025, but that figure fell to nearly $64 million one year later.

    Cheaper Blockspace Drives Higher Ethereum Usage

    Ethereum processed 203.9 million transactions during the quarter, up sharply from 121.1 million a year earlier. Network throughput also improved to 26 transactions per second from 15. The network increased its block gas limit to 60 million, creating more room for transactions and reducing user costs even as activity expanded.

    Bitwise described rising usage and falling fees as the quarter’s dominant trend. Researchers attributed the gap to protocol changes that expanded blockspace across blockchain networks. In ETH terms, quarterly revenue increased from 27,670 ETH in Q1 to 31,166 ETH in Q2, though the weaker token price reduced the dollar total.

    Active staking reached a record 40.2 million ETH, representing about 33% of the total supply. Institutional inflows continued as more tokens entered staking contracts. The question remains whether rising usage and record staking can offset weaker dollar revenue as Ethereum faces broader market pressure.

    The same pattern appeared on other networks. Solana processed 9.8 billion non-voting transactions near its record, while its dollar revenue declined. Avalanche handled 236 million C-Chain transactions, compared with 58 million a year earlier. Lower congestion reduced fees even as network use expanded.

    ETH Price Faces Oil, Rates, and Technology Pressure

    Ethereum traded near $1,927 on July 23 after reaching an intraday high of $1,941, according to crypto.news data. The token recovered more than 27% from its June low near $1,514. However, repeated failures near $1,955 kept ETH below the psychological $2,000 level.

    Oil prices added pressure as Middle East tensions pushed crude higher for a fifth session. West Texas Intermediate moved above $90 per barrel. Attacks by Iran-aligned Houthis on Saudi oil tankers raised supply concerns. Higher energy costs could lift inflation and narrow the Federal Reserve’s policy options.

    CME FedWatch data showed the probability of a September rate hike rising to 79% from 68%. Traders still expected no change at the July meeting. Technology shares also weakened after Alphabet lifted its 2026 capital-spending forecast to between $195 billion and $205 billion.

    Alphabet reported negative free cash flow of $5.9 billion as quarterly spending doubled to $44.9 billion. Its shares fell during premarket trading. Meanwhile, US spot Ethereum ETFs recorded $72.64 million in net inflows on July 22, according to SoSoValue.

    BlackRock’s iShares Ethereum Trust led with $53.47 million. The regulated products continued attracting capital while ETH remained below $2,000. BitMEX also announced plans to stop operations on September 23 following a strategic review by parent company HDR Global Trading.

    The exchange told customers to close positions and withdraw funds before the deadline. BitMEX has served more than two million professional and institutional traders since 2014. Position transfers could shift leverage to rival platforms. Binance, Bybit, OKX, and other exchanges still operate larger Ethereum derivatives markets.

    Ethereum fee revenue fell 51% even as transactions, throughput, and staking reached record levels. Cheaper blockspace reduced user costs, while ETF inflows supported demand. Still, oil prices, rate expectations, and weaker technology shares could continue influencing ETH’s attempt to reclaim $2,000.

  • Bitcoin Under Pressure: Rising Oil Prices, High Interest Rates, and Regulatory Uncertainty Weigh on Market

    Bitcoin Under Pressure: Rising Oil Prices, High Interest Rates, and Regulatory Uncertainty Weigh on Market

    Bitcoin is facing a challenging period as rising oil prices fuel inflation concerns, elevated interest rates reduce risk appetite, and ongoing regulatory uncertainty keeps investors cautious. Despite these headwinds, institutional support through spot Bitcoin ETFs continues to provide a long-term foundation for the cryptocurrency.

    Key Takeaways

    • Rising oil prices have renewed inflation fears, increasing pressure on Bitcoin.
    • High interest rates are shifting investor capital toward safer assets.
    • Institutional demand via spot Bitcoin ETFs remains a positive factor for long-term confidence.

    Higher Oil Prices Stoke Inflation Worries

    Bitcoin’s recent weakness is largely tied to the surge in oil prices. Brent crude has climbed back to $100 per barrel amid escalating tensions in the Middle East. Higher oil costs ripple through the economy, raising transportation, manufacturing, and service expenses — costs that are ultimately passed on to consumers. This inflationary environment makes central banks hesitant to cut interest rates, which in turn dampens appetite for riskier assets like Bitcoin.

    Interest Rates Dampen Demand for Cryptocurrencies

    Central banks worldwide have kept borrowing costs high to combat inflation, making government bonds and money market funds more attractive due to their reliable, low-risk returns. Consequently, capital that might have flowed into cryptocurrencies has moved into traditional financial products. Investors are closely monitoring central bank meetings, with many expecting rates to remain elevated if inflation stays above target — especially with oil prices continuing to rise.

    Regulatory Uncertainty Lingers

    Governments around the globe are still crafting new rules for cryptocurrencies, covering taxation, stablecoins, exchange operations, anti-money laundering, and investor protection. While many investors welcome clear regulations — which could boost confidence and attract institutional money — the current uncertainty creates caution. Any major policy announcement can quickly move Bitcoin prices as traders react to the latest developments.

    Market Sentiment Remains Cautious

    Bitcoin has held relatively steady near $66,000, but volatility persists. Trading volumes are lower than in previous bull markets, indicating a wait-and-see stance among many investors. They are unlikely to re-enter the market until inflation slows, interest rates fall, or economic conditions improve. Analysts note that Bitcoin is now more sensitive to macroeconomic data — such as inflation, unemployment, and central bank decisions — than in earlier years.

    Institutional Investors Provide a Buffer

    Despite short-term pressures, institutional demand remains a strong pillar. U.S. spot Bitcoin ETFs have recently reported fresh inflows after periods of withdrawals. These regulated products make it easier for pension funds, wealth managers, and large financial institutions to gain exposure to Bitcoin without directly holding the asset. This steady institutional participation helps support Bitcoin even during uncertain times.

    What’s Next for Bitcoin?

    The coming months will be crucial. Investors will watch central bank decisions, inflation reports, oil market developments, and regulatory updates closely. Continued inflows into spot Bitcoin ETFs could provide additional support. The balance between these positive and negative factors will likely determine Bitcoin’s next major price move.

    Why This Matters

    Bitcoin has become a significant part of the global financial system, so changes in oil prices, interest rates, and government policies now affect millions of investors. Understanding these risks helps investors interpret Bitcoin’s performance and prepare for future market shifts.

    Outlook

    Several factors are currently working against Bitcoin: oil prices above $100, high interest rates limiting risk appetite, and regulatory hurdles. However, institutional adoption via spot Bitcoin ETFs has helped cushion losses from previous shocks. The near-term direction depends on inflation trends, interest rate decisions, oil prices, and regulatory signals.

    Frequently Asked Questions

    1. Why do higher oil prices affect Bitcoin? Higher oil prices can increase inflation, making investors less willing to buy riskier assets like Bitcoin.
    2. How do interest rates impact Bitcoin prices? Higher interest rates make safer investments more attractive, reducing demand for cryptocurrencies.
    3. Is Bitcoin still attracting institutional investors? Yes. Spot Bitcoin ETFs continue to draw institutional investment despite short-term volatility.
    4. Why does regulation matter for Bitcoin? New regulations can affect how cryptocurrencies are traded, taxed, and adopted by financial institutions.
    5. What could help Bitcoin recover? Lower inflation, interest rate cuts, stable oil prices, and greater regulatory clarity could improve market confidence and support Bitcoin prices.
  • FTSE 100 Hits 10,670 as Retail Sales Surge and HSBC Sells Insurance Unit for $2.1B

    FTSE 100 Hits 10,670 as Retail Sales Surge and HSBC Sells Insurance Unit for $2.1B

    The FTSE 100 opened 31 points higher at 10,670 on Friday, buoyed by a strong retail sales report and a major corporate deal, even as Middle East tensions, rising oil prices, and new US tariff risks weighed on broader market sentiment.

    Oil prices continued to climb, with Brent crude futures falling 2.22% to $98.45 per barrel and US West Texas Intermediate (WTI) declining 2.21% to $90.15 per barrel. Sterling strengthened to $1.3315 early Friday from $1.3303 at Thursday’s London close, while against the euro, the pound edged down to €1.1693.

    Gainers & Losers

    On the upside, 3i Group rose 3.33% to 2,763p, RELX advanced 3.31% to 2,532p, and JD Sports Fashion gained 3.12% to 88.46p. Weir Group climbed 2.67% to 2,612p, Pershing Square Holdings added 2.58% to 3,736p, and Sage Group increased 2.56% to 842p.

    On the downside, Airtel Africa declined 5.32% to 327.20p. Shell fell 0.76% to 3,318.50p, while AstraZeneca slipped 0.69% to 12,600p. GSK dropped 0.50% to 1,896p, Endeavour Mining eased 0.45% to 3,548p, and Rio Tinto edged 0.37% lower to 6,831p.

    US Tariffs

    The US announced new tariffs on 60 trading partners over forced labor concerns, replacing an expiring global duty introduced earlier this year. The levies, effective Friday, range from 10% to 12.5%. Canada, the EU, and the UK are expected to face the lower 10% rate, while China and Japan are among those facing the higher 12.5% rate.

    Retail Sales Jump

    Retail sales jumped in June as heavy discounting drove online shopping. The volume of retail sales rose by 1% in June, following 1.2% growth in May, according to the Office for National Statistics (ONS). Online shopping grew to its largest proportion of total retail sales since spring 2021, when the COVID-19 pandemic kept consumers away from high streets.

    Hannah Finselbach, senior statistician at the ONS, said: “Internet retailers did especially well, with businesses telling us that this was because of promotions and the warm weather.”

    HSBC Sells Insurance Business

    HSBC has agreed to sell its life and health insurance business in Singapore to Allianz for $2.1 billion (£1.6 billion). Completion is anticipated in the first half of 2027. The deal is expected to generate HSBC a pre-tax gain of $1.8 billion. The transaction follows an internal review, with HSBC determining that a sale would be the “best outcome for both parties” as the bank focuses on areas where it has a “clear competitive advantage”.

    Global Market View

    In the US, stocks fell overnight: the Nasdaq declined 2.2%, the S&P 500 dropped 1.2% (its worst session of the month), and the Dow shed 1%. In Asia on Friday, Tokyo’s Nikkei 225 fell 2.73% to 64,611.15, while China’s Shanghai Composite dipped 1.61%. Hong Kong’s Hang Seng declined 1.04%, and South Korea’s Kospi fell 5.72%. In India, both the Nifty 50 and the Sensex fell by 0.31% and 0.44%, respectively.

    Disclaimer: Analytics Insight does not provide financial advice or guidance on cryptocurrencies and stocks. This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before making any investments.

  • Wall Street Tumbles: Dow Loses 500 Points as Oil Surge and Tech Losses Bite

    Wall Street Tumbles: Dow Loses 500 Points as Oil Surge and Tech Losses Bite

    US stocks fell sharply on Thursday as a surge in oil prices, rising bond yields, and disappointing earnings from major technology companies weighed on market sentiment. The Dow Jones Industrial Average dropped approximately 500 points during morning trading, with the S&P 500 losing nearly 1% and the Nasdaq Composite falling around 1.7%.

    The sell-off pushed major indexes to multi-week lows, with declining shares outnumbering advancing stocks on both the New York Stock Exchange and Nasdaq. The CBOE Volatility Index rose to 18.79 after three consecutive declines, reflecting heightened investor anxiety.

    Oil Rally Raises Inflation Concerns

    Brent crude futures surged 6.7% to $100.37 per barrel during European trading, while West Texas Intermediate gained 5.5% to $91.91 per barrel. The rally followed reports that Houthi forces attacked two Saudi oil tankers near the Bab el-Mandeb Strait, raising fresh supply concerns and threatening another major shipping route.

    Higher oil prices pushed Treasury yields upward, with the 10-year yield reaching its highest level since January 2025 and the two-year yield hitting a 17-month high. This renewed inflation fears, prompting traders to increase bets on a Federal Reserve rate hike at the July meeting. CME FedWatch data showed markets pricing a 38% chance of a quarter-point increase, up from about 12% just one week earlier.

    Alphabet and Tesla Pressure Nasdaq

    Alphabet shares fell more than 6% after the company raised its 2026 capital spending forecast, with investors focusing on costs tied to artificial intelligence infrastructure. AJ Bell investment director Russ Mould noted a “healthy degree of scepticism” about returns from such spending. The decline pulled communication services stocks lower.

    Tesla shares dropped more than 12% after reporting negative quarterly free cash flow and higher operating expenses relative to revenue growth. CEO Elon Musk called 2026 a “massive capex year,” with spending plans including robots, data centers, manufacturing projects, and its robotaxi business.

    Energy Shares Rise With Crude Prices

    Energy companies moved higher as oil prices extended a five-day rally. Exxon Mobil gained 1.6%, while Chevron rose 1.9%. Diamondback Energy, Devon Energy, ConocoPhillips, and Occidental Petroleum gained between 1.7% and 2.7%. Refiners also advanced, with Valero Energy, Marathon Petroleum, and Phillips 66 rising between 1.1% and 1.3%.

    Analysts also watched shipping activity in the Middle East. UBS analyst Giovanni Staunovo said subdued vessel traffic could slow the region’s production recovery.

    Rate Expectations Shift Before Fed Meeting

    The oil rally renewed concern that higher fuel costs could keep inflation elevated. New labor data also supported expectations that the Fed could keep policy tight, with initial unemployment claims falling to 187,000, below forecasts of 210,000.

    Airline shares faced pressure as higher fuel costs threatened operating expenses, while transport stocks moved lower. Lockheed Martin shares rose after the company lifted its 2026 forecasts, and ServiceNow gained after raising its annual subscription revenue outlook.

    Markets will likely remain focused on oil prices, upcoming inflation data, and the Federal Reserve’s next policy decision for direction.

  • FTSE 100 Opens Lower After Rally as Brent Crude Surges Above $97; Mixed Corporate Earnings in Focus

    FTSE 100 Opens Lower After Rally as Brent Crude Surges Above $97; Mixed Corporate Earnings in Focus

    The FTSE 100 opened 16.72 points lower at 10,700.25 on Wednesday, pulling back after a sharp rally that pushed the index to a 20-week high of 10,716.97. The decline came as oil prices continued to climb, with Brent crude futures jumping 3.36% to $97.23 per barrel and US West Texas Intermediate (WTI) gaining 2.75% to $89.22.

    Gainers & Losers

    On the upside, Segro led the gainers with a 7.06% rise to 958.20p. Anglo American advanced 4.93% to 3,703p, while 3i Group rose 2.98% to 2,628p. RELX gained 2.61% to 2,518.00p, BP climbed 2.32% to 551.80p, and Tritax Big Box REIT added 1.84% to 171.90p.

    On the downside, Whitbread fell 3.14% to 2,379p. Endeavour Mining declined 2.49% to 3,650p, while London Stock Exchange Group slipped 1.34% to 8,566p. AstraZeneca dropped 1.26% to 12,542.00p, Games Workshop Group eased 0.90% to 19,920p, and Lion Finance Group edged 0.69% lower to 11,520p.

    Mixed Numbers from Centrica

    Centrica hiked its interim dividend by 9% despite lower first-half profits, as energy-market volatility slowed progress in parts of the British Gas owner’s business. Underlying earnings (EBITDA) of £737 million were reported for the six months to June, down 18% year-on-year. Statutory profit before tax swung to £672 million from a £43 million loss.

    Burnham to Cut Pub Business Rates

    Andy Burnham announced a 20% cut to business rates for pubs, clubs, and music venues, funded by cracking down on businesses like vape shops and tax-avoidant online sellers. The £100 million commitment follows a campaign by hospitality venues after tax bills soared due to Rachel Reeves’ Autumn Budget last year.

    EasyJet Profits Decline

    EasyJet reported a 70% fall in third-quarter profit, with headline profit before tax of £85 million for the three months to June, down from £286 million a year earlier. The Middle East conflict kept fuel costs elevated and affected bookings. Group revenue advanced 2% to £2.98 billion, but fuel costs jumped 17% to £732 million.

    Jupiter’s Net Inflows Continue

    Jupiter’s net inflows and profit jumped despite the loss of two mandates. Net inflows reached £700 million in the first half of the year, driven by momentum in retail, wholesale, and investments. Assets under management (AUM) rose 36% to £73.7 billion, supported by the acquisition of CCLA. Revenue grew 39% to £213.3 million.

    Global Market View

    In the US, the Nasdaq and S&P 500 fell 0.6% and 0.1%, respectively, while the Dow Jones finished little changed. In Asia, Tokyo’s Nikkei 225 rose 0.46% to 66,422.6, and China’s Shanghai Composite gained 0.25%. Hong Kong’s Hang Seng advanced 1.09%, and South Korea’s Kospi rose 4.4%. In India, the Nifty 50 and the Sensex fell 0.49% and 0.56%, respectively.

  • Dow Rises, Nasdaq Slips as Wall Street Awaits Alphabet and Tesla Earnings Amid Rising Oil Prices

    Dow Rises, Nasdaq Slips as Wall Street Awaits Alphabet and Tesla Earnings Amid Rising Oil Prices

    U.S. stocks ended mixed on Wednesday as investors weighed rising oil prices, a downturn in semiconductor shares, and anticipation of major earnings reports from technology giants. The Dow Jones Industrial Average gained roughly 0.5%, while the S&P 500 hovered near the flatline. The Nasdaq Composite fell about 0.3%, dragged lower by weakness in chip stocks.

    Big Tech Earnings in Focus

    Alphabet, Tesla, IBM, ServiceNow, and Texas Instruments are set to report quarterly results after the closing bell. Their updates are expected to shed light on artificial intelligence spending, cloud demand, and corporate technology budgets. Alphabet and Tesla are the first members of the ‘Magnificent Seven’ to release second-quarter results, with investors closely watching revenue growth, capital expenditure, and forward guidance.

    Alphabet shares traded near $346 ahead of the report. The company faces scrutiny over its AI strategy after delaying a model launch tied to its development plans. Tesla’s results will also be closely watched as the automaker continues heavy spending on new projects. Analysts will focus on cash flow, operating costs, and capital outlays.

    Sam Stovall, chief investment strategist at CFRA Research, noted that investors may adopt a ‘wait-and-see attitude’ before making larger market moves, with spending levels playing a central role in the response to these earnings.

    Oil Prices Surge on Geopolitical Tensions

    Oil prices climbed as the United States conducted its eleventh straight round of strikes against Iran. Brent crude rose about 3% to trade above $93 per barrel, briefly crossing $95. West Texas Intermediate advanced above $86 per barrel. U.S. Secretary of State Marco Rubio stated that Washington would continue protecting shipping through the Strait of Hormuz and described Iran as ‘not serious’ about negotiations.

    Higher energy prices reignited concerns about inflation and interest rates. Federal funds futures indicated a strong likelihood that the Federal Reserve will hold rates steady at its next meeting, though markets still price in a potential rate increase later in 2026.

    Chip Stocks Weigh on Nasdaq

    Technology stocks were the weakest sector during morning trading, with semiconductor shares under pressure after several volatile sessions. The Philadelphia Semiconductor Index traded near unchanged levels, having closed lower in five of the past ten sessions. Texas Instruments edged lower ahead of its earnings release. Investors are scrutinizing chip demand, order growth, and management forecasts during this earnings season. AI infrastructure spending has supported semiconductor valuations, but recent price swings have slowed the Nasdaq’s momentum.

    Materials and utilities sectors moved higher, limiting broader market losses. Strength in industrial and materials shares also supported the Dow. Market breadth remained positive, with advancing stocks outnumbering decliners on both the NYSE and Nasdaq.

    Notable Stock Movers

    Super Micro Computer surged more than 20% after the AI server maker issued a strong business update, securing over $60 billion in new fourth-quarter orders and forecasting gross margins above previous expectations. AT&T gained about 3% after adding more wireless subscribers than analysts anticipated and reporting better-than-expected quarterly earnings.

    GE Vernova shares fell despite reporting $11.1 billion in revenue and raising its 2026 guidance, as earnings missed market estimates. The company posted an 88% rise in total orders to $24.2 billion, with data center orders exceeding $5 billion in the first half of the year—more than double its full-year total in 2025.

    Shares of generic drugmakers declined after President Donald Trump announced plans for future tariffs on imported generic medicines, starting with a 100% tariff in August 2028 and rising to 200% a year later.

    With oil prices rising and Big Tech earnings approaching, markets remain focused on the next major catalyst for direction.

  • FTSE 100 Rises Above 10,598 Despite UK Inflation Data; Brent Crude Jumps to $94.22

    FTSE 100 Rises Above 10,598 Despite UK Inflation Data; Brent Crude Jumps to $94.22

    The FTSE 100 traded 12.33 points higher at 10,598.24 on Wednesday, defying cooler-than-expected UK inflation data that boosted the likelihood of near-term Bank of England rate cuts. Investors weighed rising oil prices and ongoing US-Iran tensions, with Brent crude futures surging 3.53% to $94.22 per barrel and US West Texas Intermediate (WTI) gaining 3.53% to $87.32 per barrel.

    Gainers and Losers

    Top gainers:

    • Endeavour Mining: +2.34% to £36.37
    • Fresnillo: +1.29% to £25.99
    • Shell: +1.15% to £32.92
    • Admiral Group: +1.13% to £35.78
    • Reckitt Benckiser: +0.75% to £49.75
    • AstraZeneca: +0.45% to £125.48

    Top decliners:

    • Games Workshop Group: -2.43% to £196.50
    • London Stock Exchange Group: -1.86% to £84.40
    • Halma: -1.72% to £35.54
    • Experian: -1.52% to £26.59
    • Next: -1.51% to £147.25
    • Pershing Square Holdings: -0.95% to £37.54

    Mulberry Narrows Losses

    Mulberry reported a sharp reduction in annual losses and a return to revenue growth, with trading accelerating into the new financial year. Pre-tax losses narrowed to £8.9 million from £32.2 million, as revenues grew 4% to £125.5 million. Growth accelerated to 11% in the second half. The company swung to positive EBITDA of £0.8 million, compared with a £16.8 million loss a year earlier.

    Bloomsbury Expects Cash from Anthropic Settlement

    Bloomsbury, the publisher of Harry Potter, expects a significant payout from the $1.5 billion settlement paid by Anthropic following a copyright dispute. The firm will receive $3,000 for each of its 14,087 books included in the claim, putting it in line to take as much as $42 million (£32 million). Settlement payments will begin in the second half of this financial year. Bloomsbury shares jumped 1.5% to £652 at Wednesday’s market open.

    Fresnillo’s Gold Production Declines

    Fresnillo reported a decline in gold production in the first half of the year, despite an increase in the second quarter. The miner saw a 7.3% fall in production in the six months to end of June, while second-quarter volumes were up 13.8% compared to the first quarter. The firm stated it will continue to focus on efficiency, cost control, and consistent volume performance. Fresnillo shares have fallen by almost a quarter since the start of the year.

    Global Market Overview

    In the US, stocks closed sharply higher, with semiconductor stocks leading the Nasdaq to a 1.3% gain to 25,837. The S&P 500 rose 0.9% to 7,509, and the Dow Jones added 0.7%. In Asia on Wednesday, Tokyo’s Nikkei 225 fell 0.18% to 66,115.6, while China’s Shanghai Composite advanced 0.07%. Hong Kong’s Hang Seng fell 1.13%, and South Korea’s Kospi gained 0.74%. In India, both the Nifty 50 and the Sensex fell by 0.84% and 0.97%, respectively.

  • Goldman Sachs Warns Brent Crude Could Surge Past $120 on Strait of Hormuz Disruptions

    Goldman Sachs Warns Brent Crude Could Surge Past $120 on Strait of Hormuz Disruptions

    Brent crude oil prices could surge above $120 per barrel in the fourth quarter if disruptions in the Strait of Hormuz persist, according to Goldman Sachs. The investment bank, however, clarified that such a sharp rally is not its base-case expectation.

    The warning comes as global oil markets remain on edge amid renewed geopolitical tensions in the Middle East. Brent crude recently climbed above $91 a barrel following fresh hostilities involving the US and Iran, raising concerns over potential supply disruptions.

    Shipping Routes Under Pressure

    Market sentiment has also been affected by threats from Iran-backed Houthi rebels in Yemen to impose a blockade on Saudi oil shipments. The warning has added to concerns over the security of key energy routes.

    With disruptions at the Strait of Hormuz, the Red Sea has become an increasingly important alternative for transporting crude from the Persian Gulf to global markets. Any disruption along this route could further tighten supplies and push prices higher.

    In a note dated July 20, Goldman Sachs analysts said escalating tensions in the region and a sharp decline in Persian Gulf oil flows had already contributed to the recent rebound in crude prices.

    Base Case Still Points to Lower Prices

    Despite highlighting the upside risks, Goldman Sachs maintained that its central forecast assumes geopolitical tensions gradually ease. Under that scenario, the bank expects Brent crude to average around $80 per barrel in the fourth quarter and decline to about $75 per barrel next year.

    The analysts cautioned, however, that risks remain skewed to the upside because of ongoing shipping disruptions through the Strait of Hormuz and the possibility of further interruptions in the Red Sea.

    China Demand May Limit the Rally

    Goldman Sachs noted that declining global oil inventories during the second quarter have left the market more exposed to supply shocks. At the same time, weaker crude imports by China and greater demand elasticity could help contain any sustained price spike.

    For investors seeking protection from prolonged geopolitical uncertainty linked to the Middle East and Russia, the bank recommended taking a long position in the European diesel timespread between December 2026 and March 2027.

    According to the analysts, diesel markets were already tight before the latest conflict, with continued Ukrainian attacks on Russian refineries, hurricane risks, extreme summer temperatures and refinery maintenance delays adding to supply concerns.

    Brent crude futures were last trading at $88.54 per barrel. Earlier this year, prices briefly surged above $126 a barrel during the initial phase of the US-Iran conflict.

  • BTC Holds Steady Near $64K as Oil Rally and AI Uncertainty Rattle Markets

    BTC Holds Steady Near $64K as Oil Rally and AI Uncertainty Rattle Markets

    Bitcoin remained near $64,200 on Monday as traders weighed a sharp jump in oil prices against ongoing market disruption from Moonshot AI’s Kimi K3 release. Ether outperformed at $1,860, while most major tokens saw minimal movement.

    The cryptocurrency market stayed mixed. XRP held near $1.09, Solana traded around $76, BNB eased to $565, and Dogecoin remained close to $0.07. HYPE fell 10% on the week to $60.

    Oil and AI Reset Risk Appetite

    Brent crude rose as much as 4% to $91.42 a barrel, its highest level since June, following wider US and Iranian strikes that extended beyond military targets. This surge revived inflation worries just after soft US price data had eased them. Rising oil prices also pressured risk assets across markets, including crypto.

    At the same time, equities continued digesting Friday’s AI-led selloff. Moonshot AI’s Kimi K3, an open-weight Chinese model, took the top spot on a widely watched coding benchmark.

    Crypto Follows the Broader Risk Trade

    The Kimi K3 release hit semiconductor shares and pulled crypto lower into the weekend. The pressure spread into Asia on Monday, where South Korea’s Kospi fell 3.5% after a holiday break. US futures steadied later in the session. The Nasdaq 100 rose 0.5%, but the market still faced questions about the strength of the AI trade.

    For crypto, the two shocks pulled in different directions. War-driven oil supported inflation concerns and rate pressure. Meanwhile, AI weakness hit chip stocks that bitcoin has tracked closely during the month.

    With major US economic data largely out of the way, the focus this week shifts to corporate earnings. Alphabet reports on Tuesday, Tesla on Wednesday, and Intel on Thursday.

    Armstrong Rejects Mining Alarm

    Coinbase CEO Brian Armstrong dismissed Chamath Palihapitiya’s warning that AI demand could threaten Bitcoin mining. Armstrong said Bitcoin’s difficulty adjustment keeps price separate from hash power.

    Palihapitiya argued that miners could earn 10 to 20 times more by selling electricity to AI operators. He described the shift as structural, while also saying he could be wrong. He also said marginal liquidity now favors prediction markets and equities over bitcoin, pointing to daily prediction market activity that often exceeds $300 million.

    Armstrong answered that falling hash power does not determine Bitcoin’s price. He said the network adjusts automatically and keeps block production near ten minutes. He linked Bitcoin’s value to sovereign deficits rather than mining power. His remarks matched recent views that frame BTC as digital gold instead of a payments network.

    Investors will now watch major corporate earnings for further market direction.