Category: Finance

  • Avoid These LLC Formation Mistakes: Essential Guide for Non-US Founders

    Avoid These LLC Formation Mistakes: Essential Guide for Non-US Founders

    Non-US founders often follow a step-by-step online tutorial, pay the state fee, and receive a shiny LLC certificate—only to discover that their structure fails in practice. The paperwork may look complete, but the tax, banking, and compliance pieces were never set up correctly. This guide highlights the most common LLC formation mistakes non-US founders make and provides actionable fixes to build a solid foundation.

    Executive Summary

    Forming a U.S. LLC as a non-resident can be powerful, but only if the structure is built and maintained correctly. The biggest problems come from focusing solely on formation while ignoring tax reporting, banking readiness, and ongoing compliance. When non-US founders understand these risks early, they can avoid penalties, rejected applications, and legal headaches.

    Mistake 1: Thinking Formation Equals Compliance

    Many non-US founders treat the LLC certificate as the finish line. They file with a formation service, receive confirmation, and assume the company is now fully compliant. In reality, formation is only a fraction of the work. Compliance includes tax reporting, annual state filings, ownership reporting, and keeping the entity in good standing. The formation company’s job usually ends once the articles are filed.

    How to fix it: Treat formation as the starting point. After the LLC exists, build a checklist for tax filings, state renewals, registered agent maintenance, and ownership records. Map out compliance requirements before the end of the first year.

    Mistake 2: Picking the Wrong State

    Non-US founders often choose a state based on marketing rather than business reality. Some states are popular in content but are not always the right choice for a specific business model. The wrong state can create unnecessary costs, extra filings, or a mismatch with where the business truly operates.

    How to fix it: Review where your business will actually operate, bank, and pay taxes. Select a state that matches your footprint and long-term plan, not just the one you saw mentioned online.

    Mistake 3: Ignoring Foreign-Owned LLC Tax Rules

    Foreign-owned single-member and multi-member LLCs often have specific U.S. tax filing obligations that are easy to miss. Many non-US founders assume that having little or no U.S. revenue means no filings. In practice, some forms are required even when income is limited or zero. Missing information returns or incorrect corporate forms can trigger penalties.

    How to fix it: Have a tax specialist review your foreign-owned structure and explain which forms apply. Understand which returns are due even in low-revenue years, and file them on time.

    Mistake 4: Treating Banking and Payments as an Afterthought

    Some founders form the LLC and only later realize they do not know how to open a bank account, connect payment processors, or prove the business exists. Banks and payment platforms want a complete, consistent story: formation documents, tax IDs, owner identity, and a clear business description.

    How to fix it: Plan banking and payments alongside LLC formation. Prepare entity documents, EIN, identity records, and a short business profile. Choose providers that work with non-US founders and know what they expect before you apply.

    Mistake 5: Assuming the LLC Automatically Saves Tax

    A common misconception is that a U.S. LLC automatically reduces tax everywhere. In reality, tax outcomes depend on where the business is managed, where income is sourced, and how home-country rules treat foreign entities. Some high-tax countries can still tax the owner based on management or residency.

    How to fix it: Review your tax position in the U.S. and in your home country before formation. Understand how management, residency, and tax treaties affect your overall liability. Choose a structure based on clear tax planning, not assumptions.

    Mistake 6: Skipping Operating Agreements and Internal Documents

    Many non-US founders stop after the articles of organization and never create an operating agreement, management records, or internal documentation. Over time, this makes it harder to prove how the company is managed, who owns what, and how decisions are made. Operating agreements are fundamental for defining ownership and control, especially in multi-member structures.

    How to fix it: Prepare a clear operating agreement and related internal records after formation. Document ownership, management, and decision-making rules to strengthen the entity and support banking and tax compliance.

    Mistake 7: Forgetting Ongoing Compliance

    Non-US founders often assume that once the LLC is formed, it will stay valid automatically. In reality, states require annual reports, registered agent maintenance, and sometimes fees to keep the company in good standing. Forgetting these obligations can cause the LLC to fall out of good standing or even be dissolved administratively.

    How to fix it: Create a simple compliance calendar covering state renewals, tax filings, ownership reporting, and registered agent obligations. Review it at least once a year and update it whenever your structure or activity changes.

    Mistake 8: Choosing Low-Touch Services Instead of Real Guidance

    Low-cost formation services are good at filing documents quickly, but they usually stop once the certificate is issued. They do not design the full structure, explain tax filings, or help with banking and compliance. The most expensive part of LLC mistakes is correcting them after authorities have already issued penalties or notices.

    How to fix it: Use support that includes structure design, tax guidance, and compliance planning, not just document filing. The right guidance costs less than repeated penalties and restructuring.

    Frequently Asked Questions

    Are U.S. LLCs good for non-US founders?

    Yes, when formed and maintained correctly. They offer access to banking, payment processors, and a respected jurisdiction.

    Is forming the LLC enough by itself?

    No. Formation is only the first step. Ongoing tax, state, and compliance tasks are needed to keep the company in good standing.

    Do foreign-owned LLCs have special tax rules?

    Often yes. Foreign-owned single-member and multi-member LLCs can have specific filing obligations that do not apply to every domestic structure.

    Can choosing the wrong state cause problems?

    Yes. The wrong state can create extra costs, unnecessary complexity, or mismatches between operations and local rules.

    Do I need an operating agreement?

    It is strongly recommended. Operating agreements clarify ownership, control, and internal rules, which helps with banking and compliance.

    Will an LLC automatically reduce my home-country taxes?

    Not necessarily. Home-country tax rules may still apply based on management and residency.

    Can penalties be avoided?

    Many penalties are avoidable when the structure is set up and maintained correctly from the start.

    When should I get professional help?

    Before forming the LLC is ideal, and again before the first year’s tax and compliance deadlines arrive.

    Conclusion

    Non-US founders do not usually run into trouble because a U.S. LLC is a bad idea. They run into trouble because they form the entity without building the full structure: tax, banking, operating agreements, and compliance. The formation certificate alone does not protect the business. The most effective way to avoid costly mistakes is to treat LLC formation as one part of a bigger, coordinated setup. When the state, tax authorities, bank, and business records all tell the same story, the LLC becomes a stable base instead of a future risk.
  • Global Stock Markets Recap: How Major Indices Performed in 2026

    Global Stock Markets Recap: How Major Indices Performed in 2026

    Global stock markets in 2026 have experienced a dynamic year, with major indices reflecting diverse economic trends and sector-specific drivers. Here’s a concise overview of how the world’s top benchmarks have fared.

    S&P 500

    The S&P 500 continues to reflect the strength of leading U.S. companies, navigating market volatility while maintaining overall resilience. Investor confidence in corporate earnings and economic fundamentals has kept the index on a steady course.

    Nasdaq Composite

    Technology stocks remain key drivers of the Nasdaq’s performance throughout the year. Innovation in AI, cloud computing, and semiconductor sectors has fueled continued investor interest, though periodic pullbacks have occurred amid valuation concerns.

    Dow Jones

    The Dow Jones highlights steady performance from major industrial and blue-chip companies. Defensive sectors such as healthcare and consumer staples have provided stability, while cyclical industrials have benefited from infrastructure spending.

    Nifty 50

    India’s benchmark index continues attracting global investors through strong economic growth. Favorable demographics, digital transformation, and policy reforms have supported the Nifty 50’s upward trajectory, making it one of the best-performing emerging market indices.

    Sensex

    The Sensex remains supported by banking, IT, and manufacturing sector gains. Robust domestic consumption, coupled with export growth in technology services, has underpinned the index’s performance.

    FTSE 100

    The UK’s FTSE 100 reflects energy, financial, and multinational company performance. High commodity prices have boosted energy stocks, while a weaker pound has benefited exporters listed on the index.

    Nikkei 225

    Japan’s Nikkei continues benefiting from technology exports and corporate reforms. The Tokyo Stock Exchange’s governance improvements and a weaker yen have enhanced the competitiveness of Japanese exporters.

    Hang Seng

    Hong Kong’s Hang Seng remains influenced by Chinese economic developments. Regulatory shifts in mainland China and geopolitical tensions have created headwinds, but the index has shown resilience in select sectors such as technology and healthcare.

    Stay informed on global market trends by following our updates.

  • Top US Stocks Driving Strong Market Momentum in 2025

    Top US Stocks Driving Strong Market Momentum in 2025

    Several U.S. equities have consistently outperformed in recent months, buoyed by advancements in artificial intelligence, cloud computing, and digital advertising. Below is an overview of the top-performing stocks that continue to deliver robust market momentum.

    Nvidia (NVDA)

    Nvidia dominates AI chip manufacturing, benefiting from surging demand for data centers, enterprise computing, and artificial intelligence infrastructure worldwide.

    Microsoft (MSFT)

    Microsoft’s cloud services and AI-powered software continue driving revenue growth, making it a consistent performer among technology industry leaders globally.

    Apple (AAPL)

    Apple’s ecosystem, premium devices, and expanding services business generate resilient revenue, supporting long-term investor confidence despite competitive technology markets.

    Amazon (AMZN)

    Amazon combines cloud computing leadership with advertising, logistics, and artificial intelligence investments, creating multiple high-growth revenue opportunities for shareholders.

    Meta Platforms (META)

    Meta’s AI investments and digital advertising business continue improving profitability while expanding virtual reality and social media platform capabilities globally.

    Broadcom (AVGO)

    Broadcom benefits from rising semiconductor demand, enterprise software growth, and AI infrastructure expansion, supporting consistent financial performance and shareholder returns.

    Tesla (TSLA)

    Tesla continues innovating in electric vehicles, autonomous driving technology, and energy storage, maintaining significant influence within global automotive markets.

    Alphabet (GOOGL)

    Alphabet strengthens revenue through search, cloud computing, YouTube, and artificial intelligence innovations across consumer and enterprise technology services worldwide.

    Palantir Technologies (PLTR)

    Palantir’s AI-powered analytics platforms drive enterprise and government adoption, supporting impressive revenue growth and expanding commercial customer relationships.

  • Milky Mist IPO Opens August 11: Price Band, Lot Size, and Key Dates

    Milky Mist IPO Opens August 11: Price Band, Lot Size, and Key Dates

    Milky Mist Dairy Food has announced the initial public offering (IPO) details, setting a price band of Rs. 133 to Rs. 140 per share. The IPO will open for subscription on August 11 and close on August 13, 2026. Anchor investors can place bids on August 10, a day before the public issue opens.

    The company aims to raise Rs. 1,553 crore through this offering, which includes fresh shares worth Rs. 1,428 crore and an offer-for-sale (OFS) of Rs. 125 crore. The IPO size was reduced from an earlier planned Rs. 2,035 crore. Milky Mist also raised Rs. 357 crore via a pre-IPO round.

    The lot size for the IPO is set at 107 shares. Retail investors will be allocated at least 35% of the issue, non-institutional investors 15%, and qualified institutional buyers (QIBs) up to 50%.

    Proceeds from the IPO will be used primarily for debt reduction and business expansion. Specifically, Rs. 496.8 crore will go toward repaying or reducing loans, Rs. 469.2 crore will be invested in the Perundurai plant in Tamil Nadu, and Rs. 155.3 crore will be used to purchase coolers and freezers for the distribution network.

    Milky Mist reported a 176% increase in profit for the fiscal year ended March 31, 2026, with revenue from operations rising 34%. CEO K. Rathnam expects annual revenue growth of around 30%, citing India’s protein-deficient market as a growth opportunity. The company’s products currently reach over 375,000 retail outlets across India.

    Shares are expected to list on the BSE and NSE on August 18, 2026.

  • Sovereign Gold Bond August 2026 Redemption: Six Eligible Series and Key Dates

    Sovereign Gold Bond August 2026 Redemption: Six Eligible Series and Key Dates

    Key Takeaways

    • Six Sovereign Gold Bond series are eligible for premature redemption in August 2026.
    • Investors must submit redemption requests within each series’ application window.
    • Redemption value is based on the average IBJA 999-purity gold price over the three business days before redemption.

    Six SGB Series Eligible for Premature Redemption

    The Reserve Bank of India (RBI) has confirmed the Sovereign Gold Bond (SGB) series that can be redeemed early in August 2026. All six series have completed the mandatory five-year lock-in period, giving investors a chance to exit before the full eight-year tenure ends.

    Here is the complete list of eligible series, redemption dates, and application windows:

    Bond Series Redemption Date Application Window
    SGB 2020-21 Series XI Aug 7, 2026 Jul 9 – Jul 28, 2026
    SGB 2019-20 Series IX Aug 11, 2026 Jul 10 – Aug 1, 2026
    SGB 2020-21 Series V Aug 11, 2026 Jul 10 – Aug 1, 2026
    SGB 2018-19 Series VI Aug 12, 2026 Jul 10 – Aug 3, 2026
    SGB 2019-20 Series III Aug 14, 2026 Jul 14 – Aug 4, 2026
    SGB 2021-22 Series V Aug 17, 2026 Jul 17 – Aug 7, 2026

    Five-Year Lock-In Still Applies

    Sovereign Gold Bonds carry an eight-year maturity, but RBI allows early redemption after five years. This facility is available only on the interest payment dates assigned to each series. Only investors who have held the bonds for at least five years from the issue date are eligible for premature redemption.

    How the Redemption Price Is Set

    The redemption value is not fixed. RBI calculates it as the simple average of the closing price of 999-purity gold over the three business days immediately before the redemption date. The official prices published by the India Bullion and Jewellers Association (IBJA) are used for this calculation. This means the payout tracks current market conditions closely.

    How to Submit a Redemption Request

    Eligible investors must file their redemption requests within the specified window. Applications are accepted by banks, post offices, Stock Holding Corporation of India Limited (SHCIL), and authorised stockbrokers, depending on where the bonds were originally purchased. After processing, the redemption amount is credited to the investor’s linked bank account.

    Missing the deadline means waiting for the next eligible redemption date or holding the bond until full maturity. Timely submission is essential for anyone planning an early exit.

    Part of a Larger Redemption Schedule

    The August calendar is part of RBI’s broader redemption schedule for the first half of the financial year. Between April and September 2026, 33 SGB tranches are eligible for premature redemption. This gives bondholders across multiple series ample time to plan their next move and prepare the required paperwork.

    Why Gold Investors Are Paying Attention

    Sovereign Gold Bonds continue to draw interest because they combine market-linked gold exposure with a fixed 2.5% annual interest on the original investment. With gold prices remaining strong, many investors are weighing the benefits of early redemption versus holding until maturity. Since no new SGB issues have been launched after February 2024, existing series have become even more valuable in investor portfolios.

    Frequently Asked Questions

    Which SGB series can be redeemed in August 2026?

    The six eligible series are SGB 2020-21 Series XI, SGB 2019-20 Series IX, SGB 2020-21 Series V, SGB 2018-19 Series VI, SGB 2019-20 Series III, and SGB 2021-22 Series V.

    When can SGB investors redeem before maturity?

    Premature redemption is allowed after five years from the issue date, but only on the fixed interest payment dates announced for each series.

    How is the SGB redemption price calculated?

    RBI uses the simple average of the closing prices of 999-purity gold for the three business days preceding the redemption date, based on IBJA rates.

    Where can investors submit redemption requests?

    Applications can be submitted through the bank, post office, SHCIL, or authorised stockbroker where the bonds were purchased.

    What happens if an investor misses the application deadline?

    They will not be able to redeem in the current window and must wait for the next eligible redemption date or hold the bond until its eight-year maturity.

  • India Unveils Tax Reforms to Lure Offshore Fund Managers and Boost Foreign Investment

    India Unveils Tax Reforms to Lure Offshore Fund Managers and Boost Foreign Investment

    India has proposed significant tax reforms aimed at easing rules for offshore funds managed by Indian-based managers, as part of the Taxation and Other Laws Amendment Bill, 2026. The government says the changes seek to promote fund management activity and provide tax certainty, in a bid to attract foreign capital after recent overseas outflows and rupee pressure.

    The draft bill removes eight of the existing 13 safe harbour conditions, including minimum corpus tests, investor thresholds, ownership caps, and portfolio restrictions. Funds can now appoint India-based managers without triggering a taxable business connection solely through that arrangement. However, five safeguards remain: Indian residents cannot directly hold more than 5% of a fund’s corpus, the fund must remain non-resident, and it cannot control an Indian business.

    Girish Vanvari of Transaction Square noted that the proposal substantially reduces the risk of a taxable connection. Nehal Sampat, a PricewaterhouseCoopers partner, said the measure would help offshore funds hire onshore managers. EY India’s Tejas Desai added that the changes offer more flexibility for global structures. The reforms also support India’s broader push to bring more fund management activity onshore, aligning with Finance Minister Nirmala Sitharaman’s call for more foreign capital.

    In addition, the bill extends tax incentives for electronics contract manufacturing, granting a ten-year extension to the existing five-year exemption through 2040-41. Foreign companies supplying capital goods to Indian electronics manufacturers can use the exemption, and certain component sales through customs-bonded areas qualify. Specified foreign firms trading rough diamonds in notified special zones receive a 15-year tax holiday. Simpler rules for data centres allow eligible facilities to operate through ownership or leasing, reducing procedural steps.

    The bill also replaces a June ordinance for foreign portfolio investors in government securities, exempting qualifying interest income and capital gains from Indian tax. The government circulated the draft among lawmakers and may introduce it in Parliament this week; measures require parliamentary approval before taking effect.

  • Jason Blackhurst: Leading Visa’s Fraud Prevention and AI-Driven Risk Solutions

    Jason Blackhurst: Leading Visa’s Fraud Prevention and AI-Driven Risk Solutions

    Early Life and Education

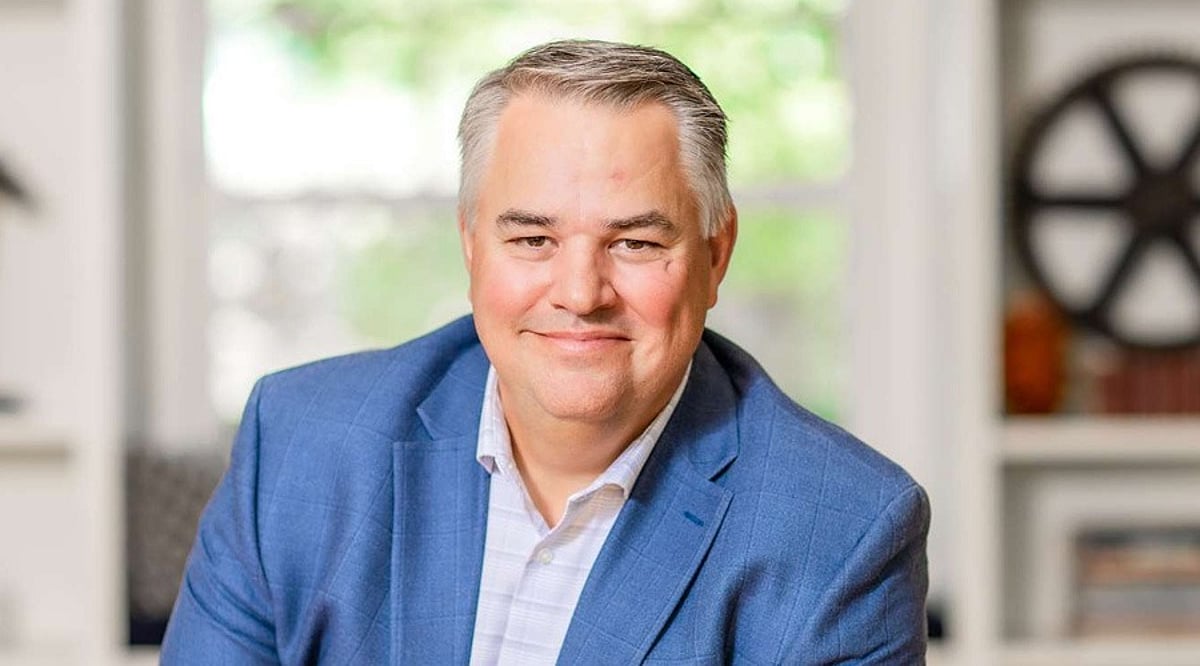
    Jason Blackhurst earned a degree in Business Administration from Warner Pacific University between 1995 and 1997. Before entering the corporate world, he served six years in the United States Navy, which instilled a disciplined, mission-focused leadership style that would define his career.

    Professional Career

    Blackhurst has spent over a decade at Visa, currently serving as Senior Vice President & Head of Featurespace & Acceptance Risk Solutions. He previously held the role of SVP Innovation and Strategic Partnership. From 2008 to 2015, he was SVP eCommerce Product Executive at Bank of America, and earlier held leadership positions at Vesta, Polestar Communications, and Concentrex, focusing on online banking and global operations. Following Visa’s acquisition of Featurespace in March 2025, Blackhurst succeeded retiring CEO Martina King to lead Featurespace and Acceptance Risk Solutions.

    Business Intervention in AI

    Featurespace enhances Visa’s global risk infrastructure with AI-based fraud prevention technologies, including:

    • Adaptive Behavioral Analytics: A self-learning platform that creates individual behavioral profiles and detects anomalies in real-time.
    • TallierLTM™: The world’s first generative Large Transaction Model, pre-trained on billions of transactions to uncover hidden fraud patterns, delivering a 71% improvement over industry standards.
    • Automated Deep Behavioral Networks: A deep learning architecture using recurrent neural networks to protect against scams, account takeover, and card fraud.
    • Card Fraud: Tailored for the card and payments industry; partners like TSYS reduced fraud losses by 39% and false declines by 70%.
    • Scam Detect: Addresses the growing threat of Authorized Push Payments with adaptive capabilities that keep banks ahead of fraudsters.

    Business Achievements

    Featurespace has become a globally recognized fraud prevention platform, expanding its enterprise footprint through Visa’s ecosystem. It reinforced its Cambridge, UK presence with a six-year office lease and broadened transit payments via Visa Ready for Transit, partnering with multiple technology providers for contactless public transport payments worldwide.

    Controversies

    No serious public controversies have been associated with Jason Blackhurst. He has built a reputation as a steady, experienced operator across banking, e-commerce, and payment risk technology, culminating in his current leadership of Featurespace within Visa’s global risk and identity solutions portfolio.

  • FTSE 100 Rises 44 Points on US-Iran Peace Optimism; BP and HSBC Post Strong Earnings

    FTSE 100 Rises 44 Points on US-Iran Peace Optimism; BP and HSBC Post Strong Earnings

    The FTSE 100 opened 40.58 points higher at 10,898.28 on Tuesday, buoyed by renewed hopes of a diplomatic resolution between the United States and Iran. The positive sentiment was further supported by robust corporate earnings from BP and HSBC, along with a flurry of other company updates.

    Market Movers

    Brent crude futures climbed 1.46% to $84.99 per barrel, while US West Texas Intermediate (WTI) rose 0.70% to $80.90. Sterling edged lower against the dollar, slipping to $1.3423 from $1.3425, and fell to €1.1664 against the euro from €1.1669.

    Top Gainers

    Antofagasta led the risers, surging 3.10% to 3,793p. Babcock International Group and BAE Systems both advanced 2.66%, reaching 1,177p and 2,200p respectively. Anglo American gained 2.54% to 3,799p, Rio Tinto added 2.30% to 7,252p, and Endeavour Mining rose 2.22% to 3,595p.

    Biggest Losers

    On the downside, Smith & Nephew plunged 5.76% to 1,128p. Coca-Cola Europacific Partners fell 4.16% to 7,725p, and Admiral Group declined 2.00% to 3,726p. Next slipped 1.24% to 14,715p, Coca-Cola HBC eased 0.94% to 4,838p, and Games Workshop Group edged 0.57% lower to 19,120p.

    BP Doubles Profit

    BP reported a sharp increase in second-quarter earnings, with underlying replacement cost profit surging to $5.7 billion from $2.4 billion a year earlier and $3.2 billion in the first quarter. Higher oil and gas prices and stronger refining margins offset lower production. Reported profit attributable to shareholders rose to $3.9 billion from $1.6 billion. Operating cash flow jumped 73% year-on-year to $10.9 billion, and net debt was reduced to $22.3 billion from $25.3 billion at the end of March.

    HSBC Beats Forecasts

    HSBC announced a fresh $1 billion share buyback after first-half profit rose 23% to $19.5 billion, beating analyst expectations. Second-quarter profit jumped 60% to $10.1 billion, surpassing the consensus estimate of $9.51 billion. The result was flattered by a $2.1 billion charge related to Bank of Communications taken a year earlier.

    Travis Perkins Cuts Dividend

    Travis Perkins reduced its dividend from 4.5p to 4p after warning of a slump in construction activity and price uncertainty. The company reported a 1.8% drop in first-half revenue to £2.3 billion. Shares have fallen 10% since the start of the year.

    Global Market Overview

    In the US, the Dow Jones rose 1.3%, the S&P 500 climbed 1.5%, and the Nasdaq jumped 2.1%, supported by lower oil prices, stronger manufacturing data, and easing concerns about a hawkish Federal Reserve. In Asia, Tokyo’s Nikkei 225 rose 0.32% to 63,957.53, China’s Shanghai Composite gained 0.33%, while Hong Kong’s Hang Seng declined 0.77%. South Korea’s Kospi edged higher by 1.62%. In India, both the Nifty 50 and the Sensex fell by 1.18% and 0.39%, respectively.

    Disclaimer: This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before making financial decisions.

  • Constructing a Multi-Layered Retirement Plan: Beyond a Single Income Stream

    Constructing a Multi-Layered Retirement Plan: Beyond a Single Income Stream

    Retirement planning becomes more believable when it is not built around one heroic assumption. One pension will take care of everything. One property will give rent forever. One market investment will keep compounding smoothly. One child will support the parents if needed. These are not poor thoughts, but they are too narrow for a long retirement. A person retiring at 60 may have to plan for 25 or 30 years of expenses. That is a long time for any single income source to behave perfectly.

    A better retirement plan has layers. Some layers give predictable income. Some create growth. Some are there for emergencies. Some are tax-efficient. The mix is personal, but the principle is fairly steady: do not make your post-retirement life wait on one cheque, one tenant, one interest rate, or one market cycle.

    The Three-Bucket Approach to Retirement Income

    A useful first draft is to divide retirement money into three buckets. It is not a textbook rule, just a practical way to keep the plan from becoming too clever.

    • Bucket 1: Predictable Income. Covers essential monthly expenses through pensions, annuities, or fixed deposits.
    • Bucket 2: Growth Investments. Equities, mutual funds, or real estate for long-term inflation protection.
    • Bucket 3: Emergency Reserve. Cash or liquid assets for unexpected costs like medical bills or home repairs.

    This structure reduces emotional pressure. When monthly expenses are covered through predictable sources, growth investments can be allowed more time. When emergency money is separate, a medical bill or home repair does not force the sale of long-term assets at an awkward time.

    Why Guaranteed Income Has a Place in the Plan

    Many people, especially younger earners, look at retirement only through return percentages. That is understandable. Growth matters. But income certainty also has its own value after salary stops. A retirement plan that offers regular income, such as an annuity or pension-style product, can act as the base layer. It may not be the loudest part of the portfolio, but it can be the part that quietly pays the electricity bill, grocery bill, and medicine bill every month.

    This is where retirement plans from life insurance companies often enter the discussion. They can be used to convert a corpus into a structured income stream, sometimes for life, depending on the option chosen. For a retiree who does not want to actively manage every rupee at 70 or 75, that predictability has a certain dignity to it.

    Do Not Ignore Inflation

    Inflation rarely feels dramatic in one year. It works slowly. A monthly expense of $60,000 may become $90,000 or more over time, depending on inflation and lifestyle changes. Medical expenses and domestic support can rise faster than general household expenses. Retirement planning should therefore include assets that have some growth potential, not only fixed payouts.

    • Keep some money in stable income products for routine expenses.
    • Keep a growth allocation for expenses that will rise over 10, 15, or 20 years.
    • Review the withdrawal rate every year instead of assuming the first-year budget will remain useful forever.
    • Do not use all retirement money for one long lock-in unless liquidity has been separately planned.

    Rental Income Is Useful, but It Needs a Backup

    Many households treat rent as a retirement plan. It can be a good income source, especially if the property is well-located and debt-free. But rental income has its own maintenance calendar. There can be months without tenants, repairs, society expenses, property tax, and occasionally a tenant who is late with payment. So rent can be one layer, not the whole floor.

    If rental income is part of the plan, keep a small reserve only for property expenses. This prevents repair costs from eating into monthly retirement spending.

    A Simple Sequence for Building the Plan

    1. Estimate essential monthly expenses separately from lifestyle expenses.
    2. List existing assured income sources such as pension, annuity, rent, and interest income.
    3. Calculate the gap between expenses and assured income.
    4. Use retirement plans, deposits, or annuity options to cover part of that gap.
    5. Keep growth assets for inflation, future healthcare, and discretionary goals.
    6. Maintain one emergency fund that is not linked to market value or tenant payment.

    Tax and Documentation Should Be Part of the Plan

    Retirement income can come from many sources, and each may be taxed differently. Interest, pension, annuity income, capital gains, and withdrawals need separate treatment. It is worth using an income tax calculator before the financial year begins, not only at return-filing time. The difference between gross income and post-tax income can be meaningful in retirement.

    Documentation is equally important. Keep nomination details updated, maintain statements, and make sure your spouse or another trusted family member knows where the records are. A retirement plan that only one person understands is too fragile, even when the investments are good.

    Final View

    A retirement plan should feel like a system, not a single bet. Predictable income can take care of everyday expenses. Growth assets can deal with inflation. Emergency funds can protect the plan from sudden withdrawals. Insurance-linked retirement plans, pension products, deposits, market assets, and rental income can all have a role, depending on the household. The sensible plan is the one where no single source is carrying the full weight of the future.

  • FamApp Review: All-in-One UPI Payment, Prepaid Card, and Money Management App

    FamApp Review: All-in-One UPI Payment, Prepaid Card, and Money Management App

    FamApp is a distinctive fintech mobile application that combines UPI payment, prepaid card services, and money management into a single platform. It enables users to handle their finances quickly and easily through transactions, payments, rewards, and expense management. The app focuses on delivering fast, efficient, and user-friendly payment services alongside comprehensive financial tools. Key benefits include digital payments, cashback rewards, and streamlined money management.

    General Information

    • Founded in: 2019
    • Platform Support: Android, iOS
    • Download: Click Here

    Main Features of FamApp

    • Safe UPI Transactions: Send money, pay merchants, recharge SIMs, and pay utility bills directly through the app.
    • Prepaid Card Services: Set spending limits, track expenses, and maintain a full transaction history for better financial control.
    • Cashbacks and Rewards: Earn incentives, cashback, and exclusive discounts from partner merchants on everyday digital transactions.
    • QR Code & Instant Transfers: Support for QR code payments, bank account linking, and instant peer-to-peer money transfers.
    • Integrated Finance Hub: All-in-one app combining digital payments, prepaid cards, transaction analysis, and reward programs.

    Benefits of FamApp

    • Seamless Transactions: Unified UPI, prepaid card, and digital wallet features streamline all payments.
    • Savings & Rewards: Cashback, reward programs, and merchant discounts help users save money effortlessly.
    • Secure Payments: A robust security framework ensures hassle-free and protected transactions.
    • User-Friendly Interface: Intuitive design makes it easy to transfer money, monitor expenses, pay bills, and use prepaid cards.
    • All-in-One Financial Tool: Combines digital payments, expense tracking, and reward schemes in a single app.

    Challenges of FamApp

    • Limited Rewards: Cashback and promotions may be restricted to specific merchants and campaigns.
    • Verification Required: Access to certain financial services depends on successful identity verification and regulatory compliance.
    • Potential Delays: UPI and transaction processing may occasionally slow during peak periods due to banking partner network issues.
    • Regional Availability: Some services, prepaid card features, and promotional offers vary by location.
    • Financial Discipline: Although secure, users should maintain good financial practices and always verify transactions.

    Subscription Information

    FamApp by Trio is a free download. Basic UPI transactions and financial services are available at no cost, while premium services may be offered based on eligibility and availability.

    Support Options

    • Help Center & Learning Resources: FAQs, payment guides, UPI support articles, security resources, blog posts, product updates, documentation, and knowledge base.
    • Customer Support: Email support, customer care, payment and account support, in-app Help Center, technical assistance, and documentation.

    Conclusion

    FamApp is an integrated digital payment platform that brings together UPI transfers, prepaid cards, reward systems, and expense management. With its convenient interface, secure payment system, and comprehensive financial products, it is well-suited for daily digital payment needs. However, users should note that certain offers and services depend on eligibility and banking partnerships.