Category: Finance

  • BHEL vs NTPC: Why One PSU Power Stock Soared 63% While the Other Fell 13%

    BHEL vs NTPC: Why One PSU Power Stock Soared 63% While the Other Fell 13%

    Over the past six months, two of India’s state-owned power giants have moved in strikingly different directions. BHEL shares surged approximately 63%, while NTPC shares declined by around 13%. According to Kotak Institutional Equities, this divergence stems from contrasting market expectations regarding thermal power capacity additions, renewable energy growth, and future earnings potential.

    BHEL’s Rally Raises Valuation Concerns

    Kotak Institutional Equities noted that BHEL’s impressive share price performance suggests investors anticipate sustained demand for thermal power equipment. However, the brokerage cautioned that the company’s current market valuation—around Rs. 1.48 trillion—implies a much larger thermal capacity buildout than government estimates support.

    Kotak’s analysis indicates that BHEL would need to execute between 150 GW and 300 GW of boiler, turbine, and generator capacity over its lifetime to justify its valuation. Even when assigning 25% of BHEL’s value to non-thermal businesses, the required execution remains demanding.

    “The current market capitalization of BHEL implies 150 GW of life-time capacity execution at a 10 per cent PAT margin, with the ask increasing further to 200 GW at a 7.5 per cent PAT margin,” Kotak stated.

    The brokerage also assessed the potential profit pool from future thermal equipment orders, estimating it could range between Rs. 50,000 crore and Rs. 1 lakh crore—even with stronger equipment pricing. This figure falls short of BHEL’s current market capitalization.

    Additionally, Kotak highlighted BHEL’s historical cash generation, noting that the company produced approximately Rs. 7,100 crore in free cash flow between FY2007 and FY2026, compared with adjusted profit after tax of Rs. 38,300 crore during the same period. “This calculation does not reflect any time value for revenues/profits, which can increase the ask further,” the brokerage added.

    NTPC’s Decline Linked to Slower Thermal Growth

    NTPC shares fell about 13% over the past six months, with Kotak attributing much of the weakness to expectations of slower near-term earnings growth. Reduced thermal capacity additions in recent months have also weighed on the outlook for the state-owned power producer.

    Meanwhile, India continues to expand its renewable energy and storage capacity. Kotak said this growth has introduced uncertainty regarding the pace of future thermal power development, as solar power paired with battery storage becomes increasingly competitive in the electricity market.

    Kotak’s reverse valuation analysis suggests NTPC would need to add approximately 42 GW of thermal capacity over time. In comparison, the Central Electricity Authority expects India to add about 86 GW of thermal capacity between FY2027 and FY2036.

    Private players could capture a portion of that expansion. For instance, the Adani Group has targeted roughly 4 GW of thermal capacity additions annually between FY2027 and FY2032, meaning NTPC would not receive the entire future thermal opportunity.

    Renewable Expansion Shapes the Outlook

    Kotak anticipates India may add around 100 GW of new thermal power capacity over the longer term. The brokerage noted that rising solar generation and battery storage could limit the need for a much larger thermal buildout.

    This scenario creates distinct valuation questions for BHEL and NTPC. NTPC’s valuation reflects expectations for future power generation capacity, while BHEL’s valuation hinges on equipment orders and margins from thermal projects.

    Kotak acknowledged that thermal generation and equipment assets carry uncertain long-term value. However, the brokerage believes BHEL’s current valuation assumes thermal capacity additions that appear higher than government projections.

    The contrasting share price performance underscores the market’s assessment of thermal additions, renewable energy growth, and future earnings. While BHEL has sharply outperformed NTPC over the past six months, Kotak’s analysis reveals that both valuations remain closely tied to India’s evolving power capacity mix.

  • 5 Essential Mutual Fund Books to Sharpen Your Investing Skills in India

    5 Essential Mutual Fund Books to Sharpen Your Investing Skills in India

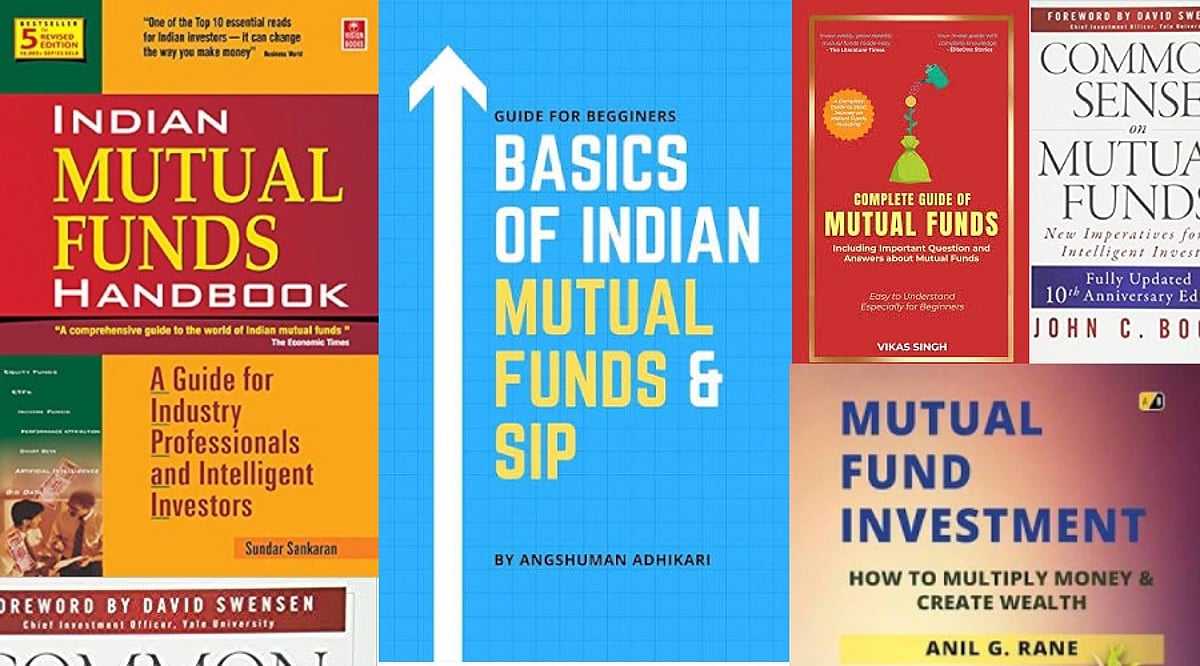
    Building strong mutual fund investing skills begins with the right knowledge. The best books explain fund selection, portfolio construction, and long-term investing using practical frameworks. Following a structured reading roadmap helps Indian investors make informed decisions and build disciplined wealth creation habits.

    Most Indian investors lose money not from picking bad funds, but from investing without a clear framework or process. Five books, read in the right order, build four distinct skills: fund basics, fund evaluation, portfolio construction, and emotional discipline. Books are selected for practical value, Indian market relevance, and principles that hold across market cycles.

    Every market correction produces the same behavior. Investors scan social media, chase last year’s top-performing funds, and reshuffle portfolios on impulse. Months later, many realize the problem was never the fund. It was the absence of a process. One well-chosen book can close that gap faster than years of trial and error. Monika Halan’s Let’s Talk Mutual Funds has done exactly that for a wide range of Indian investors by teaching them how to think before they invest, not after.

    The books in this guide are not ranked by popularity. Each one is chosen for the specific investing skill it develops. Read them in order, and the effect is cumulative.

    The Four Skills That Actually Drive Investment Success

    Good mutual fund investing is not one skill. It is four. First, understand what funds are and how they work. Second, learn to evaluate them without relying on tips or rankings. Third, build a portfolio that fits your goals and risk tolerance. Fourth, stay rational when markets move against you. Most investors develop the first skill and skip the rest. That is where the damage happens.

    Let’s Talk Mutual Funds — Monika Halan

    Skill Built: Fund Basics

    Halan writes for real people, not finance professionals. She explains SIPs, NAV, fund categories, and risk using everyday Indian financial situations. The book is grounded in local regulations and household budgeting realities, which makes it immediately useful for first-time investors.

    Her central point is worth repeating: choose funds based on your goals, not on recent performance tables. Investors who miss this early tend to keep chasing returns for years. The book does not go deep into fund evaluation. That is intentional. It is designed to build a foundation, and it does that well.

    Indian Mutual Funds Handbook — Sundar Sankaran

    Skill Built: Fund Evaluation

    Once the basics are clear, the next step is learning to read a fund properly. Sankaran walks through scheme documents, factsheets, expense ratios, and fund manager assessment with more detail than most Indian investing books attempt.

    This is the reference that helps investors stop depending on third-party rankings and start forming their own views. It pairs naturally with Common Sense on Mutual Funds, which extends the conversation on costs.

    Common Sense on Mutual Funds — John C. Bogle

    Skill Built: Cost Awareness

    Bogle’s argument is direct. Reducing costs does more for long-term wealth than identifying the next top-performing fund. For Indian investors still in regular plans, this insight alone can translate into a material difference over a decade or more. Every percentage point saved in annual fees compounds quietly in the background. Most investors underestimate how much that adds up.

    The Four Pillars of Investing — William J. Bernstein

    Skill Built: Portfolio Construction

    Bernstein moves the conversation away from individual fund selection toward how a portfolio holds together as a whole. He covers diversification, rebalancing, and long-term planning in a way that is structured without being dense. This is the right book to read after fund evaluation is clear but before a long-term portfolio is locked in.

    The Intelligent Investor — Benjamin Graham

    Skill Built: Emotional Discipline

    Graham wrote this for stock investors, but the core lessons apply directly to anyone holding mutual funds through a volatile market. His framing of “Mr. Market” remains the clearest explanation of why reacting to short-term price moves is almost always a mistake. Chapters 8 and 20 carry the most practical value for mutual fund investors and are worth reading more than once.

    Read Them in this Sequence

    Start with Let’s Talk Mutual Funds to build a solid foundation. Move to the Indian Mutual Funds Handbook to learn fund evaluation. Follow with Common Sense on Mutual Funds to understand what fees actually cost over time. Then read The Four Pillars of Investing before constructing a diversified portfolio. Finish with The Intelligent Investor to develop the discipline that separates long-term investors from short-term reactors. The sequence matters. Each book builds on the one before it.

    Final Thoughts

    The investors who hold steady through ten or twenty years of market cycles are rarely the ones who picked the best fund at the right time. They are the ones who built a clear process early and trusted it when things got uncomfortable. These five books do not promise shortcuts. They build the kind of judgment that holds up across market conditions, economic shifts, and personal financial changes. That is what makes them worth reading.

  • Top 10 Personal Finance Books to Master Money in 2026

    Top 10 Personal Finance Books to Master Money in 2026

    Managing money well depends as much on behavior as on financial knowledge. The right books can help build better saving, investing, and spending habits over time. Timeless principles remain valuable even as markets, technology, and personal finance continue to evolve.

    A budgeting app can track spending in seconds. It cannot explain why a person overspends every payday despite knowing better. That gap between knowing and doing is where books still earn their place, and it is wider in 2026 than it was five years ago, with gig income, AI-driven job cuts, and market swings reshaping how people relate to money.

    Here are the ten worth reading, grouped by financial stage rather than ranked by popularity.

    Strongest Starting Trio

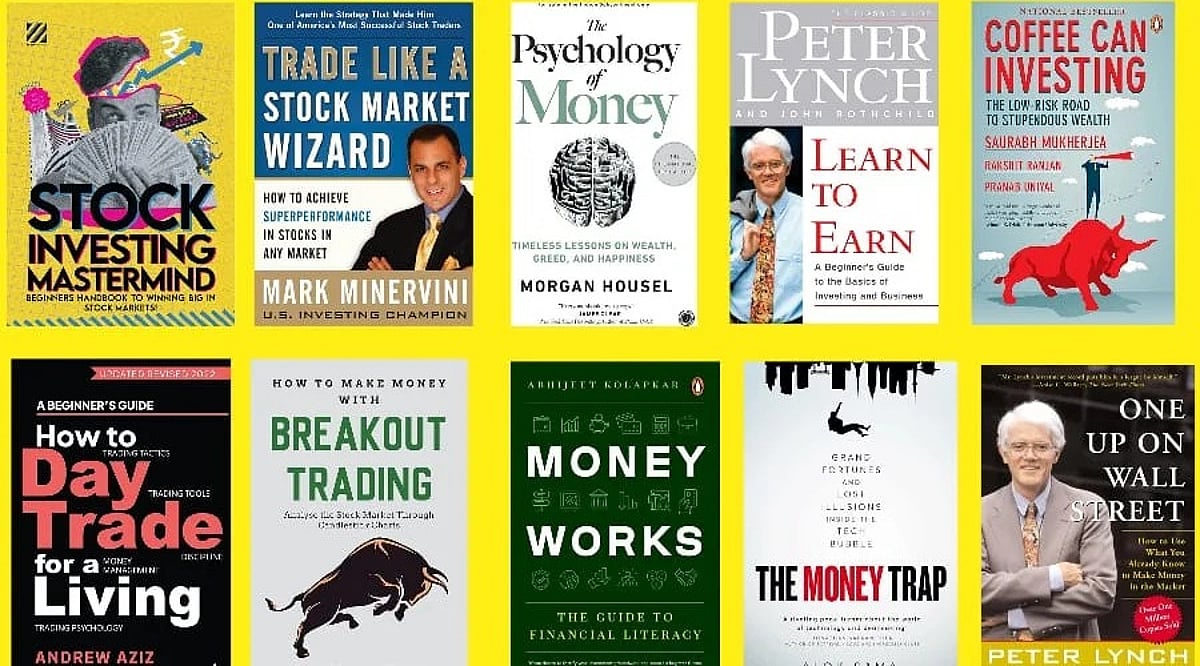
    Most readers, regardless of stage, gain the most from three books together: The Psychology of Money, I Will Teach You to Be Rich, and The Simple Path to Wealth. One reshapes how money is understood. One provides a working routine for daily decisions. One builds a durable investing foundation. Together they cover the three most common failure points: poor instincts, no system, and fear of investing.

    For Money Mindset and Behavior

    The Psychology of Money, by Morgan Housel, explains why capable people still make poor financial decisions under stress and social pressure. Rich Dad Poor Dad, by Robert Kiyosaki, reframes how readers categorize assets and liabilities. That shift proves useful even though several of Kiyosaki’s specific claims have drawn criticism from financial professionals over the years. Housel holds up better on rereading and works well as a single starting point for anyone who reads only one book from this list.

    Financial anxiety has become routine for many readers in 2026. Layoffs tied to AI adoption and unpredictable gig income have made that anxiety a daily condition, and no budgeting app addresses it directly. Both books tackle that psychological layer instead of the numbers alone.

    For Budgeting, Debt, and Daily Money

    The Total Money Makeover, by Dave Ramsey, and I Will Teach You to Be Rich, by Ramit Sethi, solve the same problem through opposite personalities. Ramsey favors strict rules: cut up the cards, snowball the debt, and live on a fixed cash plan. It works well for readers who need firm boundaries. Sethi favors automation: build routines that run quietly in the background so willpower matters less. Neither method is wrong. They suit different temperaments.

    Get Good with Money, by Tiffany Aliche, serves a third kind of reader—someone who feels structurally lost rather than simply undisciplined, with no baseline financial education to build from. It starts several steps earlier than the other two, covering credit basics and account structure before moving into strategy. Rigid budgets tend to break under variable income, and gig work keeps growing. Sethi’s automation-first model tends to hold up better for readers without a fixed monthly paycheck.

    For Investing and Wealth Building

    The Simple Path to Wealth, by JL Collins, and The Intelligent Investor, by Benjamin Graham, are both essential but not interchangeable. Collins offers a direct, low-friction case for index investing that a reader could act on within a week. Graham offers a philosophy of value and risk that takes longer to absorb but shapes every future investment decision. Collins builds action. Graham builds judgment.

    Friends that Invest, by Simran Kaur, works as the right entry point for readers who find both intimidating. It skips theory and walks through mechanics instead: opening a brokerage account, choosing a first fund, and understanding fees. Together, Collins and Graham argue for disciplined, low-cost investing over chasing trends, a case that has only grown stronger as AI-driven volatility and a flood of new ETF products make picking individual winners harder.

    For Retirement, FIRE, and Life Design

    Die with Zero, by Bill Perkins, and Your Money or Your Life, by Vicki Robin, share a premise: most people over-save and under-live. They land in different places. Perkins argues for deliberate spending before health or energy declines, treating memories and experiences as assets with their own expiration date. Robin pushes further, asking readers to treat every purchase as hours of life spent rather than dollars traded.

    The FIRE conversation has moved past the question of early retirement itself. Higher borrowing costs and pricier healthcare have made the math harder than it looked a decade ago, shifting the real question toward what retirement is actually for. Perkins and Robin, read together, address both the numbers and the purpose behind them.

    Suggested Reading Order

    Start with The Psychology of Money to reset how money gets evaluated. Move to I Will Teach You to Be Rich for a working routine. Read The Simple Path to Wealth next to build investing confidence. From there, branch based on priority: Die with Zero for life design, or The Intelligent Investor for deeper investment judgment.

    Final Thought

    Reading ten books was never the goal. Applying one lesson from the right book, at the right stage, changes outcomes faster than collecting a shelf of titles that never get opened. That single act of follow-through will matter more in the next few years than it has in the last decade, as financial noise keeps multiplying and genuine signal gets harder to find.

  • Qonto’s Rise: How a French Fintech Disrupted SME Banking Across Europe

    Qonto’s Rise: How a French Fintech Disrupted SME Banking Across Europe

    Qonto’s Rise: How a French Fintech Disrupted SME Banking Across Europe

    Running a small business comes with countless challenges, and traditional banking often adds to the burden. Slow processes, complex paperwork, and services not tailored to their needs are common frustrations for freelancers and small companies. Qonto, a French fintech, recognized this problem and built a simpler solution. Today, it serves over 600,000 customers across eight European markets, offering a comprehensive platform for business banking, expense management, invoicing, and accounting.

    The Problem with Traditional Banking

    Many small business owners struggle with outdated banking systems that were designed for large corporations. Opening an account can take days, managing expenses is cumbersome, and even finding a simple transaction record can be time-consuming. Qonto’s founders, Alexandre Prot and Steve Anavi, experienced these issues firsthand while running their own business. They envisioned a banking service that was fast, transparent, and user-friendly—one built specifically for the needs of freelancers, startups, and small to medium-sized enterprises (SMEs).

    Qonto’s Launch and Mission

    Qonto launched in France in 2016 with a clear focus: serve business customers only. This narrow focus allowed the company to deeply understand the pain points of small firms and tailor its offerings accordingly, rather than trying to be everything to everyone. From the start, Qonto aimed to simplify business banking by combining multiple financial tools into one seamless platform.

    Simplifying Business Banking

    Qonto’s core value proposition is its intuitive online experience. Customers can open a business account, order payment cards, and track spending from a single dashboard. Business owners can also issue cards to team members with customizable spending limits. The platform integrates essential daily tasks—managing bills, invoices, expenses, and account records—in one place. Additionally, Qonto connects with popular accounting software, eliminating the need for duplicate data entry and saving business owners valuable time.

    This user-centric approach set Qonto apart from traditional banks. While legacy institutions often rely on systems designed for large enterprises, Qonto built its service around the realities of freelancers and small teams, who typically lack a dedicated finance department. The result is a suite of tools that are both time-saving and easy to understand.

    Expansion Across Europe

    After establishing a strong presence in France, Qonto expanded into other European markets, including Italy, Spain, Germany, Austria, Belgium, Portugal, and the Netherlands. The company also grew through strategic acquisitions, such as the purchase of German fintech Penta in 2022, which strengthened its position in Germany and expanded its customer base.

    Investor confidence has been robust. In 2022, Qonto raised approximately €486 million (about $552 million) in a Series D funding round led by Tiger Global Management and TCV, cementing its status as one of Europe’s most prominent fintech companies. Over the years, Qonto has helped more than 250,000 entrepreneurs establish their businesses and now employs around 1,700 people across its markets.

    The Road Ahead: Lending and a Full Banking License

    Qonto started with business accounts and payment cards, then expanded into spending, billing, and accounting tools. The company’s next major step is lending. Small businesses often need quick access to capital for inventory, staffing, or new projects, but traditional lenders can take weeks to approve loans. Qonto aims to offer a faster, smoother lending process through its platform.

    Currently operating under a payment institution license, Qonto applied for a full banking license in France in 2025. If approved, this would enable the company to offer a broader range of financial products directly, including loans and other services.

    Why Qonto’s Success Matters

    Qonto’s growth is a testament to solving a specific problem exceptionally well. Rather than attempting to revolutionize banking for everyone, it focused on a segment often underserved by traditional banks: small businesses. By providing clear tools, responsive support, and reduced paperwork, Qonto has transformed from a French startup into a serious challenger in European SME banking.

    Its story highlights that small businesses want more than just an account—they want efficiency, transparency, and tools that simplify their financial lives. Qonto delivers on that promise, and its continued expansion signals a bright future for digital-first business banking.

    Frequently Asked Questions

    1. What is Qonto?
    Qonto is a French fintech company offering digital business banking and financial management tools for freelancers, startups, and small businesses.

    2. Who founded Qonto?
    Qonto was founded by Alexandre Prot and Steve Anavi, who were motivated by their own banking frustrations while running a business.

    3. Which countries does Qonto operate in?
    Qonto operates in France, Germany, Italy, Spain, Austria, Belgium, Portugal, and the Netherlands.

    4. What services does Qonto offer?
    Qonto provides business accounts, payment cards, expense management, invoicing, accounting integrations, and financial management tools. It also plans to expand into business lending.

    5. Why has Qonto become popular among small businesses?
    Qonto’s popularity stems from its simple digital banking, quick account setup, easy expense tracking, and time-saving tools designed specifically for freelancers and small businesses.

  • Top Momentum Stocks to Watch in Q3 2026: AI Memory, Interconnects, Storage, Industrial Chips, and Infrastructure

    Top Momentum Stocks to Watch in Q3 2026: AI Memory, Interconnects, Storage, Industrial Chips, and Infrastructure

    AI-driven memory demand, high-speed connectivity, storage recovery, industrial semiconductor growth, and infrastructure expansion continue to support momentum across multiple sectors in Q3 2026. Strong earnings, improving fundamentals, and identifiable catalysts reinforce these trends. Disciplined risk management remains essential as market leadership evolves.

    What Momentum Actually Means

    A momentum stock has not simply gone up. It needs to show real strength across multiple timeframes — ideally three, six, and twelve months — relative to the wider market. Fundamentals have to move in the same direction: revenue growth, earnings beats, and expanding margins. The stock should trade above its key moving averages, confirming that the trend has staying power. A clear sector tailwind adds durability, and enough liquidity keeps the position tradeable without excessive slippage.

    Micron Technology (MU): The Memory Cycle Nobody Predicted

    Micron sits at the center of the current DRAM pricing upcycle, driven by AI servers and next-generation GPU clusters that need memory faster than the industry can supply it. The company’s fiscal Q3 2026 revenue hit $41.46 billion, a sharp jump from $23.86 billion the prior quarter and $9.30 billion a year earlier. Non-GAAP net income landed at $28.86 billion, or $25.11 per diluted share. Management has confirmed HBM4 is already shipping in high volume to its lead customer, with the next generation already in development. The momentum case rests primarily on continued strength in AI memory demand and favorable supply conditions. Cyclicality remains the risk that matters most — memory pricing can reverse fast if capital expenditure slows or a competitor floods supply.

    Credo Technology (CRDO): Riding the AI Interconnect Wave

    Credo is the highest-risk, highest-reward name on this list. It builds high-speed connectivity solutions for data-center interconnects, a niche that AI infrastructure spending has turned into a genuine growth category. Full fiscal year 2026 revenue tripled to $1.3 billion, with Q4 alone reaching $437 million, up 157% year over year. Management is now guiding for revenue growth above 80% in fiscal 2027, supported by a ramp in optical DSPs. That growth trajectory holds only as long as hyperscaler capital spending stays strong. Roughly 90% of Credo’s revenue comes from its top ten customers, a concentration that magnifies any slowdown from even one major buyer.

    Western Digital (WDC): Storage Recovery Gains Momentum

    Western Digital’s story is different from the AI-driven names above it. NAND flash pricing is recovering after years of oversupply, and enterprise storage demand is climbing alongside it. Revenue rose 45.5% year over year in the most recent quarter, with EPS of $2.72 beating consensus by a wide margin. Bank of America lifted its price target to $732 from $610 in July, citing hard disk drive demand that continues to outpace available supply. The stock has held well above its 200-day moving average through the rally, a sign the recovery has technical support behind it. Competitive pressure from Samsung and SK Hynix in NAND remains the variable worth watching into Q4.

    Microchip Technology (MCHP): Quiet Strength in Industrial Chips

    Microchip trades in a different lane entirely, serving industrial automation, automotive systems, and IoT devices through microcontrollers and analog chips. Inventory levels across those end markets are normalizing, lifting order volumes after a prolonged downturn. Earnings growth accelerated sharply in the most recent quarter, and the stock’s forward P/E of roughly 29.59x sits close to its five-year average of 26.83x. Its valuation remains notably lower than the multiples commanded by many pure AI semiconductor companies, supporting its appeal as a quality momentum stock. This combination — improving demand alongside a reasonable price tag — is what gives this pick its staying power. A slowdown in industrial spending is the clearest threat to the thesis.

    Sterling Infrastructure (STRL): Building What AI Needs to Run

    Momentum in 2026 is not confined to chips. Sterling builds the physical infrastructure that AI companies depend on: data centers, e-infrastructure, and industrial projects. Signed backlog hit $4.3 billion in Q2, up 116% year over year, while combined backlog rose 150% to $5.6 billion, giving the company years of visibility most tech names can only envy. The e-infrastructure segment alone grew revenue 192% in the quarter, with margins holding at 24%. Sterling offers exposure to the AI buildout with less of the valuation risk carried by the chipmakers above it. Project execution remains the key risk to track.

    Trading Momentum with Discipline

    Momentum works as a filter, not a strategy on its own. Check the earnings calendar before entering any position — a single miss can erase weeks of gains overnight. Trailing stops help protect profits if a stock breaks below its 50-day moving average. Spread exposure across themes rather than piling into one. Three names here carry semiconductor risk, so WDC and STRL do real work balancing the group. Exit when the fundamentals stop supporting the price, not when the price simply pulls back. That discipline is what separates traders who profit from momentum from those who just chase it.

    Final Thoughts

    The strongest momentum stocks rarely announce themselves with the loudest short-term gains. They are the companies still compounding earnings and investor confidence together long after the initial excitement fades — which is exactly where the real returns tend to show up.

  • Top 10 Stocks to Watch in August 2026: Strong Earnings and Growth Catalysts

    Top 10 Stocks to Watch in August 2026: Strong Earnings and Growth Catalysts

    August 2026 presents opportunities across AI, semiconductors, fintech, digital infrastructure, and industrials. This curated list of 10 stocks highlights companies with strong fundamentals, earnings potential, and long-term growth prospects while emphasizing diversification, valuation, and disciplined risk management for investors.

    Overview

    Indian equities entered August 2026 with improving earnings momentum as stronger Q1 FY27 results, renewed FII inflows, and a stable interest-rate outlook supported sectors including IT, banking, defence, auto, pharma, and quick commerce. Companies such as TCS, Infosys, LTIMindtree, ICICI Bank, Bajaj Finance, HAL, Sun Pharma, and Swiggy reported key financial milestones, ranging from margin expansion and profit growth to record order books and improving profitability.

    The outlook for these stocks is shaped by upcoming catalysts including large deal execution, banking and fintech expansion, defence order conversion, rural demand, AI adoption, and sector-specific risks such as valuation pressure, regulatory scrutiny, and competitive intensity.

    How the List Was Built

    Each stock combines strong quarterly performance across revenue, margin, and profit with a durable edge over peers, a specific catalyst landing in August, and enough trading volume to enter and exit without friction. Several names on this list still carry Buy or Outperform ratings from major brokerages after their Q1 FY27 results. The goal is not to chase every green number but to isolate the ones that will keep mattering past this earnings season. This selection reflects editorial analysis of public disclosures and works best as a research starting point rather than a fixed ranking.

    The Ten Stocks at a Glance

    TCS: Margin Stability Keeps it Ahead

    TCS remains the steadiest name in the group. Its Q1 FY27 revenue reached Rs 72,275 crore, up 13.9%, and it held a 24% operating margin while peers battled wage-cycle pressure. New order value hit $9.5 billion, with North America contributing roughly half. The soft spot is USD revenue growth of just 2.7%, a sign that offshore pricing remains tight even as deal volumes grow.

    Infosys: AI Demand Continues to Drive Growth

    Infosys sits closer to the center of enterprise AI adoption than any other name here. AI-linked revenue reached 8.2% of the total, and large deal value came in at $3.6 billion with 61% net new business, a stronger mix than Wipro managed in the same quarter. The company trimmed its FY27 growth guidance to 1.5–3%, a sign that discretionary spending across the sector remains cautious even as AI budgets expand.

    LTIMindtree: Fastest Growth Among Large-Cap IT

    LTIMindtree posted the fastest revenue growth among the large-cap IT names on this list, at 17.96%, ahead of HCLTech’s 14% for the same period. Profit rose 17% to Rs 1,469 crore, beating consensus, while trading at a lower multiple than most peers. That combination makes LTIMindtree one of the more attractively positioned large-cap IT stocks in this list.

    ICICI Bank: Profitability Remains the Key Strength

    ICICI Bank posted profit growth among the strongest of India’s largest private lenders this quarter, with return on assets at 2.49%, a figure brokerages flagged as best in class. Its balance sheet improved year on year, though HDFC Bank still posted a lower absolute bad-loan ratio, so ICICI’s edge sits in profitability and returns rather than having the cleanest book in the sector.

    Bajaj Finance: Record ROE Signals Continued Momentum

    Bajaj Finance had one number that stood out above the rest: return on equity crossed 20% for the first time in the company’s history. AUM grew 23.9% to Rs 5.47 lakh crore, and new loan bookings rose 20% to 16.13 million. Profit climbed 28% to Rs 6,081 crore. The stock trades at a premium NBFC multiple, which leaves little cushion if credit costs move against it in coming quarters.

    Jio Financial Services: Rapid Growth with Premium Valuation

    Jio Financial Services had a quieter quarter in absolute size but a sharp one in growth. Profit jumped 156% to Rs 830 crore, and both Jio Payments Bank and Jio Payment Solutions turned operationally positive for the first time. JioBlackRock AMC closed the quarter with Rs 18,412 crore in assets, up 21% sequentially. The business is still young, and its valuation already prices in a lot of that future growth, so any slowdown in scale-up would hit the stock harder than an established peer.

    HAL: Defense Orders Provide Long-Term Visibility

    HAL carries the most visible defense order book in the country, at Rs 2.54 lakh crore, more than seven years of revenue at current run rates and roughly 3.5 times the size of Bharat Electronics’ Rs 72,258 crore book. Results land mid-August and will shape sentiment through the rest of the quarter.

    Mahindra & Mahindra: Rural Demand Supports Growth

    Mahindra and Mahindra grew across every metric that matters, with return on equity at 23%, well past its own target, while kharif acreage points to stronger tractor demand ahead.

    Sun Pharma: Strong Domestic Business, Ongoing Regulatory Watch

    Sun Pharma kept its formulation business growing at double digits, though it still carries an active US FDA warning letter from a 2024 inspection, a reminder that regulatory risk in Indian pharma rarely disappears completely.

    Swiggy: A High-Risk Growth Bet

    Swiggy rounds out the list as the speculative name: Instamart reached contribution-margin break-even in May, a real milestone, but competition from Blinkit and Zepto keeps the stock better suited to a small position than a core holding.

    Reading the List with Discipline

    Ten names span seven sectors, and that spread matters more than any single pick. Position sizes should reflect risk: TCS and ICICI Bank warrant more weight than JFSL or Swiggy. Entries are worth staggering around pending results, HAL most of all. IT already accounts for three of the ten picks, so adding more exposure there raises concentration risk rather than reducing it. Each name deserves a second look once the next quarter’s numbers land, since a single strong print is a starting point, not a guarantee.

    Markets will keep reacting to headlines. Long-term returns come from businesses that keep executing on earnings, margins, and capital allocation quarter after quarter. Every name on this list earned its spot through verified Q1 FY27 numbers, not market excitement.

    Final Thoughts

    The next test for these ten stocks arrives fast. HAL reports mid-August, rate decisions loom for the banks, and IT demand signals for the rest of FY27 will sharpen as the quarter closes. Investors who track execution over headlines, sector by sector, will read the next data set more clearly than the market’s first reaction to it.

  • Apple’s Stock Split History: A Complete Timeline from 1987 to 2020

    Apple’s Stock Split History: A Complete Timeline from 1987 to 2020

    Apple’s Stock Splits Over the Decades

    Since 1987, Apple has executed five stock splits, each designed to make shares more accessible to retail investors while preserving overall market capitalization. Here is a timeline of each split and its context.

    • 2-for-1 Stock Split (1987): Announced on June 16, 1987, this split doubled shareholders’ holdings while halving the share price. The move aimed to increase accessibility for retail investors amid growing confidence in Apple’s future despite a competitive PC market.
    • 2-for-1 Stock Split (2000): Executed on June 21, 2000, during the dot-com boom, this split increased liquidity and encouraged broader participation as investor enthusiasm for technology companies surged.
    • 2-for-1 Stock Split (2005): Effective February 28, 2005, following the success of the iPod and strong financial performance, this split attracted additional investors while maintaining shareholder value.
    • 7-for-1 Stock Split (2014): Effective June 9, 2014, this surprising move dramatically reduced the share price, improving accessibility, liquidity, and positioning Apple for inclusion in price-weighted indexes.
    • 4-for-1 Stock Split (2020): Effective August 31, 2020, after a remarkable rally driven by iPhone, services, and wearables growth, this split lowered the entry price for investors and boosted trading activity.

    Why Apple Splits Its Stock

    Stock splits do not change a company’s overall market value or shareholder ownership percentage. Instead, they reduce the per-share price, improving affordability, increasing market liquidity, and making shares psychologically more attractive to retail investors.

    Impact on Long-Term Investors

    Apple has delivered exceptional long-term returns despite only five stock splits since 1987. Investors who held shares through each split saw their ownership multiply significantly, demonstrating how stock splits combined with sustained business growth can amplify investment potential over decades.

  • Healthcare Stocks with Steady Profit Growth: Top Picks for 2026

    Healthcare Stocks with Steady Profit Growth: Top Picks for 2026

    The healthcare sector continues to be a cornerstone of the Indian stock market, driven by demand for medicines, hospital services, diagnostics, and medical research. Several companies have maintained strong financial performance, healthy profitability, and expansion into new markets, bolstering investor confidence. Below, we profile leading healthcare companies with consistent profit growth, examining their market capitalization, valuation, profitability, returns, and financial strength.

    Sun Pharmaceutical Industries Ltd

    Sun Pharmaceutical Industries Ltd is the largest company in this list with a market capitalization of ₹4,68,110.25 crore. It is a leading drug manufacturer in India. The stock trades at ₹1,951.00 with a P/E ratio of 40.78. The stock has gained 0.57% in one day, 2.43% in one month, 15.10% in six months, and 22.30% over the year. Its price-to-book ratio is 5.58, return on equity (ROE) is 14.68%, and return on capital employed (ROCE) is 18.02%. The dividend yield is approximately 0.82%, and a debt-to-equity ratio of 0.06 indicates low leverage.

    Divi’s Laboratories Ltd

    Divi’s Laboratories Ltd operates in the laboratory and life sciences services business. The company has a market capitalization of ₹2,21,639.72 crore and trades at ₹8,349.00 per share with a P/E ratio of 86.31. Though the stock declined 0.46% in a single day, it returned 22.96% in one month, 38.58% in six months, and 36.12% in one year. The price-to-book ratio is 13.22, ROE is 16.19%, and ROCE is 18.98%. The dividend yield is 0.36%, and the company maintains a debt-to-equity ratio of 0.00—completely debt-free.

    Torrent Pharmaceuticals Ltd

    Torrent Pharmaceuticals Ltd holds a market valuation of ₹1,88,510.31 crore. The stock is quoted at ₹4,956.00 with a P/E ratio of 87.14. The stock saw a negative variation of 0.88% in the past day but gained 3.38% in one month, 25.82% in six months, and 40.63% over one year. The price-to-book ratio is 10.72, ROE is 17.19%, and ROCE is 9.24%. The dividend yield is 0.68%, and the debt-to-equity ratio of 0.85 reflects moderate borrowing. Volatility relative to Nifty is 1.52.

    Apollo Hospitals Enterprise Limited

    Apollo Hospitals Enterprise Limited is one of India’s leading hospital operators. Its market cap is ₹1,29,039.54 crore, and the stock trades at ₹8,974.50 with a P/E ratio of 66.46. The stock rose 0.72% in a day, and returns over one month, six months, and one year are 0.76%, 25.47%, and 24.83%, respectively. The price-to-book ratio is 12.93, ROE is 18.42%, and ROCE is 19.81%. Dividend yield is 0.22%, and the debt-equity ratio stands at 0.85.

    Cipla Ltd

    Cipla Ltd remains a well-established pharmaceutical company. It has a market capitalization of ₹1,19,319.91 crore. The stock closed at ₹1,477.00 with a P/E ratio of 30.76—one of the lower valuations in this group. The share price rose 1.25% in one day. One-month and six-month returns are 0.96% and 11.05%, respectively, while the one-year return is -0.65%. The price-to-book ratio is 3.46, ROE is 11.79%, and ROCE is 14.94%. Dividend yield is 0.88%, and a debt-to-equity ratio of 0.02 reflects excellent financial discipline. Volatility versus Nifty is 1.51.

    Zydus Lifesciences Ltd

    Zydus Lifesciences Ltd has a market capitalization of ₹1,10,523.42 crore. The stock is valued at ₹1,108.00 with a P/E ratio of 21.93. It decreased 1.17% in a day and 3.23% in a month. Despite recent declines, it delivered returns of 24.75% in six months and 18.79% in one year. The price-to-book ratio is 3.74, ROE is 18.02%, and ROCE is 20.19%. Dividend yield is 0.09%, and the debt-equity ratio of 0.42 indicates healthy leverage. Volatility relative to Nifty is 1.55.

    Lupin Limited

    Lupin Limited holds a market capitalization of ₹1,09,050.52 crore and trades at ₹2,385.00. The P/E ratio is 20.45, the lowest among the companies listed here. The stock slipped 0.13% in one day and 4.52% over one month, but produced 9.72% returns in six months and 28.79% in one year. The price-to-book ratio is 4.84, ROE is 26.79%, and ROCE is 28.66%—the highest figures in this group. Dividend yield stands at 0.75%, and a debt-to-equity ratio of 0.29 reflects comfortable leverage. Volatility versus Nifty is 1.37.

    Max Healthcare Institute Limited

    Max Healthcare Institute Limited operates in the hospitals and diagnostic centers segment. The company has a market capitalization of ₹1,04,373.84 crore. The stock closed at ₹1,072.40 with a P/E ratio of 72.36. The share price declined 0.70% in one day, 7.37% in one month, and 15.63% over one year, but grew 3.13% in six months. The price-to-book ratio is 9.71, ROE is 14.33%, and ROCE is 12.74%. Dividend yield is 0.19%, and the debt-to-equity ratio is 0.32. Volatility against Nifty is 1.82.

    Mankind Pharma Ltd

    Mankind Pharma Ltd is strongly positioned in prescription medicine and consumer healthcare products. It is valued at ₹99,957.42 crore. The closing price is ₹2,420.30 with a P/E ratio of 52.25. The stock decreased 0.63% in one day and 4.66% in one month. It provided returns of 17.48% over six months, while the one-year return is -5.32%. The price-to-book ratio is 6.04, ROE is 12.29%, and ROCE is 14.01%. Dividend yield is 0.04%, and the debt-to-equity ratio is 0.38. Volatility against Nifty is 1.81.

    Laurus Labs Ltd

    Laurus Labs Ltd completes this list with a market capitalization of ₹98,877.14 crore. The stock trades at ₹1,830.00 with a P/E ratio of 111.25—the highest valuation among these healthcare stocks. The stock declined 0.27% in one day but produced impressive returns of 18.37% in one month, 92.52% in six months, and 118.85% over one year—the strongest price performance in this group. The price-to-book ratio is 18.20, ROE is 17.72%, and ROCE is 19.67%. Dividend yield is 0.11%, and a debt-to-equity ratio of 0.46 reflects moderate borrowing. Volatility versus Nifty is 2.06.

    Key Takeaways

    • Healthcare companies continue to show strong financial performance across pharmaceutical and hospital segments.
    • Low debt and healthy profitability remain common strengths among several market leaders.
    • Each stock offers a different mix of valuation, growth potential, and long-term business strength.

    Final Thoughts

    India’s healthcare industry comprises strong pharmaceutical manufacturers, research organizations, hospitals, and diagnostic service firms. Sun Pharmaceutical Industries leads in market capitalization; Divi’s Laboratories has a zero-debt balance sheet; Lupin boasts the highest ROE and ROCE; and Laurus Labs delivered the best one-year stock return. Apollo Hospitals and Max Healthcare represent the hospital segment, while Cipla and Zydus Lifesciences offer well-established operations with reasonable valuations. Each company provides a unique mix of growth, profitability, valuation, and financial performance, making them significant healthcare businesses in India.

    Frequently Asked Questions

    1. Which Indian healthcare company has the highest market capitalization?
    Sun Pharmaceutical Industries Ltd leads the sector with a market capitalization of ₹4,68,110.25 crore, making it the largest drug manufacturer on the list.

    2. Which stock offers the lowest valuation based on the P/E ratio?
    Lupin Limited trades at a P/E ratio of 20.45, making it the lowest-valued stock by P/E among the top healthcare companies listed.

    3. Which stock delivered the highest 1-year return?
    Laurus Labs Ltd delivered the strongest one-year price performance in the group, with an impressive 118.85% return.

    4. Which healthcare company operates with zero debt?
    Divi’s Laboratories Ltd maintains a completely debt-free balance sheet with a debt-to-equity ratio of 0.00.

    5. Which top companies represent the hospital and diagnostic services sector?
    Apollo Hospitals Enterprise Limited (market cap: ₹1,29,039.54 crore) and Max Healthcare Institute Limited (market cap: ₹1,04,373.84 crore) represent the core hospital and diagnostic healthcare space.

    6. Which company has the highest Return on Equity (ROE) and ROCE?
    Lupin Limited reports the highest profitability metrics in the group, with an ROE of 26.79% and an ROCE of 28.66%.

    7. Which healthcare stock offers the highest dividend yield?
    Cipla Ltd provides the highest dividend yield among these companies at 0.88%, closely followed by Sun Pharmaceutical Industries Ltd at 0.82%.

    Disclaimer: This article is for informational purposes only and does not constitute investment advice. Always conduct your own research before making any investment decisions.

  • Central Banks Shift Reserves: Gold Gains Ground Over US Treasuries

    Central Banks Shift Reserves: Gold Gains Ground Over US Treasuries

    Central Banks Rethink Reserve Strategies

    Central banks worldwide are reshaping how they manage national reserves. For decades, US Treasuries were the go-to reserve asset, prized for safety, liquidity, and steady interest income. Gold held a secondary role, with most reserves parked in dollar-denominated instruments. That dynamic is now shifting.

    Over the past several years, gold has taken on a much larger role in reserve portfolios. While central banks still hold significant amounts of US Treasuries, many are accelerating gold purchases to build more balanced and resilient reserves. This strategic pivot reflects changing economic realities, geopolitical tensions, and a desire for long-term stability.

    Record Gold Buying Spree

    Central bank gold demand has surged to historic levels. Between 2022 and 2025, official gold purchases averaged roughly 1,000 tonnes annually—nearly double the 500-tonne average of the prior decade.

    The latest World Gold Council survey underscores this momentum. Nearly 89% of reserve managers expect global gold reserves to rise in the next 12 months, and 45% plan to increase their own gold holdings—the highest percentage ever recorded. Looking ahead, 83% foresee gold gaining a larger share of global reserves within five years, while 74% anticipate a decline in the dollar’s reserve share.

    Why Gold Is Gaining Favor

    Gold offers unique attributes that appeal to reserve managers in uncertain times. Unlike government bonds, gold carries no default risk and is not tied to any single country’s fiscal health or policies. This independence provides a safety net during economic stress or geopolitical upheaval.

    According to the World Gold Council survey, 90% of reserve managers value gold for its strong performance during financial crises. About 84% see it as a dependable long-term store of value, and 82% believe it enhances portfolio diversification. Geopolitical risk has also become a more prominent consideration in reserve decisions.

    Gold does have drawbacks: it generates no income, incurs storage costs, and can be volatile in the short term. Still, many central banks prioritize long-term stability over regular interest payments.

    US Treasuries Remain Relevant

    The rise in gold demand does not spell the end for US Treasuries. American government bonds still offer significant advantages, including regular interest income, deep liquidity, and the ability to support large transactions. Central banks can trade these securities quickly without major price disruptions.

    However, reserve managers are increasingly mindful of risks tied to inflation, interest rate fluctuations, rising US government debt, and geopolitical developments. These concerns are prompting many countries to spread reserves across a broader set of assets rather than concentrating in dollar-denominated securities.

    Diversification, Not Abandonment

    Commentary often frames this trend as a move away from the dollar, but the reality is more nuanced. Central banks are not dumping US Treasuries; most continue to hold substantial amounts while gradually expanding gold reserves.

    Many reserve managers allow the Treasury share to decline naturally as total reserves grow. New inflows often fund additional gold purchases rather than larger Treasury positions. This gradual approach creates a more diversified portfolio without disruptive market shifts.

    Leaders in the Shift: India, China, Poland

    Several countries exemplify this changing strategy. India has steadily increased gold reserves while trimming its US Treasury holdings, which recently fell to around $181 billion—the lowest in six years. The Reserve Bank of India has also ramped up regular gold purchases.

    China has expanded its reported gold reserves and developed a broader gold market, including additional bullion storage in Hong Kong and yuan-based gold trading, as part of efforts to reduce reliance on Western financial infrastructure.

    Poland has been one of the most aggressive buyers in 2026, acquiring 64 tonnes in the first five months alone. Other notable buyers include Kazakhstan, Singapore, and the Czech Republic, reflecting a broad global trend rather than a strategy limited to a few nations.

    A New Era for Global Reserves

    Gold prices have remained volatile in 2026, trading near US$4,043 per troy ounce after retreating from record highs. Despite this, central bank demand stays strong, supporting the long-term outlook.

    Recent data revisions suggest early-2026 gold purchases were slightly below initial estimates, but reserve managers remain confident in higher gold allocations ahead. The global reserve system is entering a new phase where gold serves as an essential pillar of security alongside US Treasuries, reflecting careful, gradual diversification rather than abrupt change.

    Frequently Asked Questions

    Why are central banks buying more gold?

    Gold provides long-term value, portfolio diversification, and protection during financial or geopolitical uncertainty.

    Are central banks selling all their US Treasuries?

    No. Most central banks still hold substantial US Treasuries while gradually increasing gold allocations.

    Which countries have increased gold reserves recently?

    India, China, Poland, Kazakhstan, Singapore, and the Czech Republic have reported notable gold purchases.

    Why do US Treasuries remain important?

    They offer liquidity, regular interest income, and access to one of the world’s largest government bond markets.

    What does this reserve shift mean for the global economy?

    It signals a move toward diversified reserve management, which could influence currency markets, international finance, and long-term economic stability.

  • How AI Is Building Adaptive Financial Ecosystems: Insights from Equiniti India’s Engineering Head

    How AI Is Building Adaptive Financial Ecosystems: Insights from Equiniti India’s Engineering Head

    Artificial intelligence is rapidly transforming financial services, enabling organizations to modernize legacy operations without compromising trust, security, or regulatory compliance. Beyond improving operational efficiency, AI is helping financial institutions accelerate software development, automate complex workflows, enhance decision-making, and deliver better customer experiences.

    For companies with long-standing industry expertise, the real opportunity lies in adopting AI responsibly. Strong governance, transparency, and human oversight are becoming just as important as innovation, ensuring businesses can unlock AI’s potential while maintaining the confidence of clients and regulators.

    Jyoti Prakash Dash, Head of Engineering at Equiniti India, believes AI will go far beyond automation to reshape how financial services are designed and delivered. In an exclusive interview, he shares Equiniti India’s AI strategy, the evolving role of engineering leaders, workforce readiness in the GenAI era, and how intelligent financial ecosystems will define the industry’s future.

    Modernizing a 200-Year Legacy with AI

    Dash explains that AI enables Equiniti to modernize complex financial services operations while preserving the trust, accuracy, and regulatory compliance clients expect. The focus is on responsible AI adoption that enhances productivity, decision-making, and customer outcomes through strong governance, transparency, security, and human oversight.

    Engineering Leadership in the AI Era

    The role of engineering leadership has evolved from managing delivery to orchestrating teams with AI capabilities. Success now depends on driving AI adoption, establishing guardrails, building AI-ready talent, and accelerating innovation without compromising quality, security, or compliance.

    Where AI Is Creating Value

    Equiniti India is embedding AI across software engineering, testing, operational processes, and data-driven decision-making. The impact is already visible through improved developer productivity, faster delivery, enhanced quality, and increased automation, allowing teams to focus on higher-value innovation and customer outcomes.

    Skills Engineers Need in the AI Era

    Engineers must develop AI fluency alongside strong fundamentals in architecture, systems thinking, data, security, and governance. At Equiniti India, significant investment is being made in AI enablement, communities of practice, hands-on learning, and responsible AI adoption to prepare teams for the future.

    Long-Term Vision: Intelligent, Adaptive Ecosystems

    Dash’s vision is to move beyond automation and build intelligent, adaptive financial services ecosystems. AI will enable better decision-making, greater personalization, stronger risk management, and faster innovation, creating sustainable competitive advantage for clients and transforming how financial services are delivered.